Subscribe for our latest news, straight to your inbox:
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Share this post
Steel flows face fresh challenges in the final quarter of 2026
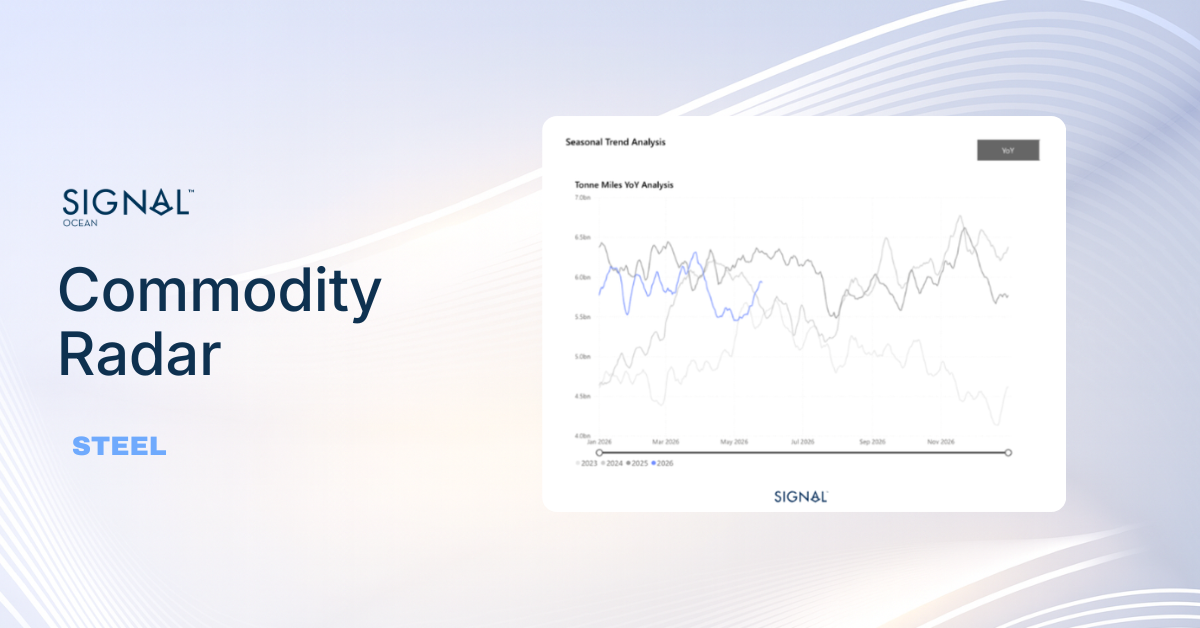
Steel flows slip into negative growth in July 2026
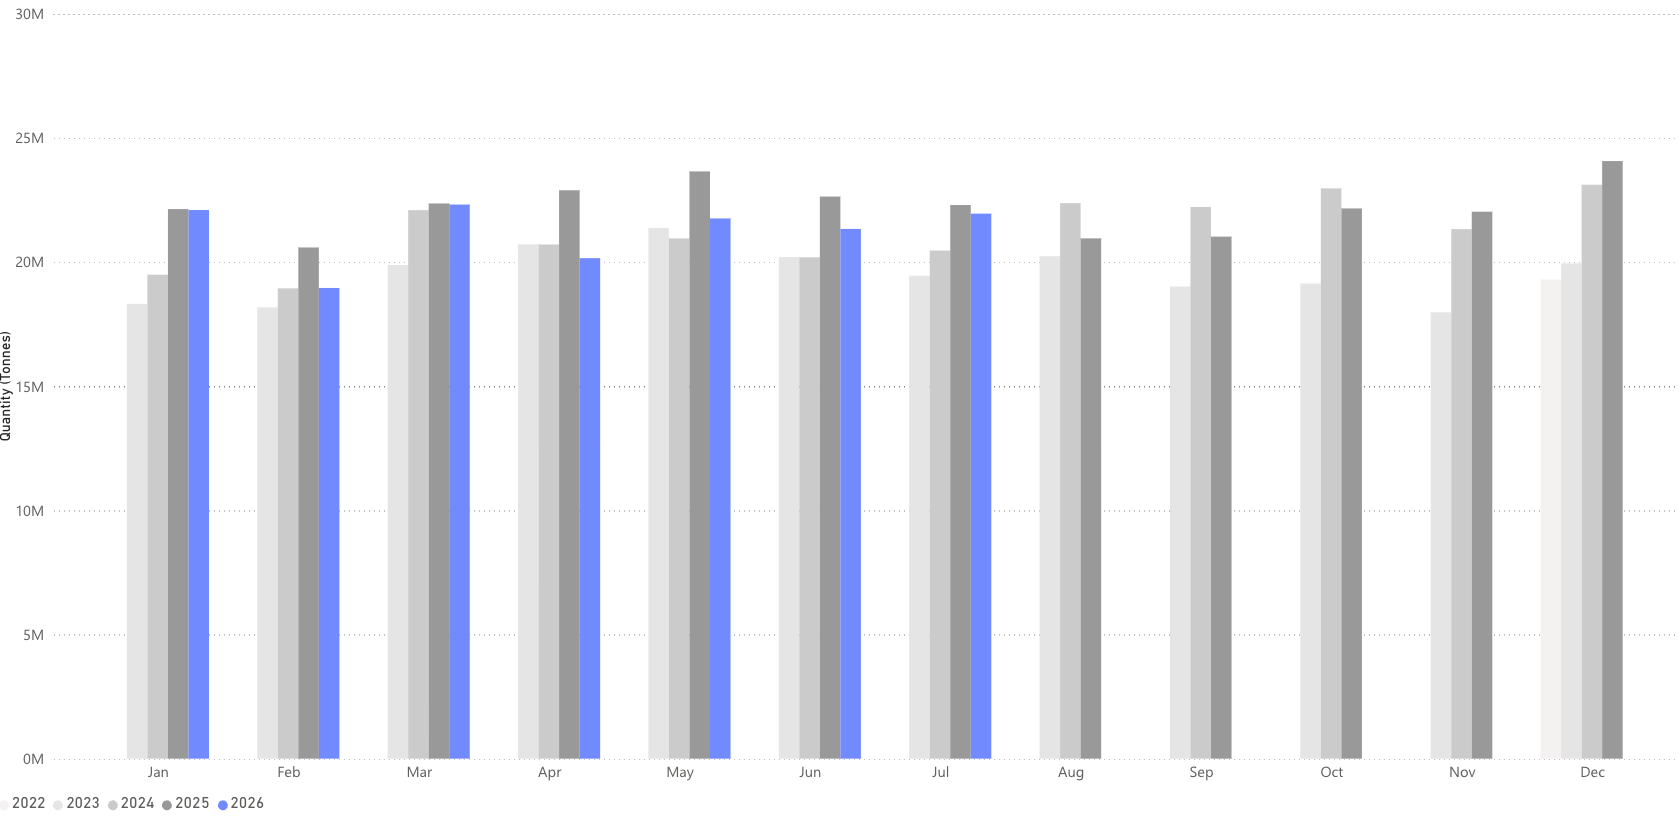
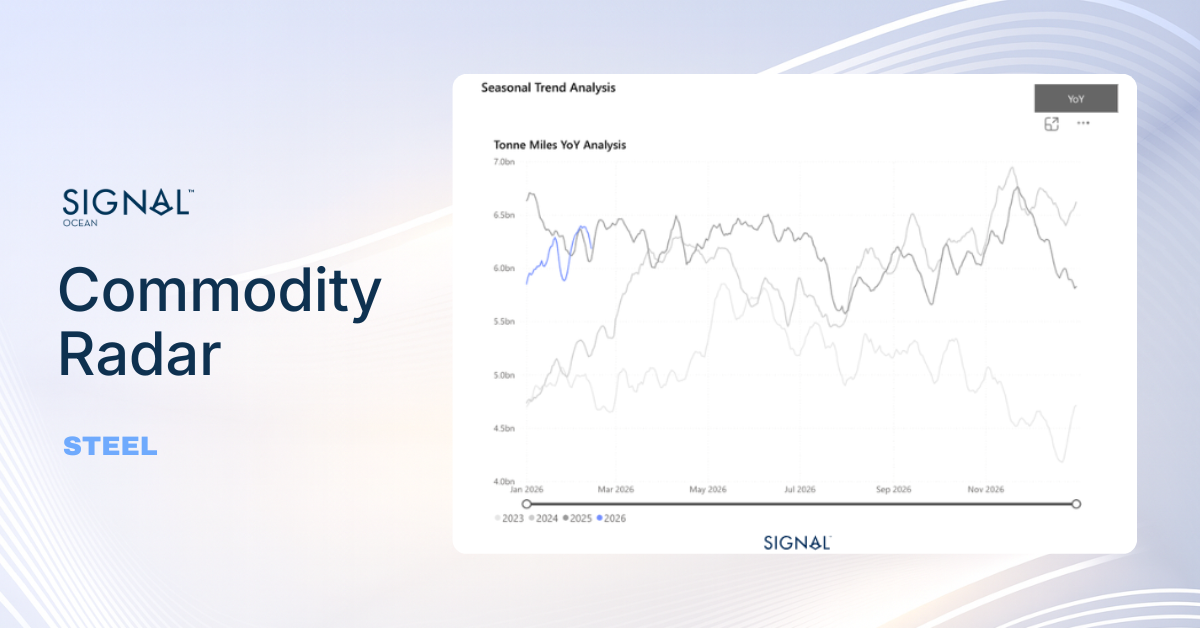
Global steel flows fall 1% y/y in July 2026 to reach 22.2 Mt.
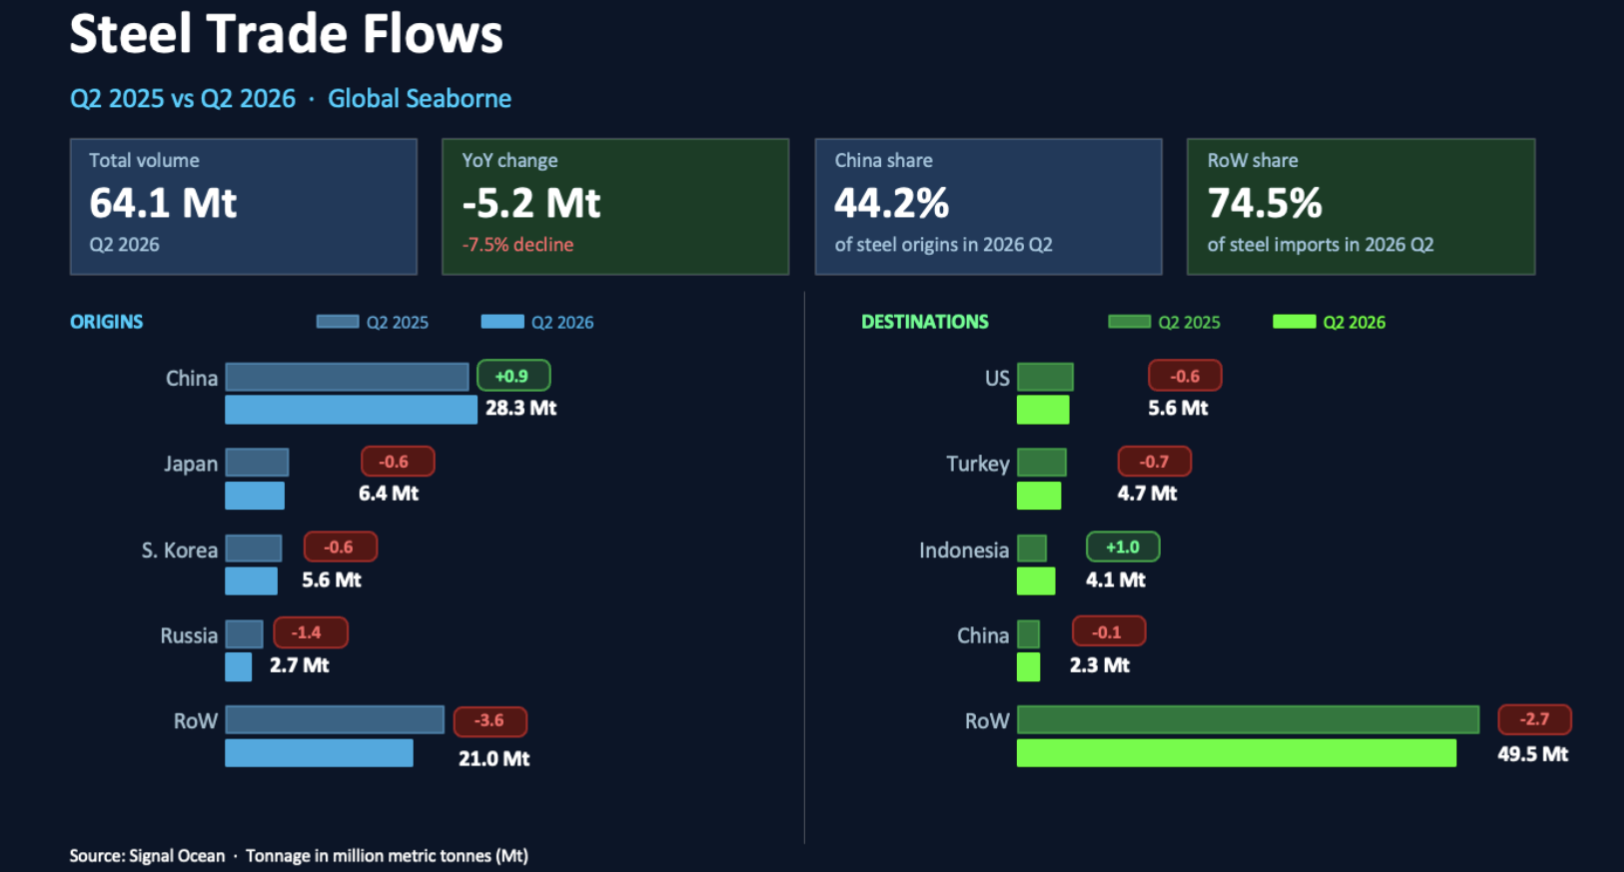
China’s share of global steel flows rises from 41.6% in July 2025 to 45.7% in July 2026, driven by a 9.1% increase in exports.
Flows from the World Ex. China fell by 7.9%, to 12.0 Mt in July.
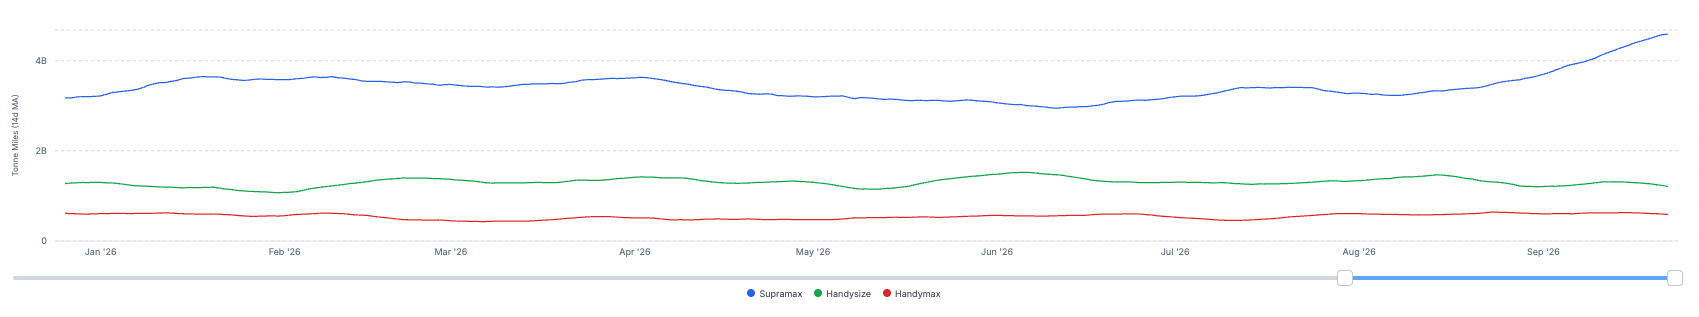
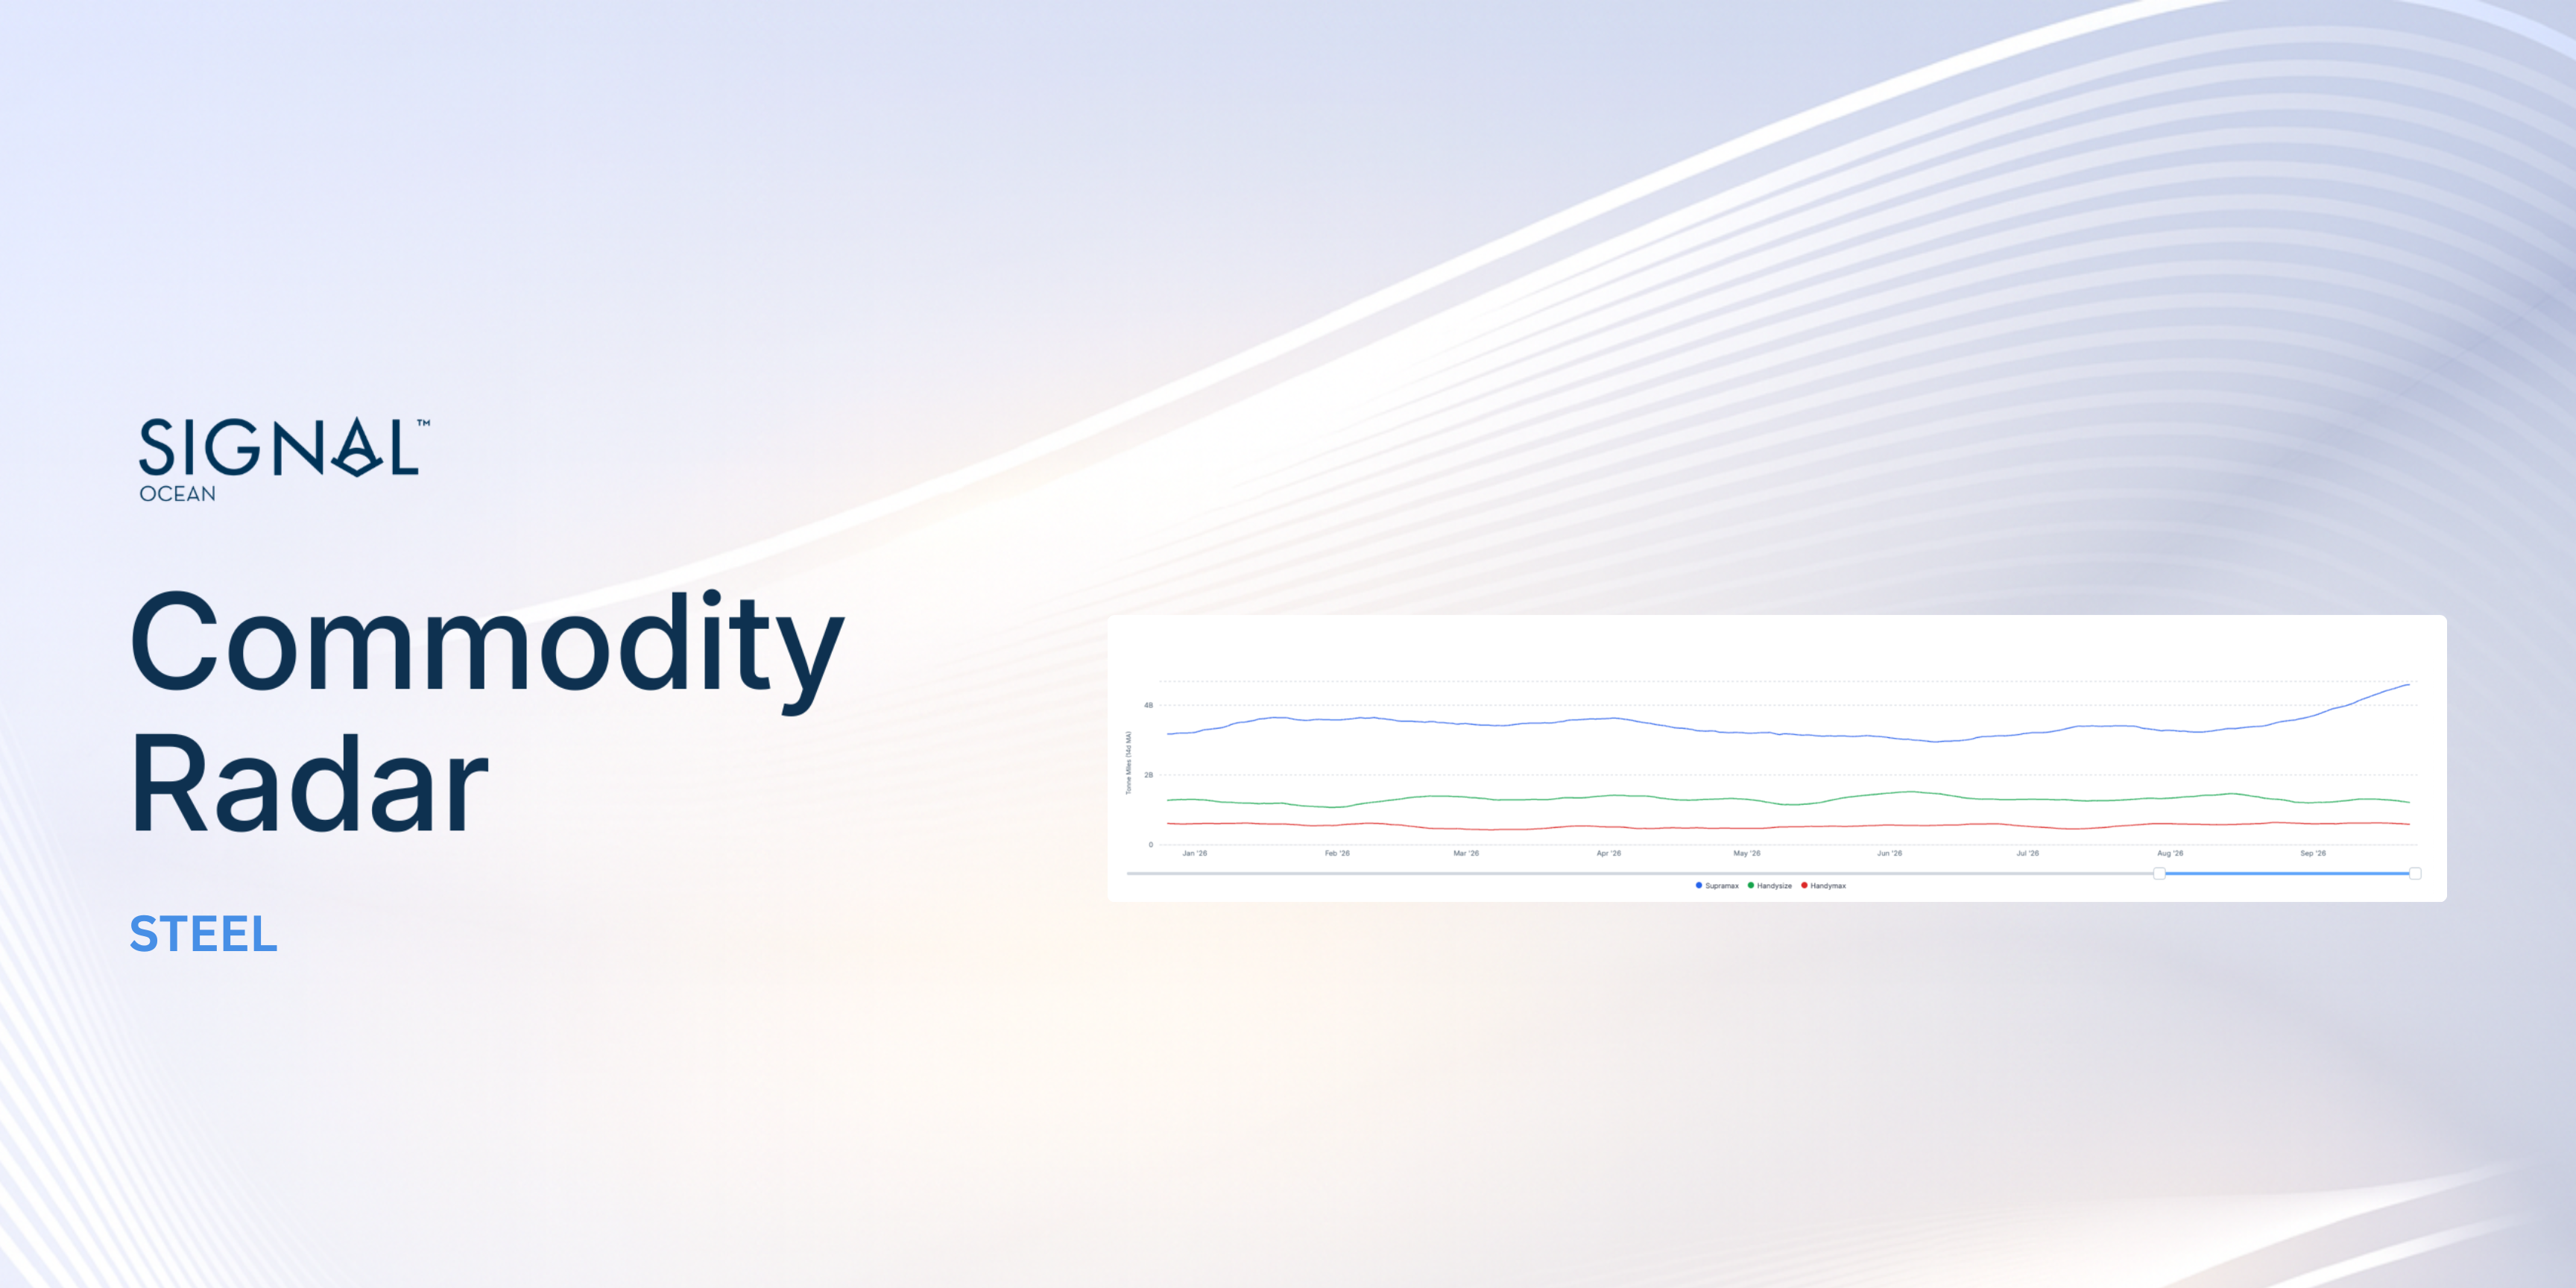
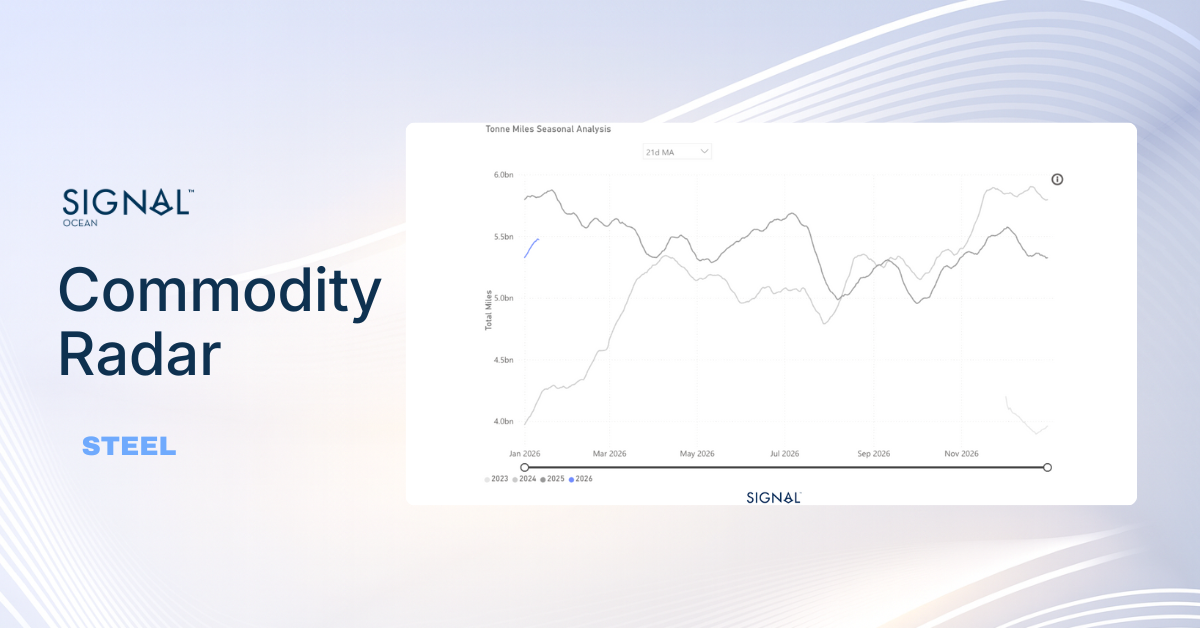
Source: Steel tonne-miles from Signal Ocean https://app.signalocean.com/dry/dynamic/timeseries_dry
Global steel flows were 22.2 Mt in July 2026, up 1% from the same period a year earlier. Higher flows from China drove much of this growth, while combined flows from elsewhere fell by nearly 8%.
India also saw a remarkable increase in steel exports in July, up 51% from the year before; however, the absolute figure is still far behind China. The exports come despite strong domestic demand for steel; Indian steel mills have been encouraged to place incremental production overseas as lower-cost steel imports to India have squeezed margins.
Source: Seaborne steel flows from Signal Ocean https://app.signalocean.com/dry/dynamic/drybulkflows
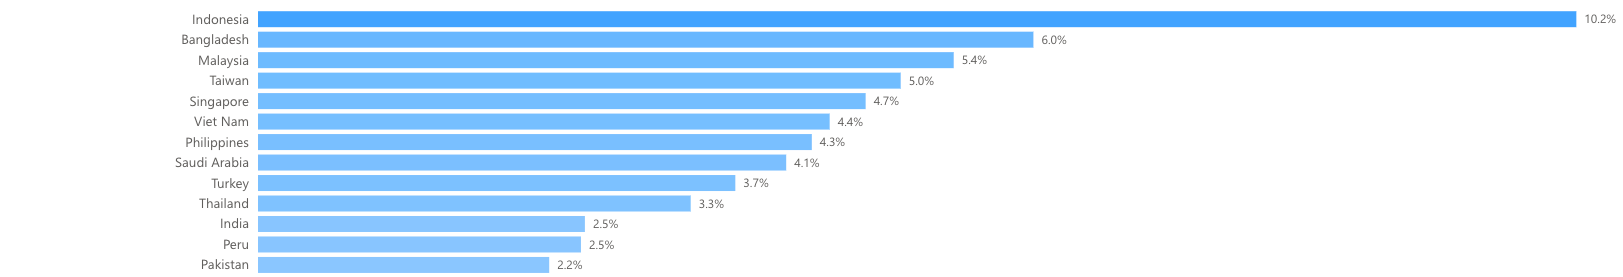
Looking ahead into the end of Q3 and into Q4, many of the market dynamics that have affected steel flows are expected to continue. The Arabian Peninsula continues to be widely locked out of the market and has seen its proportion of global steel imports fall from an average of 6.4% between 2022 and 2025 to 4.4% in 2026. This has been most impactful on China who typically sends 10% of its steel exports to the region but has seen this fall to 5.3% in 2026.
China’s steel exports will also face some new challenges going into the final quarter of 2026. The most obvious is the incoming EU crackdown on ‘Melt and Pour.’ From October 1st, the EU is enforcing strict mandates tracking the absolute origin of crude steel; this will cut off the common practice of nations buying lower-cost Chinese steel, rerolling, and selling into the EU as ‘local’ steel.
Turkey is the most likely to see steel imports fall as a result of this, as the country imports around 20% of its steel demand from China. Turkey typically then exports around 28% of its steel exports to either the Central Mediterranean or East Mediterranean.
Source: Chinese steel exports destination in 2026 from Signal Ocean https://app.signalocean.com/dry/dynamic/drybulkflows
Chinese steel exports face new and ongoing challenges in 2026 Q4
Global steel flows nudged higher in July 2026, but the headline figure masks a widening split in the market. China continued to tighten its grip, pushing more volume out even as demand from the rest of the world softened and pulled overall non-China flows down sharply. India emerged as a notable bright spot, with exports surging as domestic mills, squeezed by cheap imports undercutting their margins at home, leaned harder into overseas sales, though it remains a minor player next to China's scale.
Heading into Q4, headwinds are building for Chinese exports. The Arabian Peninsula's share of global steel imports has fallen from 6.4% to 4.4% in 2026, hitting China's regional exports hardest, down to 5.3% of its total from a typical 10%. More significantly, the EU's "Melt and Pour" origin rules take effect October 1st, closing the reroll-and-resell loophole. Turkey, which sources roughly 20% of its steel demand from China and sends about 28% of its exports to the Mediterranean, looks most exposed to the fallout.
Luke has over 8-years of experience analysing and forecasting commodity markets, with particular expertise in stainless steel raw materials and the wider metals markets.
Creating a sustainable world requires us to embark on a journey towards a zero emission future, where every step is a commitment to preserve our planet for future generations.
Albert Greenway
Environmental Scientist, Sustainability Expert
No items found.
Increased Use of Renewable Energy:
Shipping companies are embracing renewable energy sources to power onboard systems and reduce emissions during port operations. Solar panels and wind turbines are being installed on vessels to generate clean energy, reducing reliance on auxiliary engines, and cutting down emissions. Shore power facilities in ports allow ships to connect to the electrical grid, eliminating the need for onboard generators while docked.
Collaboration and Industry Partnerships:
Recognizing that addressing emissions requires collective action, shipping companies, governments, and organizations have formed partnerships and collaborations. These initiatives focus on research and development, sharing best practices, and promoting knowledge transfer. Joint projects aim to develop and deploy innovative technologies, improve infrastructure, and create a supportive regulatory framework to accelerate the industry's transition towards a greener future. The Zero Emission Shipping - Mission Innovation.
To pave the way for a greener future in shipping, the availability of alternative fuels plays a vital role in their widespread adoption. However, this availability is influenced by factors such as port infrastructure, local regulations, and government policies. As the demand for cleaner fuels in shipping rises and environmental regulations become more stringent, efforts are underway to improve the accessibility of these fuels through infrastructure development, collaborations, and investments in production facilities.
Liquefied Natural Gas (LNG) infrastructure has seen significant growth in recent years, resulting in more LNG bunkering facilities and LNG-powered vessels. Nonetheless, the availability of LNG as a marine fuel can still vary depending on the region. To ensure consistent availability worldwide, there is a need for further development of LNG supply chains and infrastructure. For biofuels, their availability hinges on production capacity and the availability of feedstock. Although biofuels are being produced and utilized in various sectors, their availability as a marine fuel remains limited. Scaling up biofuel production and establishing robust supply chains are imperative to ensure wider availability within the shipping industry.Hydrogen, as a fuel for maritime applications, is still in the early stages of infrastructure development. While some hydrogen vessels have been tested or introduced in the first quarter of last year, the infrastructure required for hydrogen production and distribution needs further advancement.
Ammonia, as a marine fuel, currently faces limitations in availability. The production, storage, and handling infrastructure for ammonia need further development to support its widespread use in the shipping industry.Methanol, on the other hand, is already a commercially available fuel and has been used as a blend with conventional fuels in some ships. However, its availability as a standalone marine fuel can still be limited in certain regions. Bureau Veritas in October 2022 published a White Paper for the Alternative Fuels Outlook. This white paper provides a comprehensive overview of alternative fuels for the shipping industry, taking into account key factors such as technological maturity, availability, safety, emissions, and regulations.
Creating a sustainable world requires us to embark on a journey towards a zero emission future, where every step is a commitment to preserve our planet for future generations.
Albert Greenway
Environmental Scientist, Sustainability Expert
Increased Use of Renewable Energy:
Shipping companies are embracing renewable energy sources to power onboard systems and reduce emissions during port operations. Solar panels and wind turbines are being installed on vessels to generate clean energy, reducing reliance on auxiliary engines, and cutting down emissions. Shore power facilities in ports allow ships to connect to the electrical grid, eliminating the need for onboard generators while docked.
Collaboration and Industry Partnerships:
Recognizing that addressing emissions requires collective action, shipping companies, governments, and organizations have formed partnerships and collaborations. These initiatives focus on research and development, sharing best practices, and promoting knowledge transfer. Joint projects aim to develop and deploy innovative technologies, improve infrastructure, and create a supportive regulatory framework to accelerate the industry's transition towards a greener future. The Zero Emission Shipping - Mission Innovation.
To pave the way for a greener future in shipping, the availability of alternative fuels plays a vital role in their widespread adoption. However, this availability is influenced by factors such as port infrastructure, local regulations, and government policies. As the demand for cleaner fuels in shipping rises and environmental regulations become more stringent, efforts are underway to improve the accessibility of these fuels through infrastructure development, collaborations, and investments in production facilities.
Liquefied Natural Gas (LNG) infrastructure has seen significant growth in recent years, resulting in more LNG bunkering facilities and LNG-powered vessels. Nonetheless, the availability of LNG as a marine fuel can still vary depending on the region. To ensure consistent availability worldwide, there is a need for further development of LNG supply chains and infrastructure. For biofuels, their availability hinges on production capacity and the availability of feedstock. Although biofuels are being produced and utilized in various sectors, their availability as a marine fuel remains limited. Scaling up biofuel production and establishing robust supply chains are imperative to ensure wider availability within the shipping industry.Hydrogen, as a fuel for maritime applications, is still in the early stages of infrastructure development. While some hydrogen vessels have been tested or introduced in the first quarter of last year, the infrastructure required for hydrogen production and distribution needs further advancement.
Ammonia, as a marine fuel, currently faces limitations in availability. The production, storage, and handling infrastructure for ammonia need further development to support its widespread use in the shipping industry.Methanol, on the other hand, is already a commercially available fuel and has been used as a blend with conventional fuels in some ships. However, its availability as a standalone marine fuel can still be limited in certain regions. Bureau Veritas in October 2022 published a White Paper for the Alternative Fuels Outlook. This white paper provides a comprehensive overview of alternative fuels for the shipping industry, taking into account key factors such as technological maturity, availability, safety, emissions, and regulations.