Subscribe for our latest news, straight to your inbox:
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Share this post
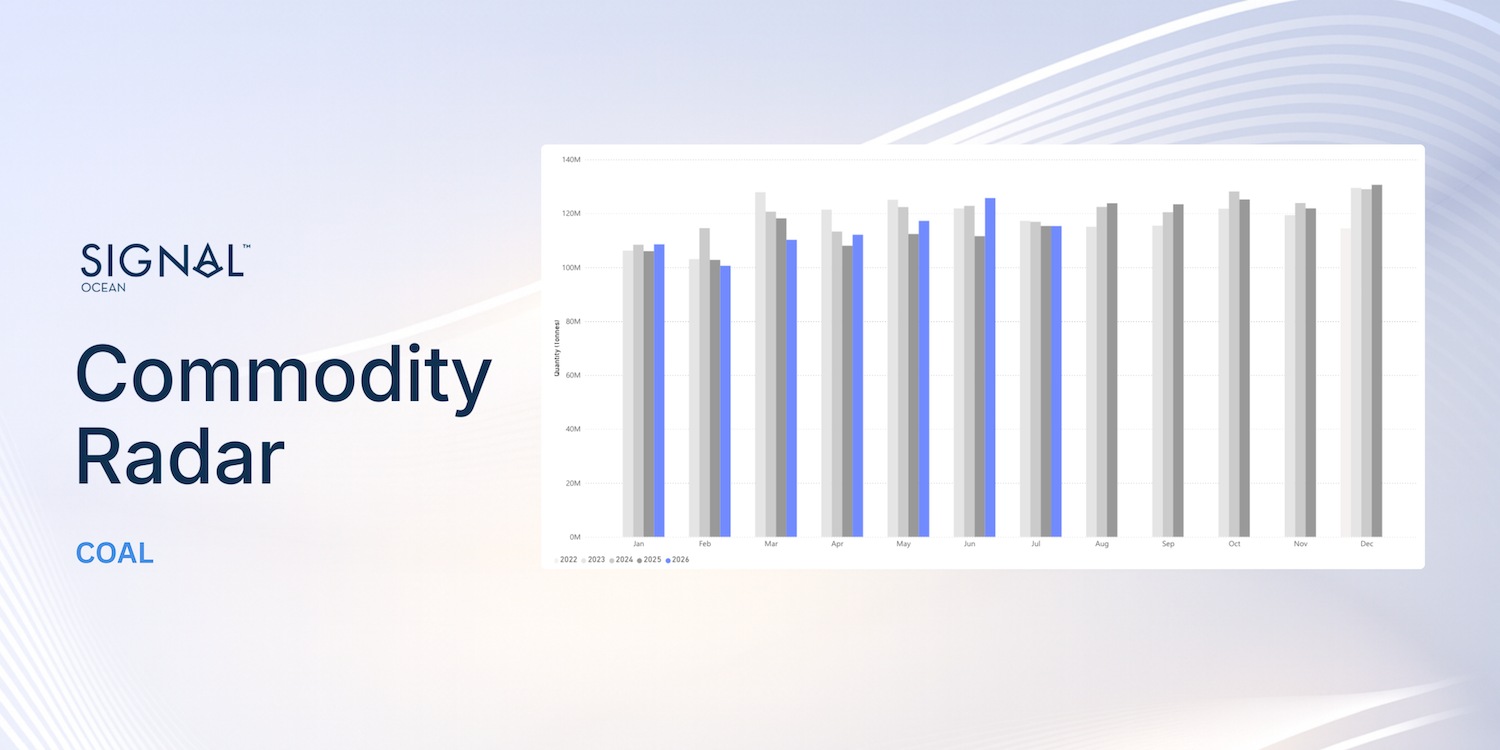
COMMODITY RADAR | Spotlight: COAL
Thermal weakness drags global coal flows lower
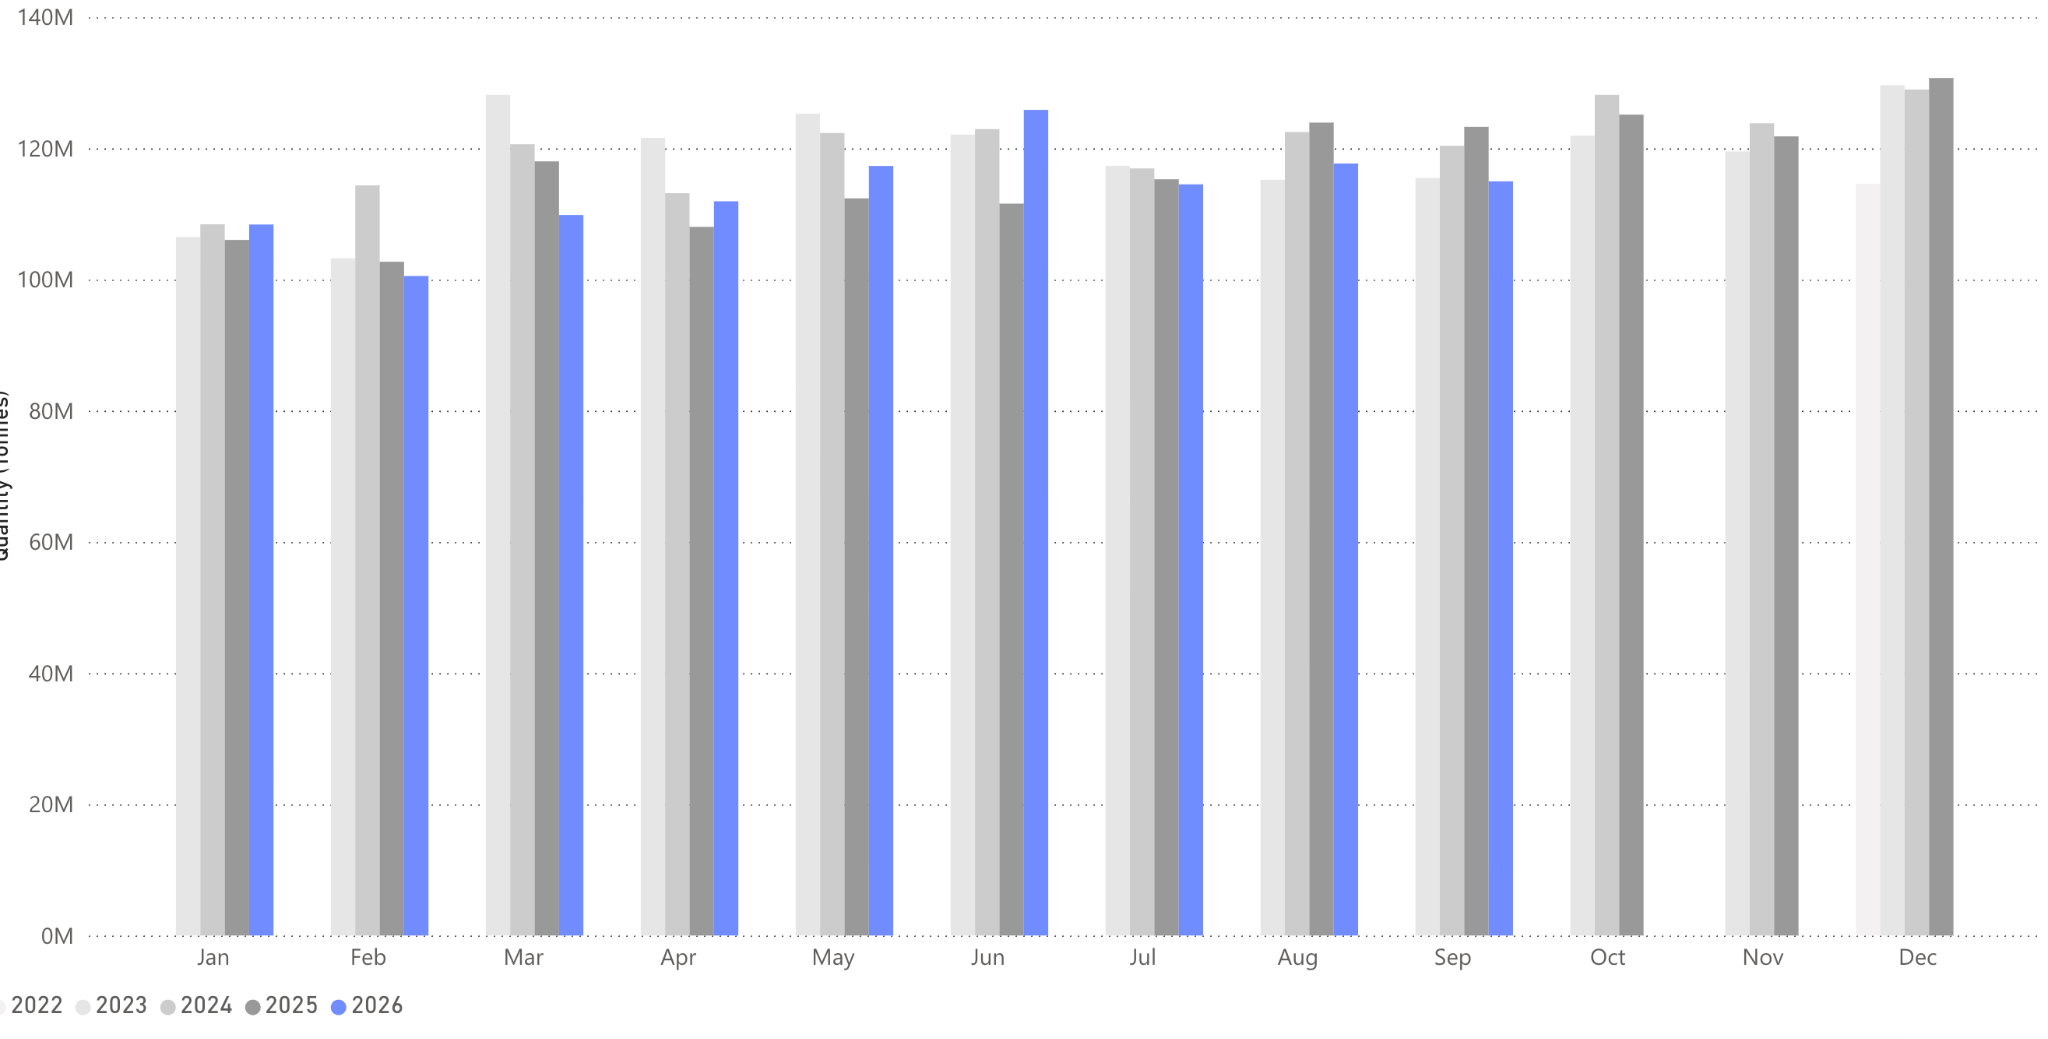
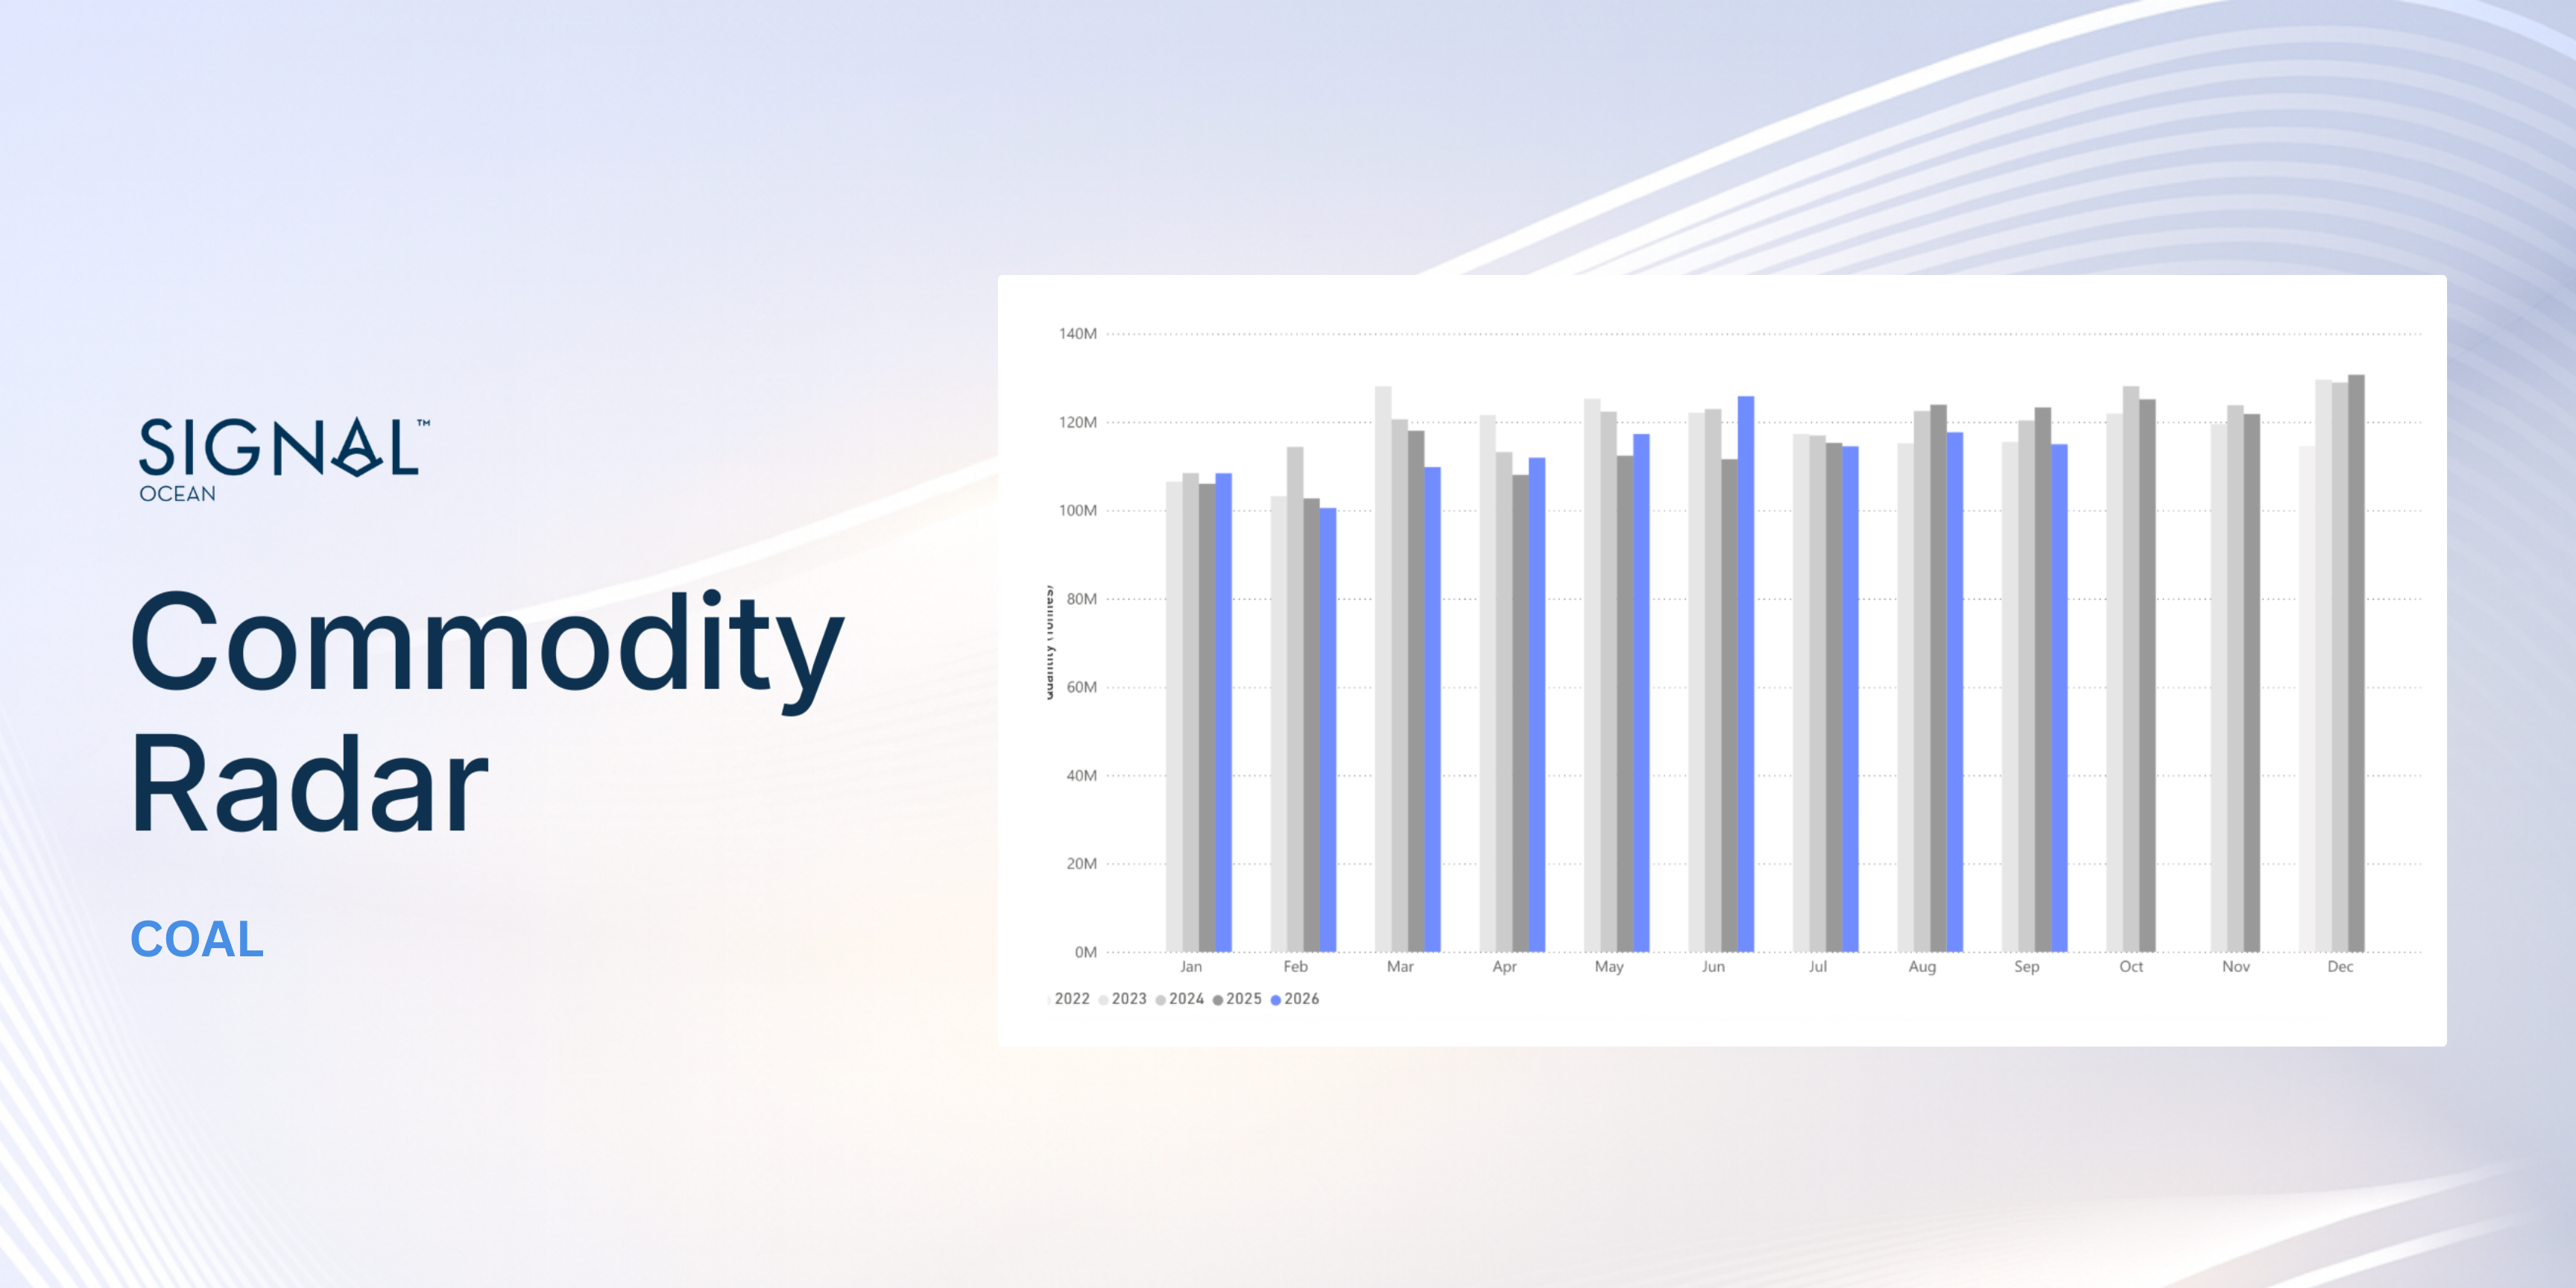
Global seaborne coal flows fell 6.7% year on year in September 2026 to 115 Mt. Thermal coal drove the decline, and a rise in met coal flows was not enough to offset it. Behind the headline, regional demand diverged sharply. India and China cut arrivals as domestic production and renewable output grew, while Japan increased imports as elevated LNG prices pushed utilities back towards coal. This report examines what drove September's weakness, how trade patterns are shifting across the main importers, and why October points to a firmer restocking phase.
Global seaborne coal flows fell sharply by over 6.7% in September 2026.
Driven by a 12.7% decline in seaborne thermal coal flows.
Global seaborne met coal flows jumped 13.5% in September 2026.
Coal arrivals into India during September 2026 fell by 13.9%
Coal arrivals into Japan during September 2026 jumped by 12.9%
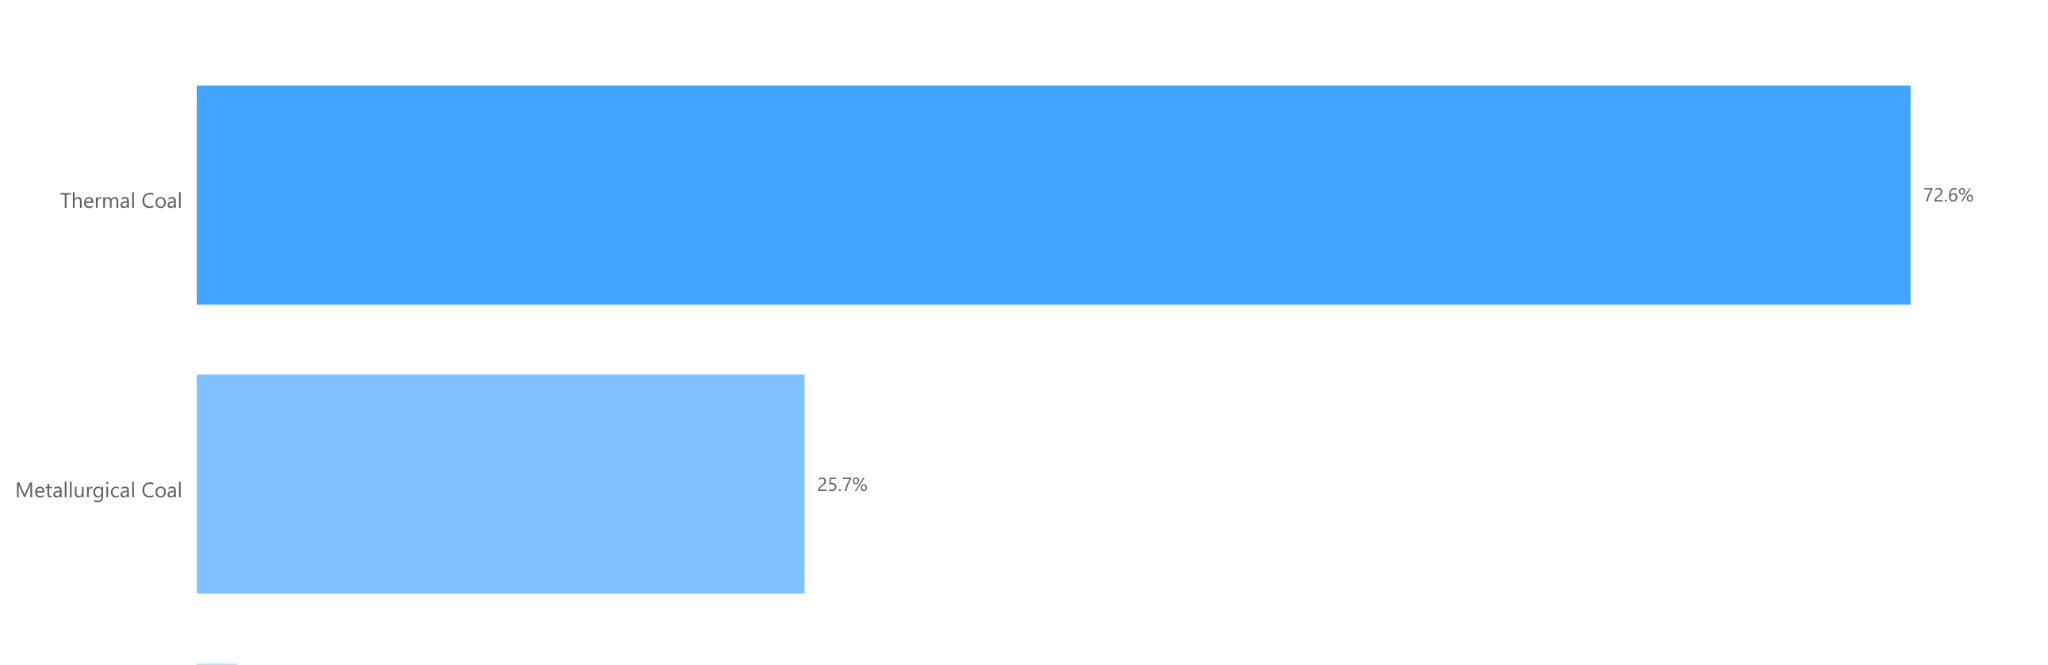
Global seaborne coal flows were 115 Mt in September 2026, down 6.7% y/y, driven by a large 14% decline in seaborne thermal coal flows. This contrasts with a 13.5% rise in seaborne met coal flows, but because 72.8% of all coal flows in September were thermal coal, the met coal increase could not offset the overall decline.
Coal arrivals into India and China fell sharply, by 14.6% and 8.0%, respectively. These drops were driven by both countries increasing domestic coal production, and both seeing improved energy production through ‘green energy’ initiatives.
The opposite was true of Japan, which saw coal arrivals increase by 12.9%. The rising imports are a result of a switch to coal for power generation as LNG prices remain severely elevated. Japan relies heavily on the Arabian Gulf for its energy commodities, but the shift to coal has enabled a much more insulated energy supply chain.
Source: Met coal flows vs thermal coal flows in September 2026 from Signal Ocean https://app.signalocean.com/dry/dynamic/drybulkflows
Looking ahead, Signal Ocean is already tracking strong coal loadings due to arrive in October, particularly into India. A drier end to the monsoon season has sharply cut hydroelectric output, forcing utilities to burn more coal. October is therefore expected to mark the start of a strong restocking period. However, because renewable generation has grown, stockpiles are likely to be rebuilt to lower levels than in previous years.
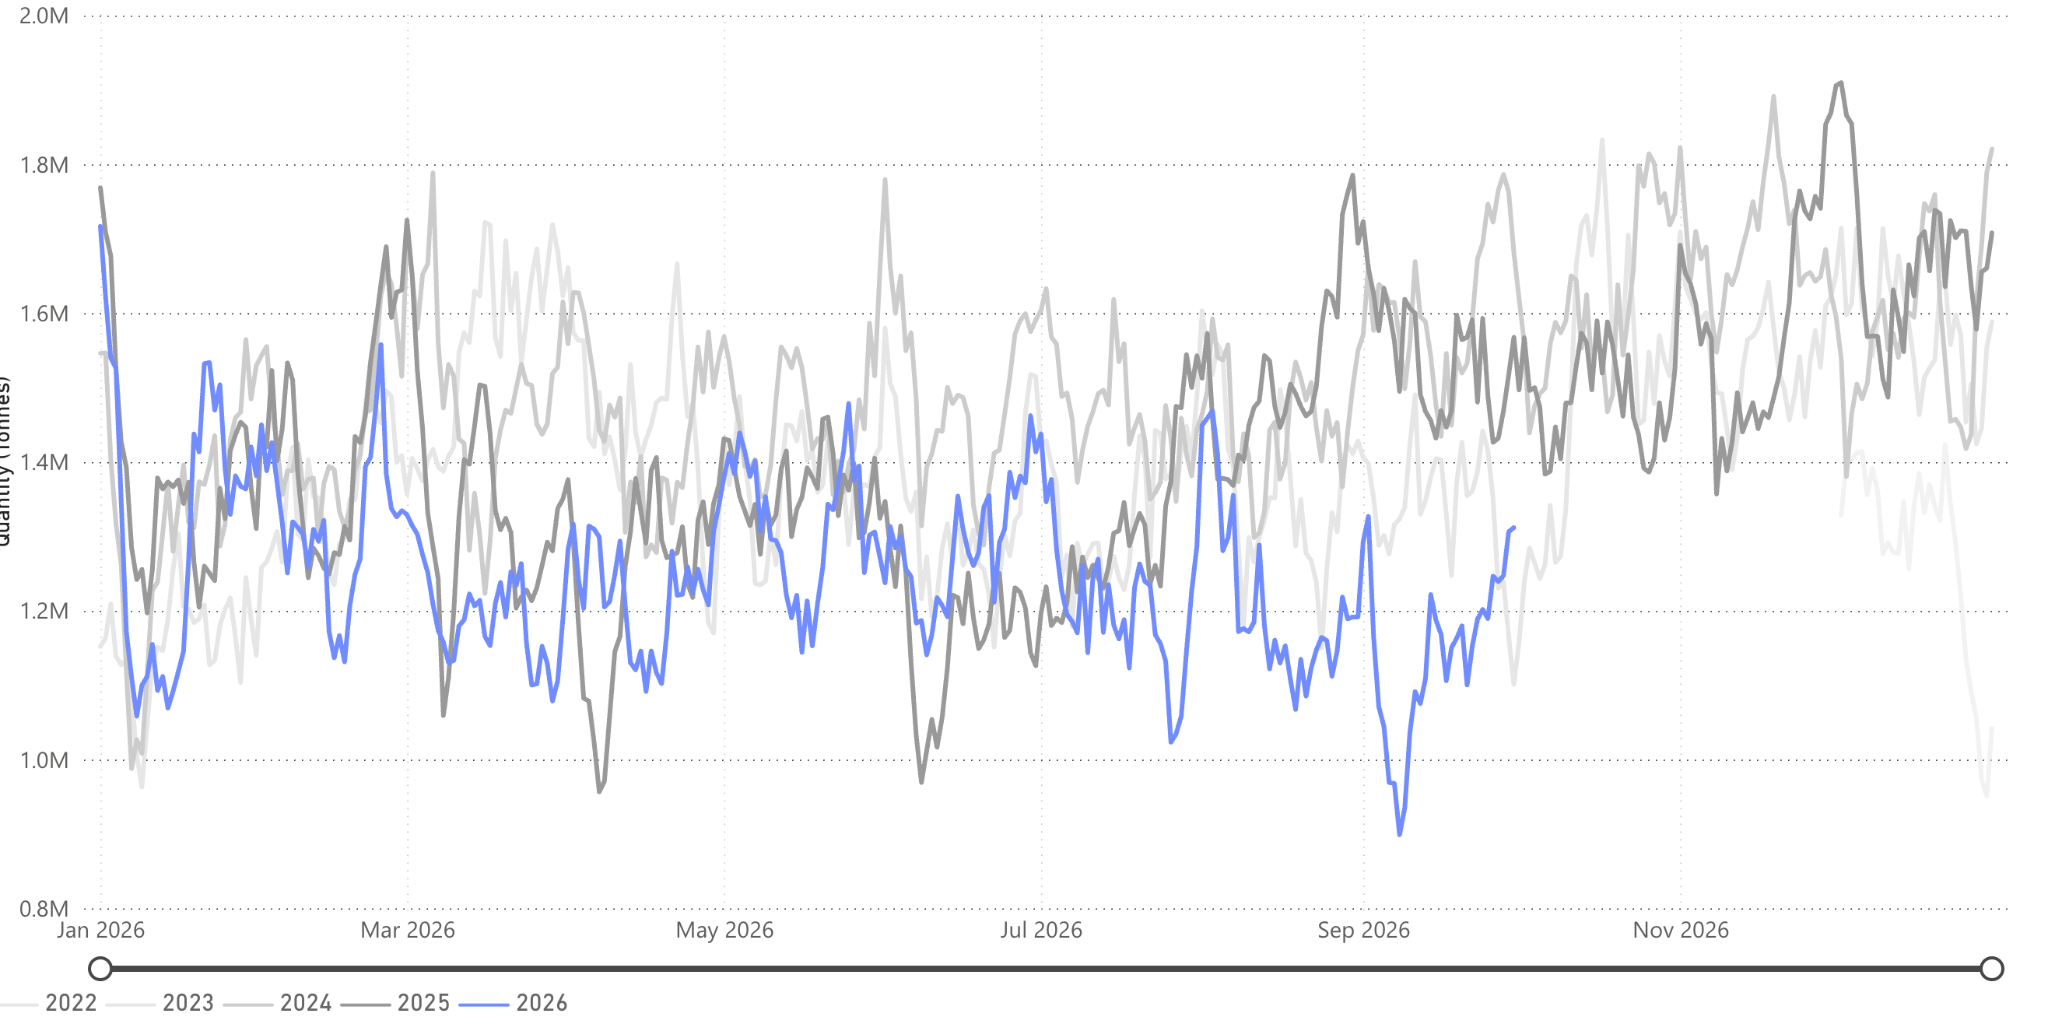
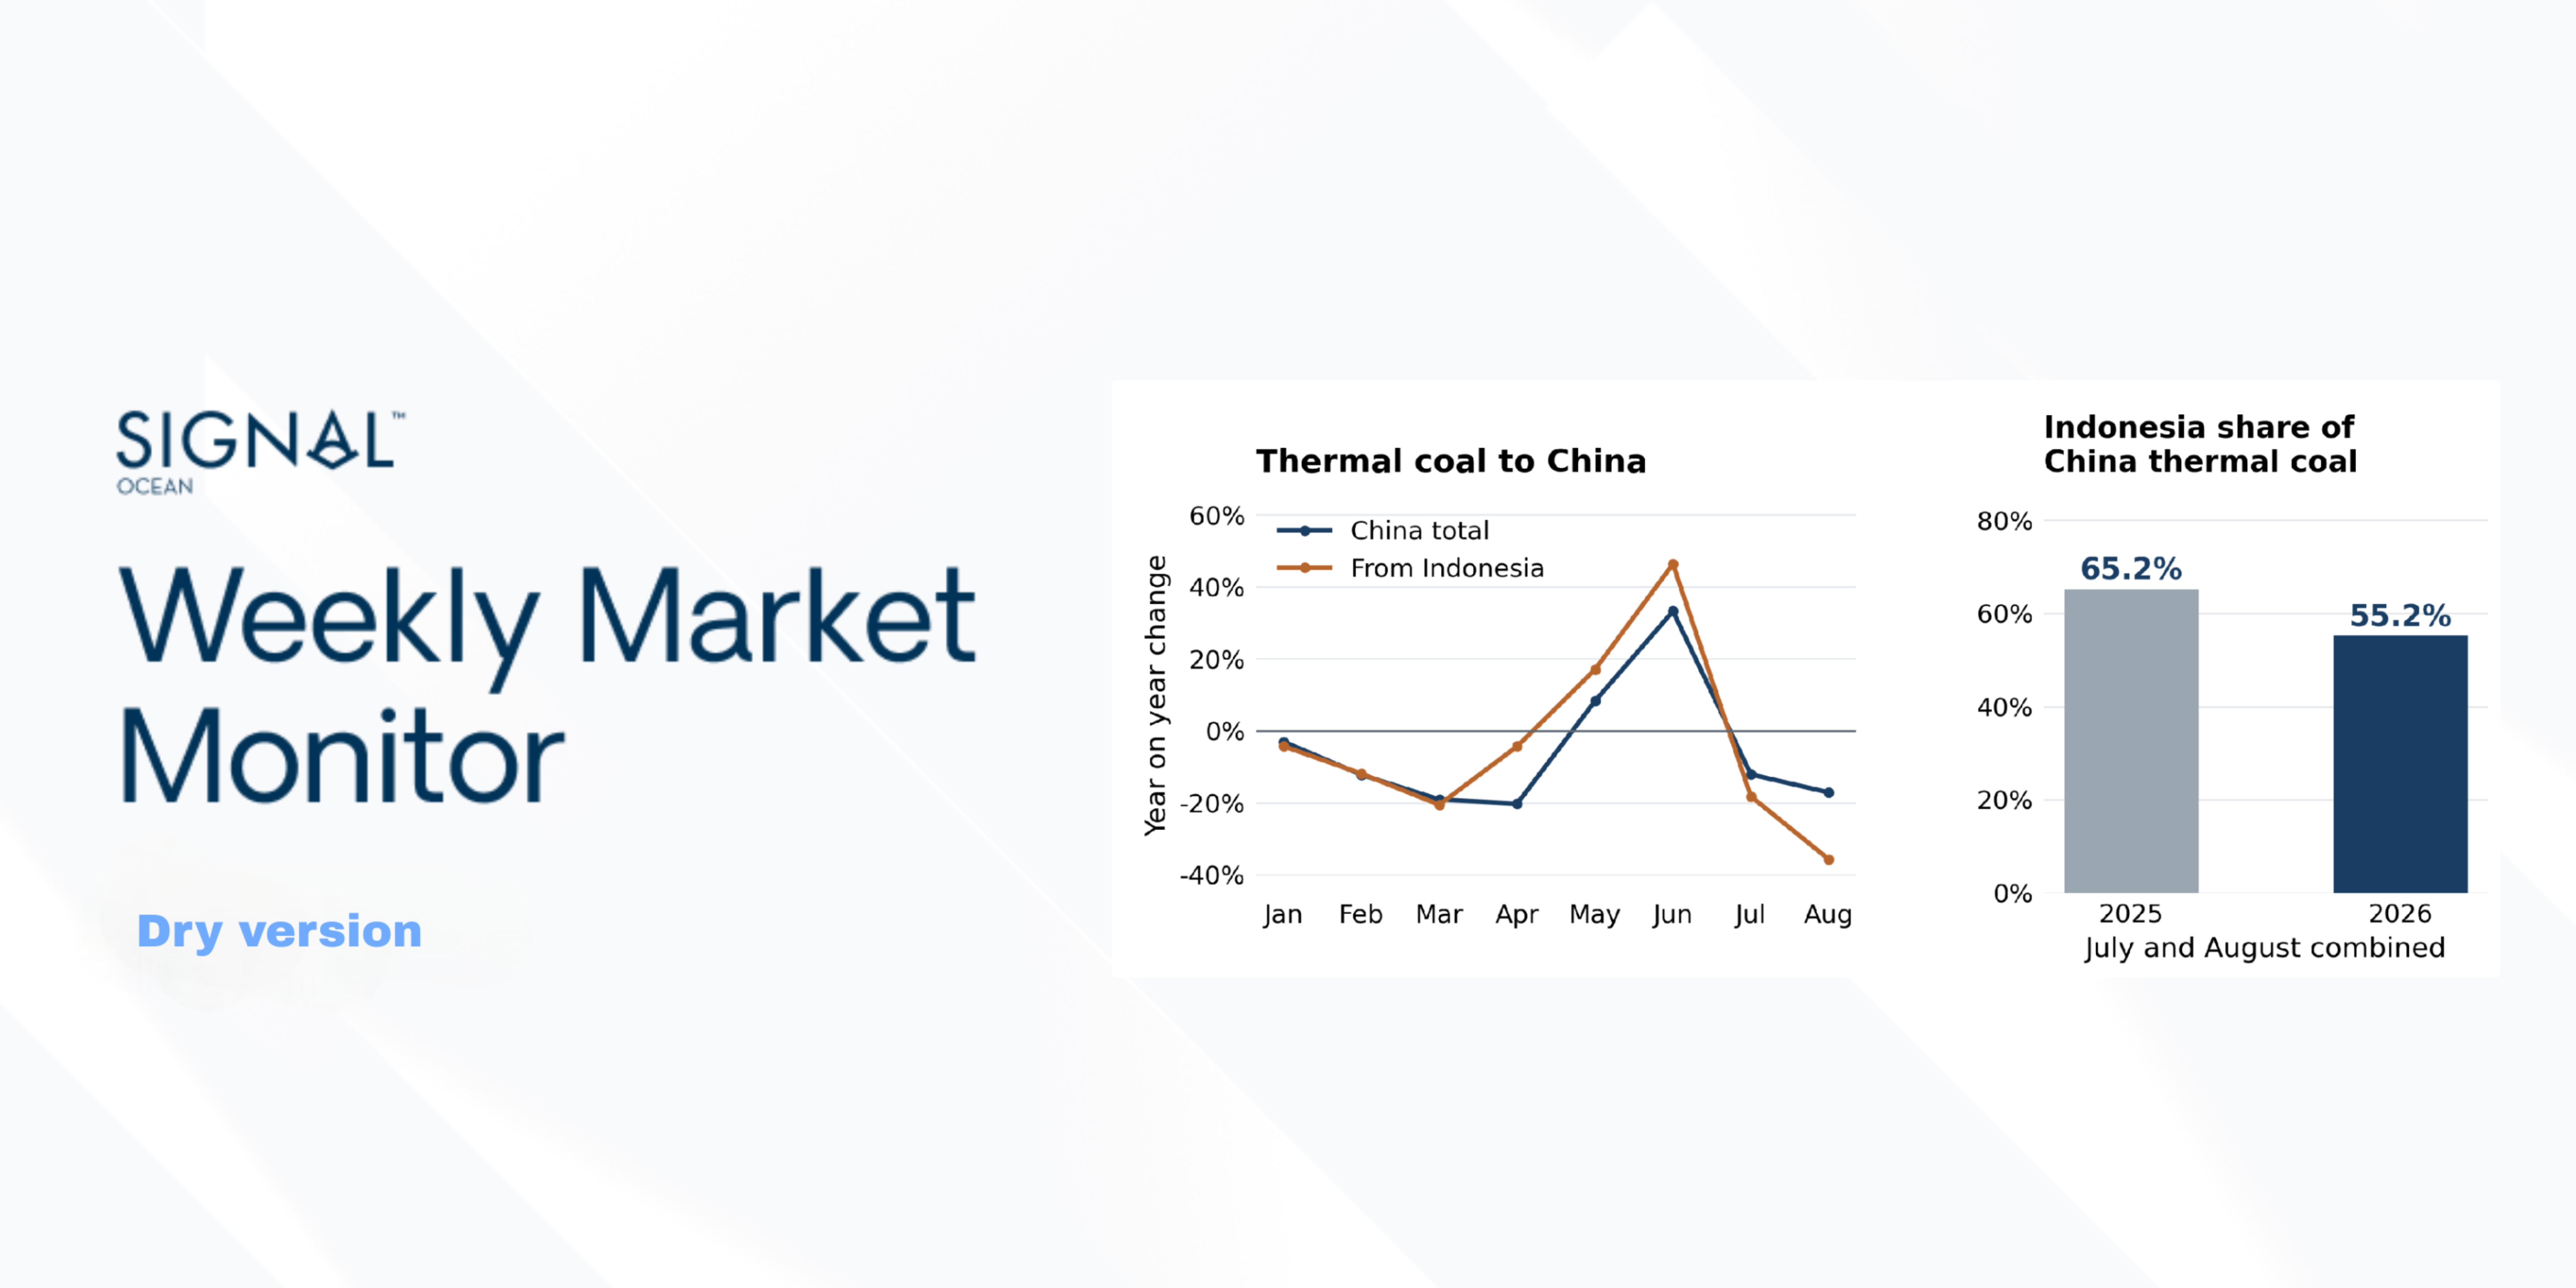
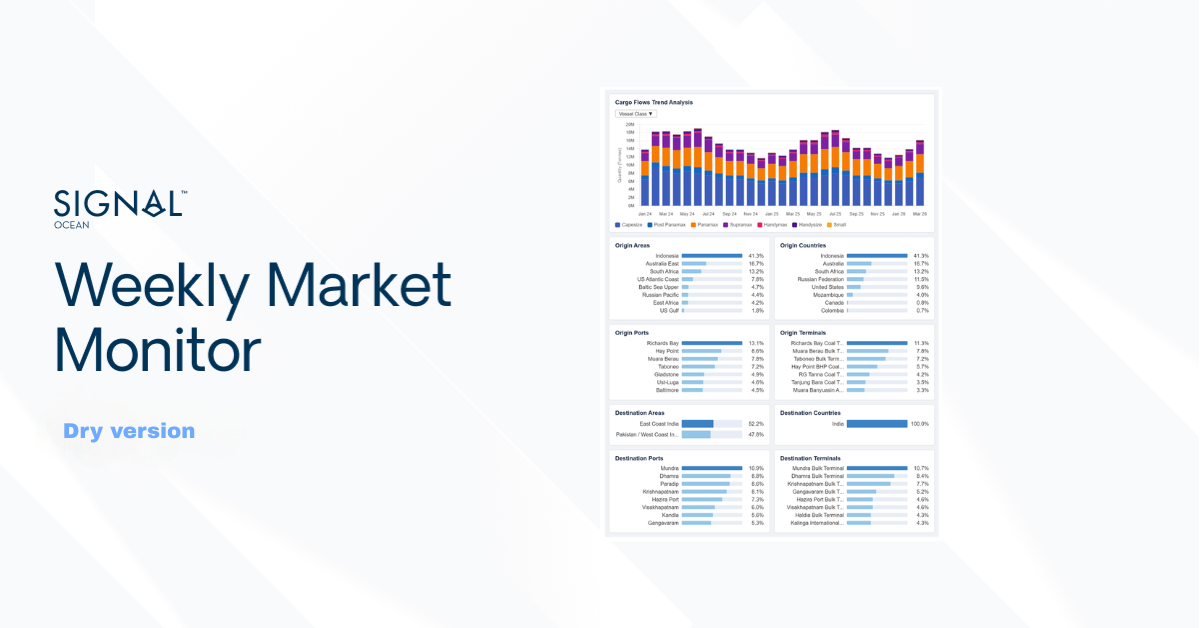
In China, domestic coal prices have risen for 11 straight weeks, so buyers are turning to cheaper seaborne coal. Indonesian supply is struggling to meet demand, and Australian cargoes look best placed to fill the gap. Mongolian coal, which arrives overland rather than by sea, has also risen notably in 2026.
Source: Indonesia coal flows from Signal Ocean https://app.signalocean.com/dry/dynamic/drybulkflows
September is a dip, not the start of a trend
September's 6.8% fall in global seaborne coal flows, to 115 Mt, was a thermal story. Met coal rose 13.5%, but thermal made up 72.8% of volumes and set the direction. India and China pulled back as domestic output and renewable generation grew, while Japan bought more coal as elevated LNG prices pushed its power sector towards coal. The picture now looks set to turn. A dry end to the monsoon has cut Indian hydropower, and loadings due in October already point to stronger arrivals. In China, domestic prices have risen for 11 straight weeks, which favours cheaper seaborne cargoes, with Australia best placed to cover Indonesia's shortfall. Mongolian volumes will keep competing for market share, but overland. Expect October to mark the start of a firmer restocking phase, though stockpiles will likely be rebuilt to lower levels than in previous years.
Luke has over 8-years of experience analysing and forecasting commodity markets, with particular expertise in stainless steel raw materials and the wider metals markets.
Creating a sustainable world requires us to embark on a journey towards a zero emission future, where every step is a commitment to preserve our planet for future generations.
Albert Greenway
Environmental Scientist, Sustainability Expert
No items found.
Increased Use of Renewable Energy:
Shipping companies are embracing renewable energy sources to power onboard systems and reduce emissions during port operations. Solar panels and wind turbines are being installed on vessels to generate clean energy, reducing reliance on auxiliary engines, and cutting down emissions. Shore power facilities in ports allow ships to connect to the electrical grid, eliminating the need for onboard generators while docked.
Collaboration and Industry Partnerships:
Recognizing that addressing emissions requires collective action, shipping companies, governments, and organizations have formed partnerships and collaborations. These initiatives focus on research and development, sharing best practices, and promoting knowledge transfer. Joint projects aim to develop and deploy innovative technologies, improve infrastructure, and create a supportive regulatory framework to accelerate the industry's transition towards a greener future. The Zero Emission Shipping - Mission Innovation.
To pave the way for a greener future in shipping, the availability of alternative fuels plays a vital role in their widespread adoption. However, this availability is influenced by factors such as port infrastructure, local regulations, and government policies. As the demand for cleaner fuels in shipping rises and environmental regulations become more stringent, efforts are underway to improve the accessibility of these fuels through infrastructure development, collaborations, and investments in production facilities.
Liquefied Natural Gas (LNG) infrastructure has seen significant growth in recent years, resulting in more LNG bunkering facilities and LNG-powered vessels. Nonetheless, the availability of LNG as a marine fuel can still vary depending on the region. To ensure consistent availability worldwide, there is a need for further development of LNG supply chains and infrastructure. For biofuels, their availability hinges on production capacity and the availability of feedstock. Although biofuels are being produced and utilized in various sectors, their availability as a marine fuel remains limited. Scaling up biofuel production and establishing robust supply chains are imperative to ensure wider availability within the shipping industry.Hydrogen, as a fuel for maritime applications, is still in the early stages of infrastructure development. While some hydrogen vessels have been tested or introduced in the first quarter of last year, the infrastructure required for hydrogen production and distribution needs further advancement.
Ammonia, as a marine fuel, currently faces limitations in availability. The production, storage, and handling infrastructure for ammonia need further development to support its widespread use in the shipping industry.Methanol, on the other hand, is already a commercially available fuel and has been used as a blend with conventional fuels in some ships. However, its availability as a standalone marine fuel can still be limited in certain regions. Bureau Veritas in October 2022 published a White Paper for the Alternative Fuels Outlook. This white paper provides a comprehensive overview of alternative fuels for the shipping industry, taking into account key factors such as technological maturity, availability, safety, emissions, and regulations.
Creating a sustainable world requires us to embark on a journey towards a zero emission future, where every step is a commitment to preserve our planet for future generations.
Albert Greenway
Environmental Scientist, Sustainability Expert
Increased Use of Renewable Energy:
Shipping companies are embracing renewable energy sources to power onboard systems and reduce emissions during port operations. Solar panels and wind turbines are being installed on vessels to generate clean energy, reducing reliance on auxiliary engines, and cutting down emissions. Shore power facilities in ports allow ships to connect to the electrical grid, eliminating the need for onboard generators while docked.
Collaboration and Industry Partnerships:
Recognizing that addressing emissions requires collective action, shipping companies, governments, and organizations have formed partnerships and collaborations. These initiatives focus on research and development, sharing best practices, and promoting knowledge transfer. Joint projects aim to develop and deploy innovative technologies, improve infrastructure, and create a supportive regulatory framework to accelerate the industry's transition towards a greener future. The Zero Emission Shipping - Mission Innovation.
To pave the way for a greener future in shipping, the availability of alternative fuels plays a vital role in their widespread adoption. However, this availability is influenced by factors such as port infrastructure, local regulations, and government policies. As the demand for cleaner fuels in shipping rises and environmental regulations become more stringent, efforts are underway to improve the accessibility of these fuels through infrastructure development, collaborations, and investments in production facilities.
Liquefied Natural Gas (LNG) infrastructure has seen significant growth in recent years, resulting in more LNG bunkering facilities and LNG-powered vessels. Nonetheless, the availability of LNG as a marine fuel can still vary depending on the region. To ensure consistent availability worldwide, there is a need for further development of LNG supply chains and infrastructure. For biofuels, their availability hinges on production capacity and the availability of feedstock. Although biofuels are being produced and utilized in various sectors, their availability as a marine fuel remains limited. Scaling up biofuel production and establishing robust supply chains are imperative to ensure wider availability within the shipping industry.Hydrogen, as a fuel for maritime applications, is still in the early stages of infrastructure development. While some hydrogen vessels have been tested or introduced in the first quarter of last year, the infrastructure required for hydrogen production and distribution needs further advancement.
Ammonia, as a marine fuel, currently faces limitations in availability. The production, storage, and handling infrastructure for ammonia need further development to support its widespread use in the shipping industry.Methanol, on the other hand, is already a commercially available fuel and has been used as a blend with conventional fuels in some ships. However, its availability as a standalone marine fuel can still be limited in certain regions. Bureau Veritas in October 2022 published a White Paper for the Alternative Fuels Outlook. This white paper provides a comprehensive overview of alternative fuels for the shipping industry, taking into account key factors such as technological maturity, availability, safety, emissions, and regulations.