Subscribe for our latest news, straight to your inbox:
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Share this post
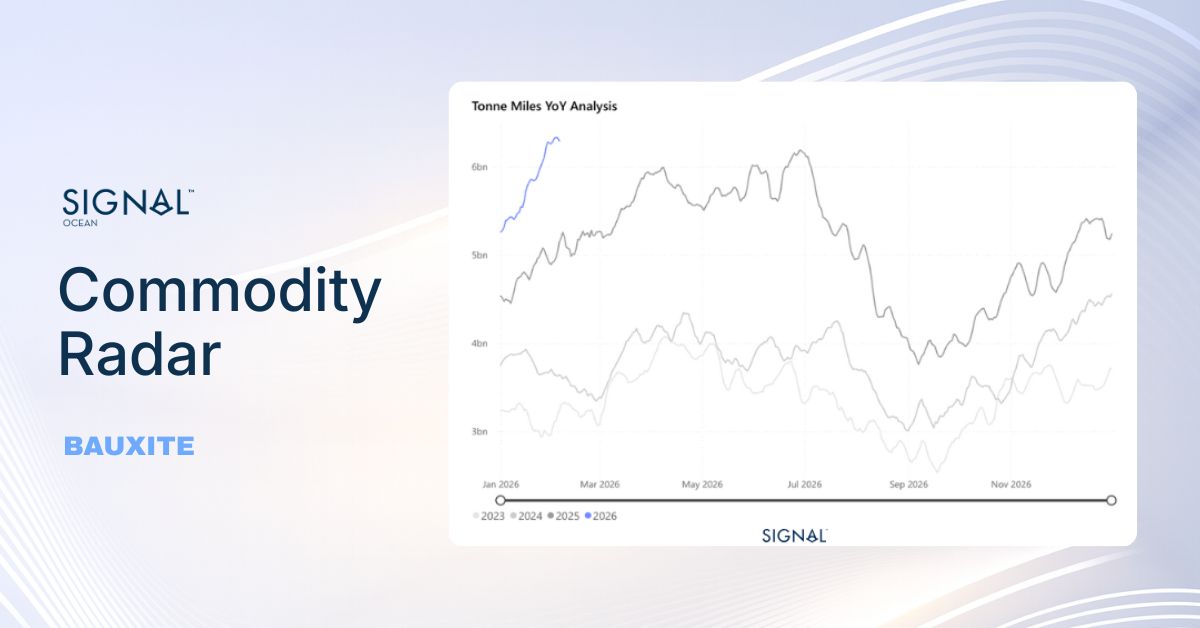
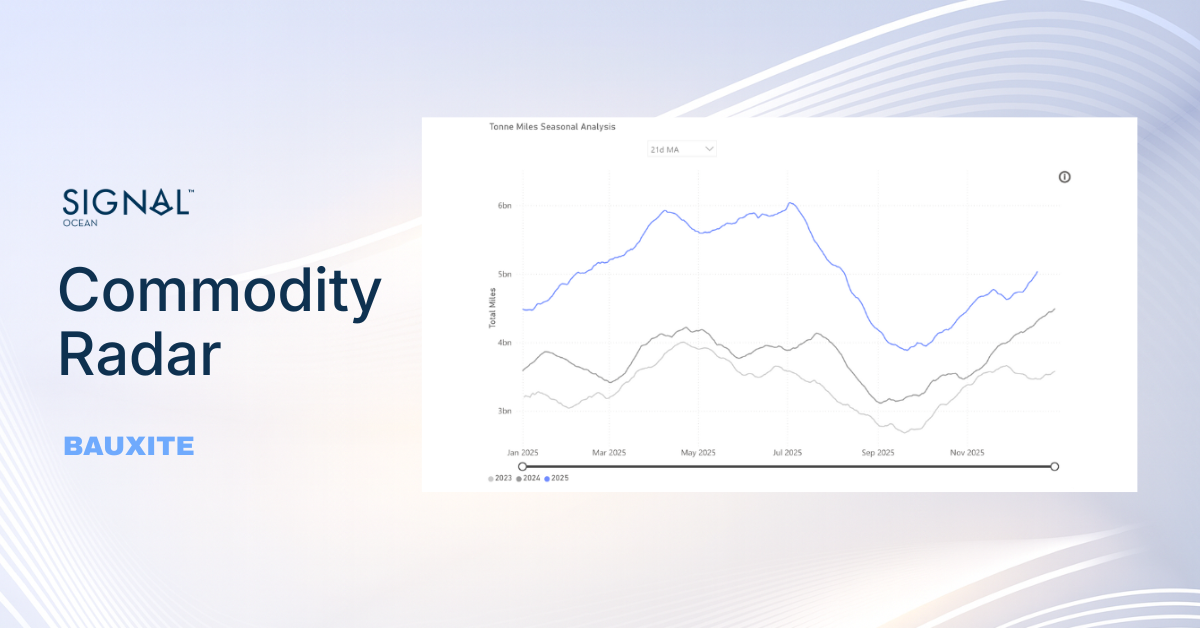
COMMODITY RADAR | Spotlight: BAUXITE
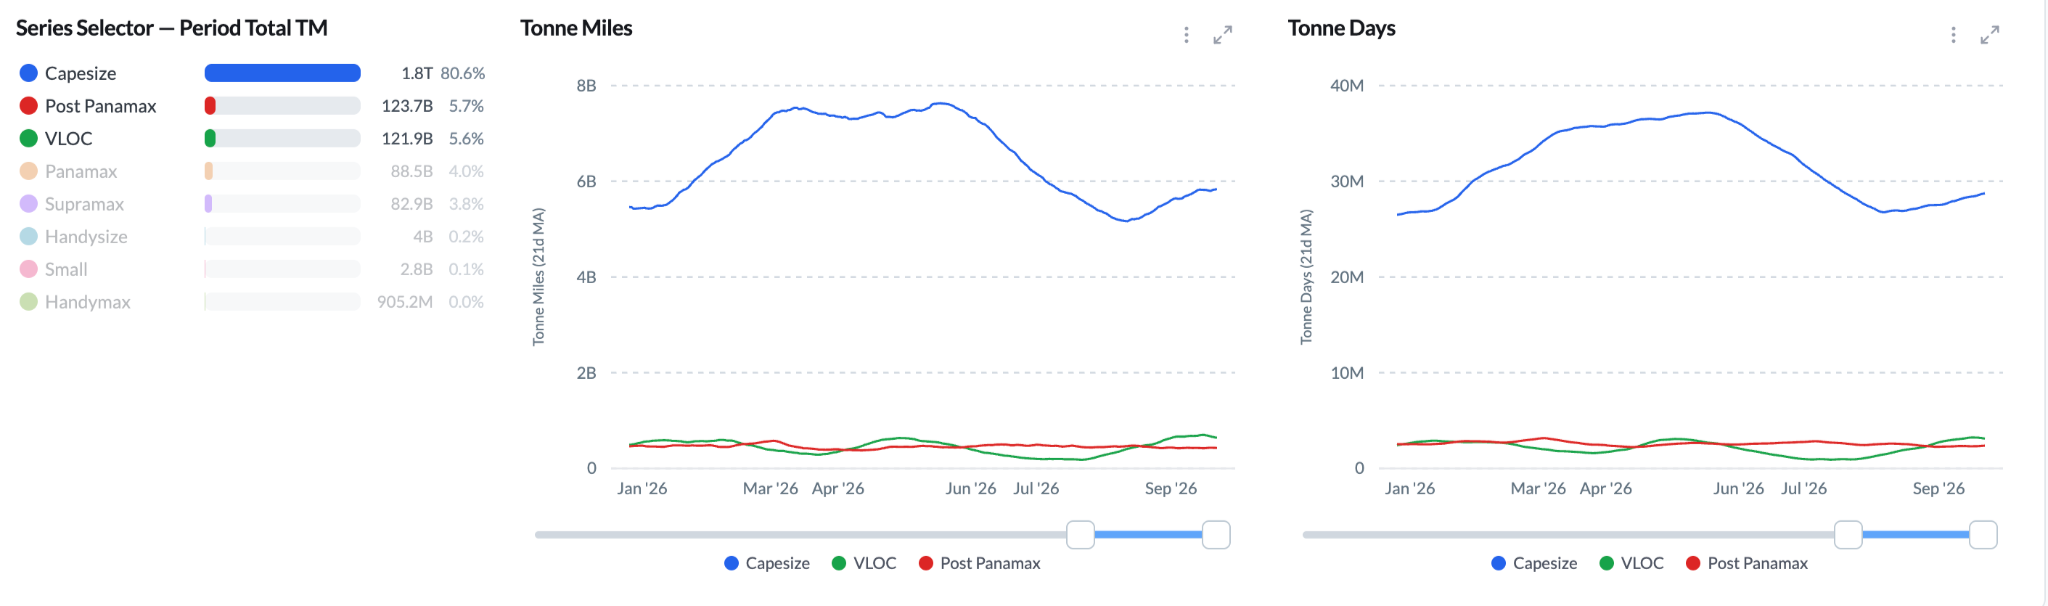
The final quarter of 2026 is expected to see softer bauxite flows
Chinese front-loading is expected to have run its course, pointing to softer bauxite flows in 2026 Q4.
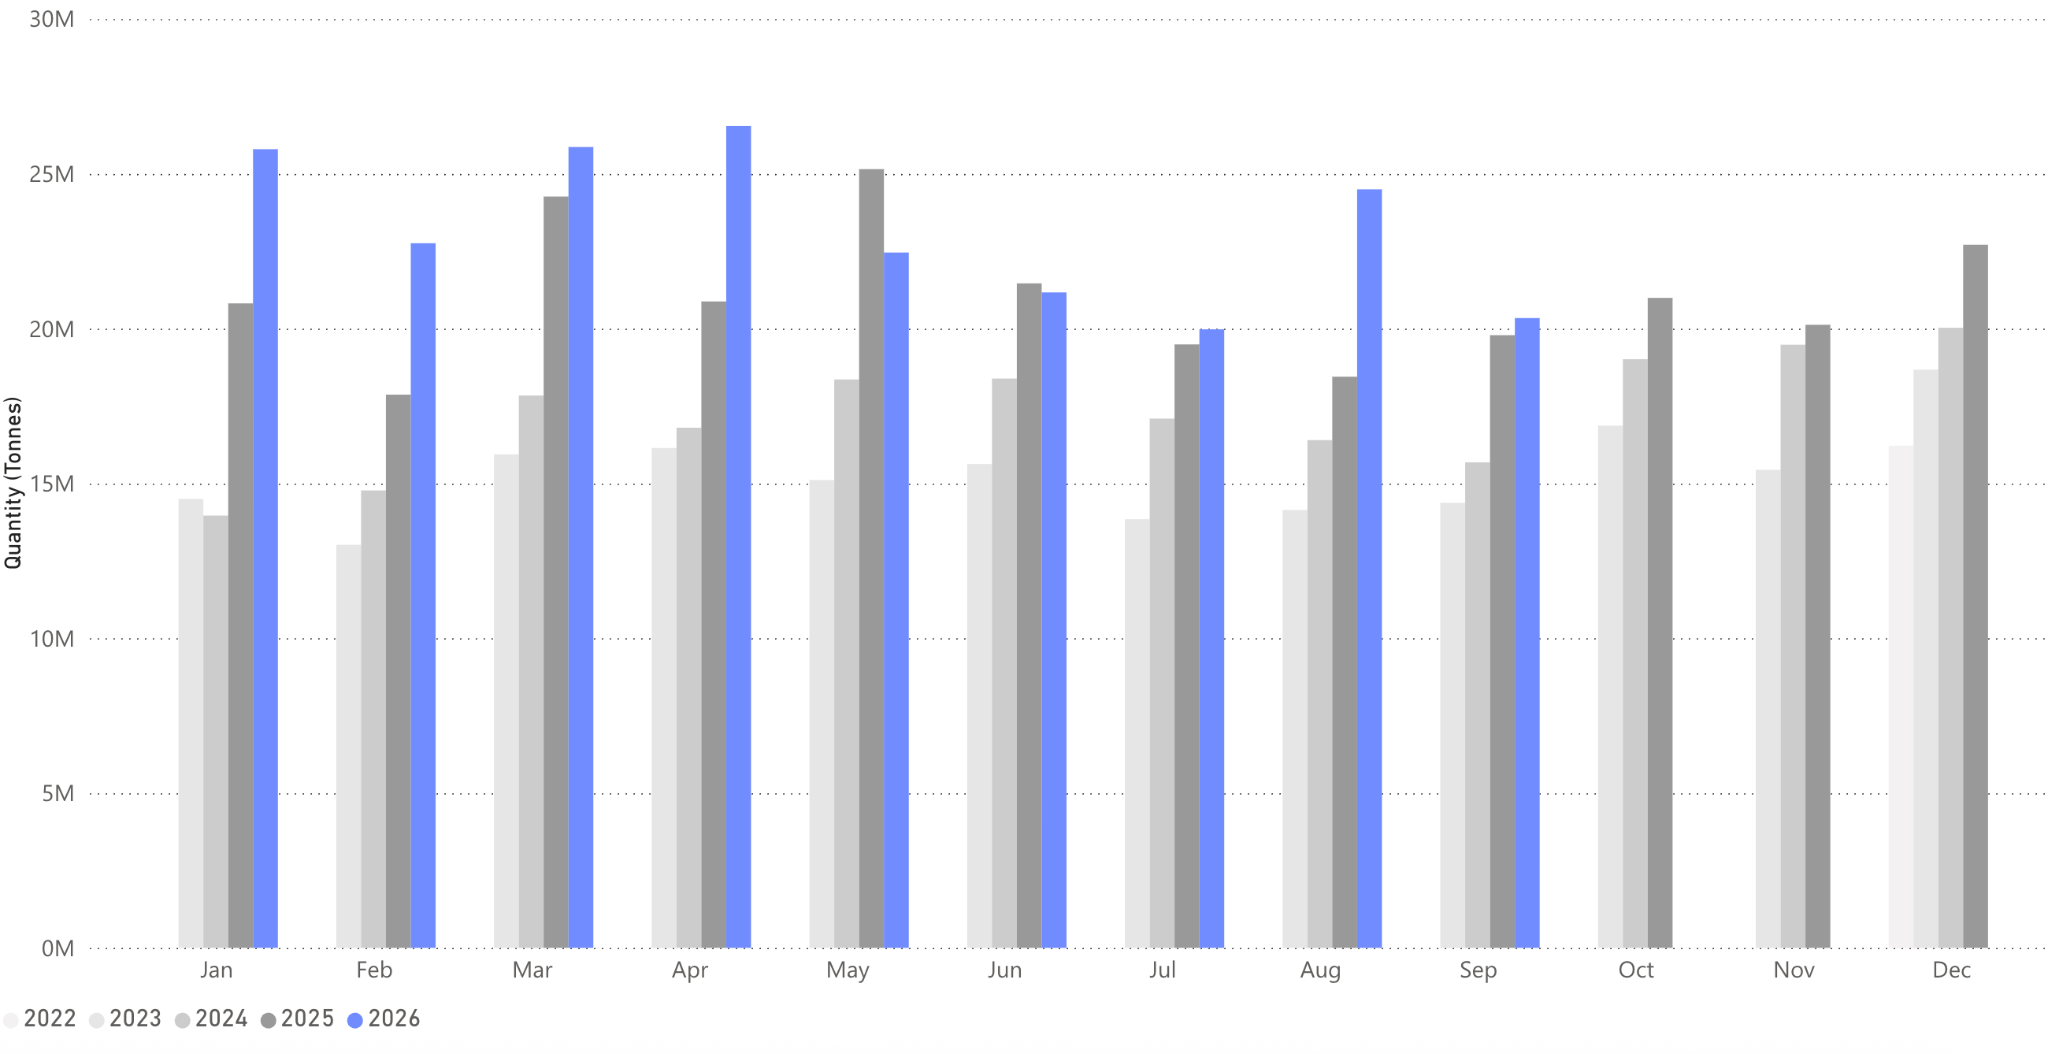
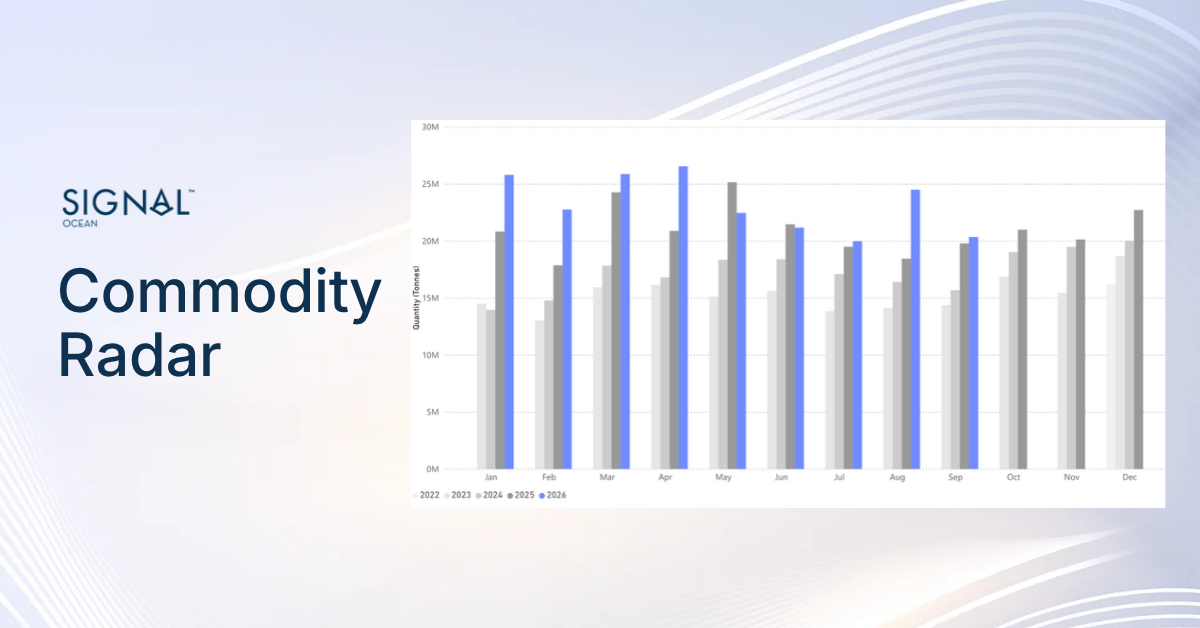
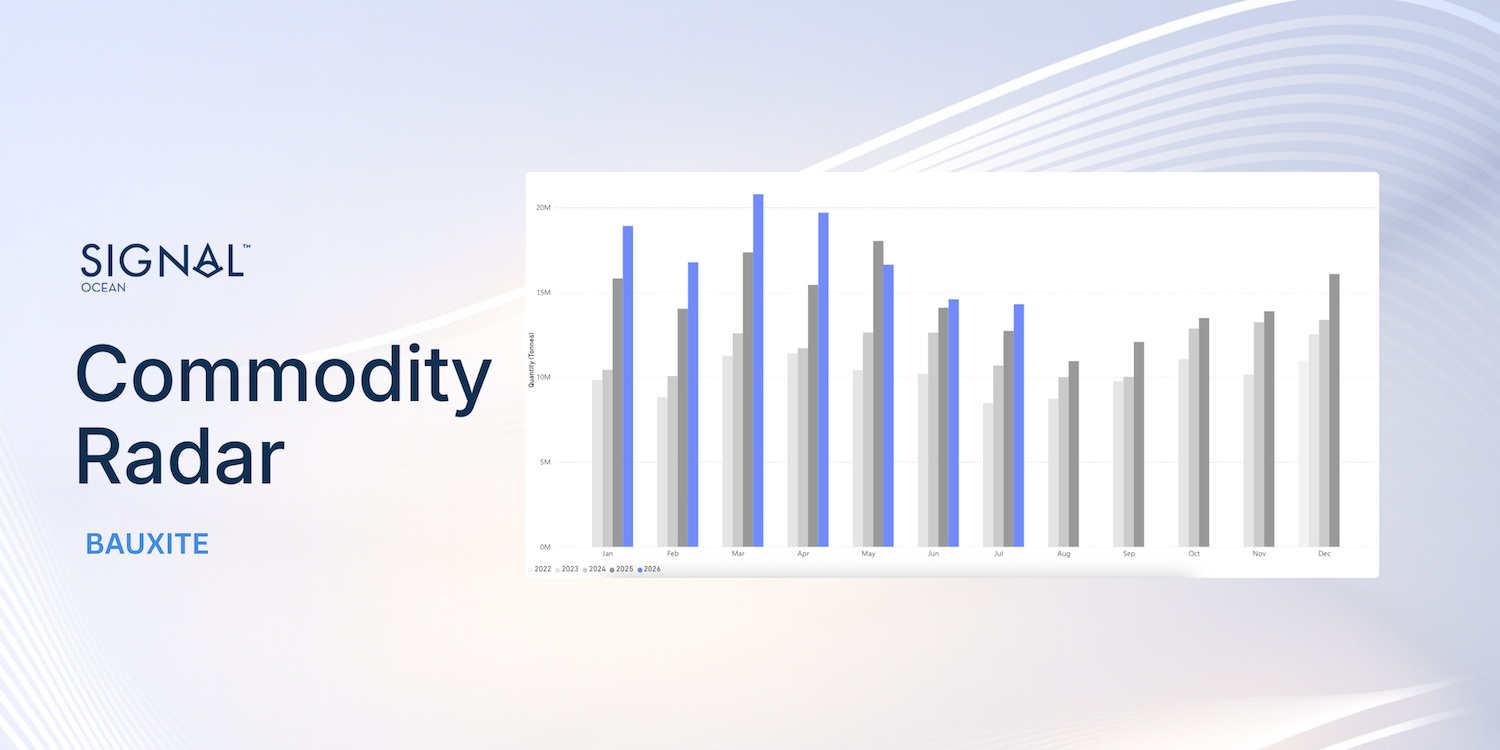
Global bauxite flows increased by 2.8% y/y in September.
Flows arriving in China increased by 21.2% y/y in September
Flows arriving in the UAE fell by over 60.0% in September.
Bauxite arriving in India declined by 37.0% y/y in September, the largest y/y decrease of any month in 2026 so far.
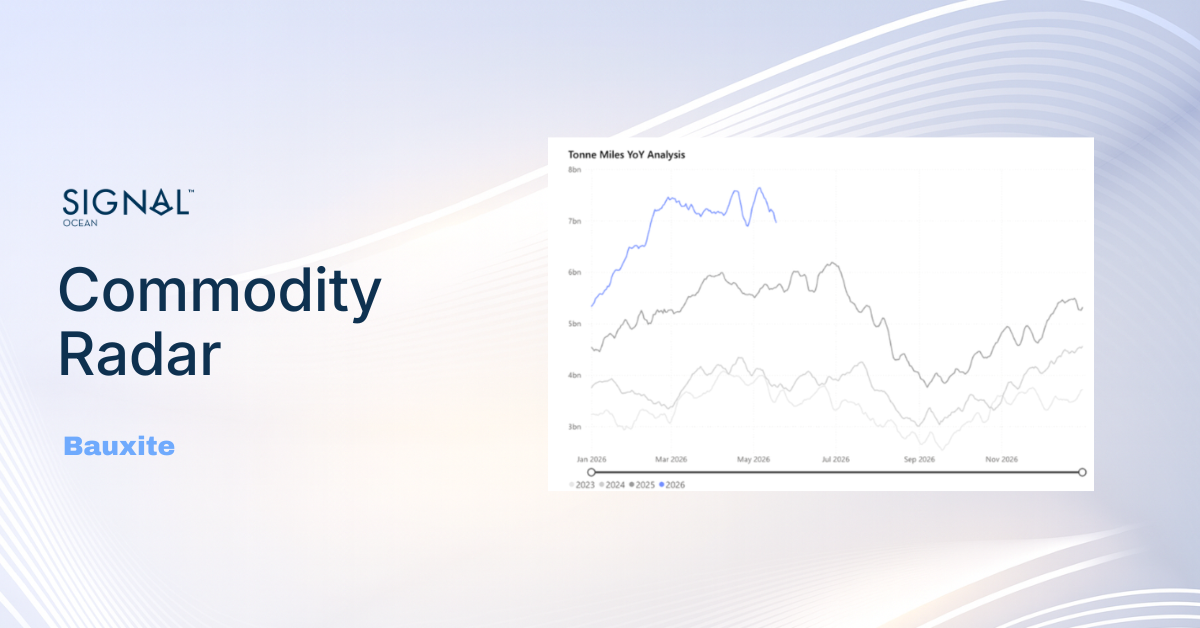
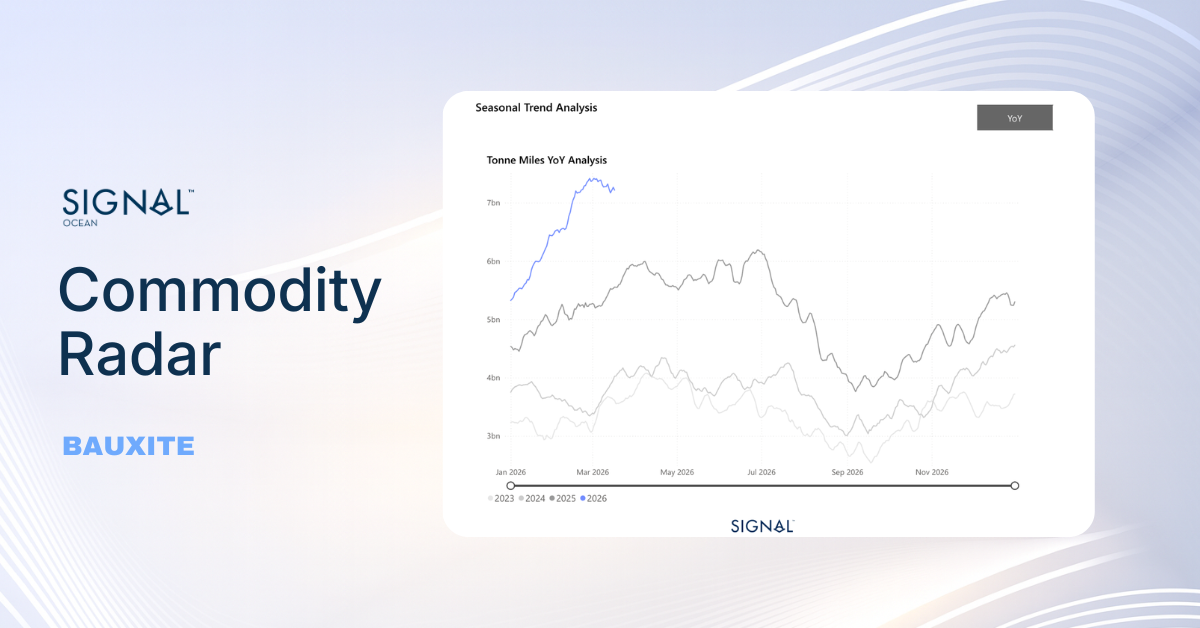
Source: Tonne-miles and Tonne-days of bauxite carrying vessels from Signal Ocean https://app.signalocean.com/dry/dynamic/timeseries_dry
Bauxite flows in September 2026 rose 3% to 20.4 Mt, driven by higher flows from Guinea. Flows fell m/m, but this was expected as September falls within the wet season, which typically reduces the ability of material to flow out of the ports. Compared to September 2025, flows from Guinea increased by over 20%.
China received a surge of seaborne bauxite inflows during September, reaching 19.7 Mt, up over 21% from the same period a year earlier. Disruptions to shipping norms in the Arabian Gulf have continued to affect bauxite arrivals in the UAE, and some regional processing facilities are operating below normal utilization levels, leading to a 60% drop in bauxite arrivals in September 2026.
India has been a key landing spot for seaborne bauxite that could not reach the Arabian Gulf, with Q1 and Q2 arrivals well ahead of the previous year. 2026 Q3 finished with a decrease y/y of 13.8%. This was driven by several factors, such as adequate stocks not requiring additional material and monsoons affecting domestic logistics operations.
Source: Seaborne bauxite flows from Signal Ocean https://app.signalocean.com/dry/dynamic/drybulkflows
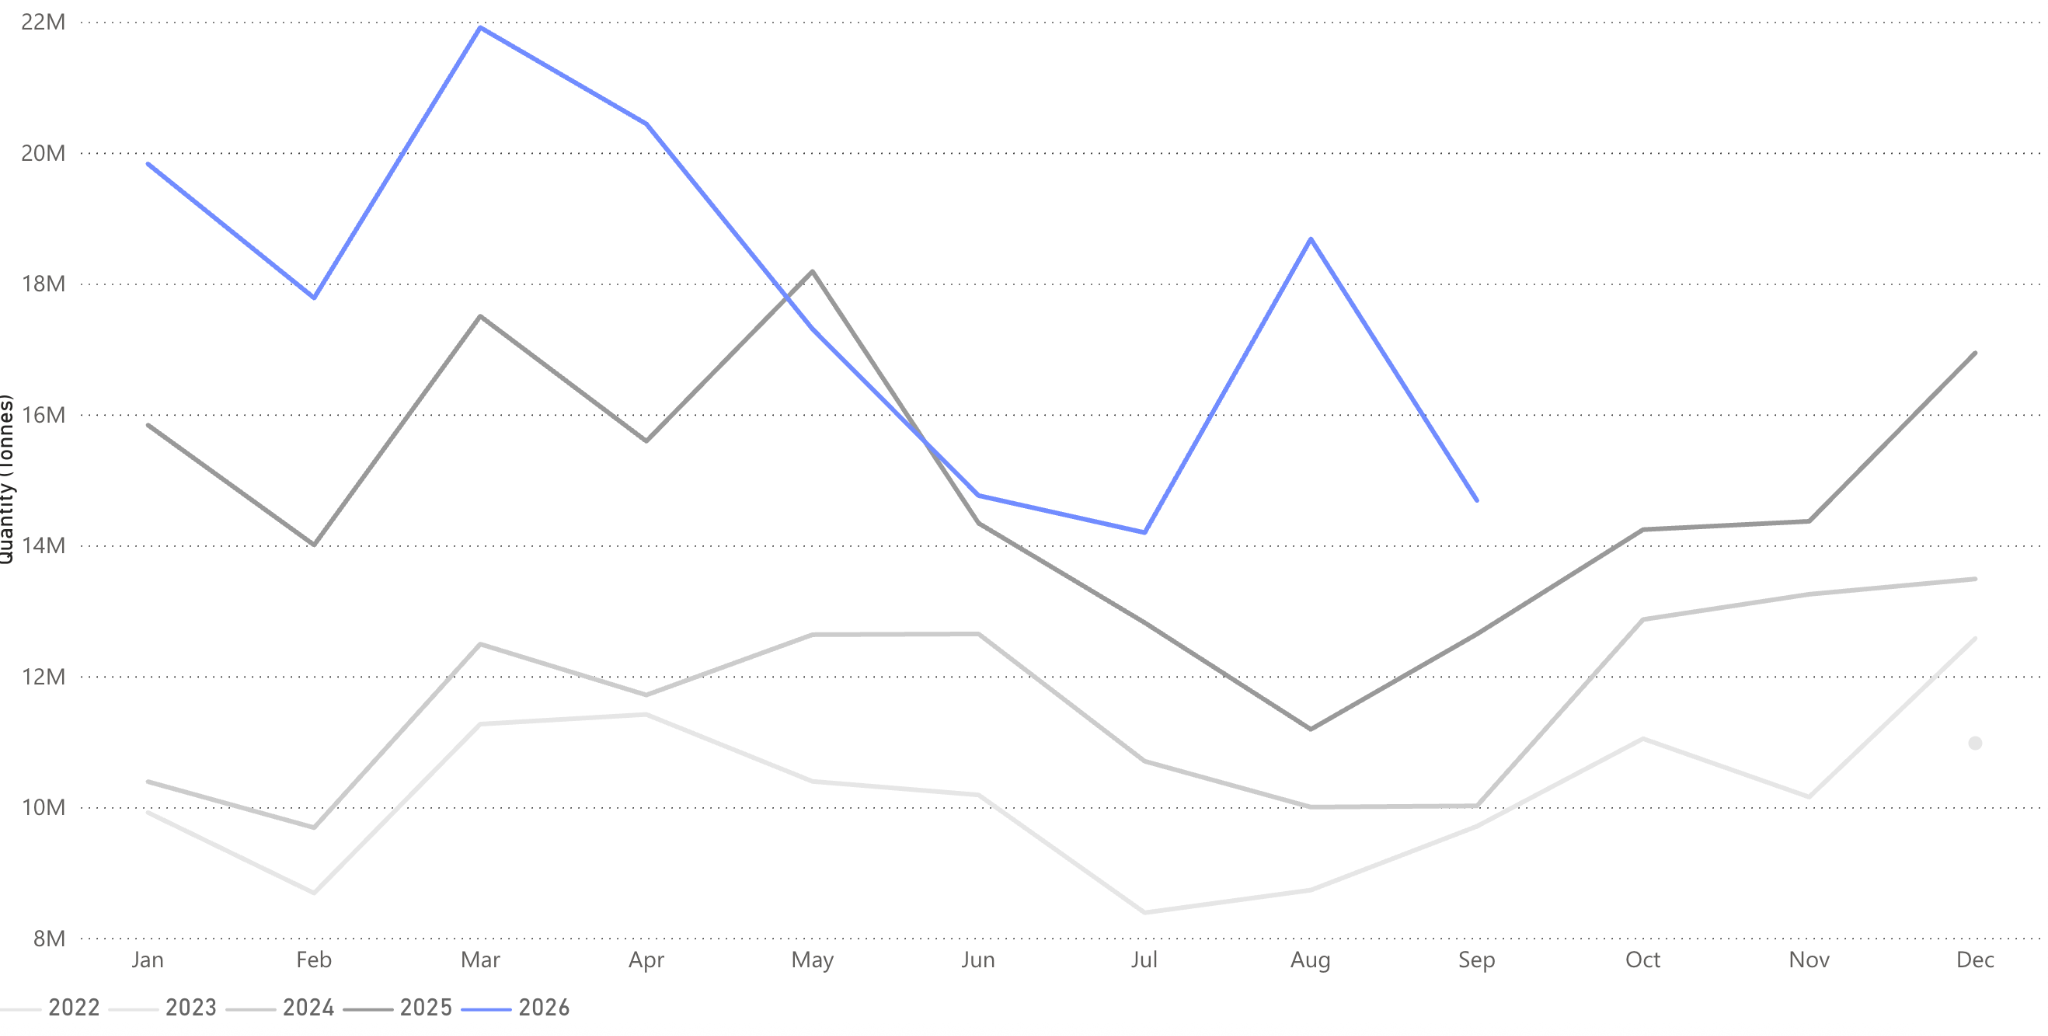
The outlook for global bauxite flows is softer in Q4 2026, with Guinea’s export restrictions expected to constrain shipments in the final months of the year. In June, Guinea introduced an annual export quota of 150 Mt, 18% below 2025 levels. However, Signal Ocean data show Guinean bauxite exports up 21% year-to-date, implying that shipments will need to slow materially in Q4.
Demand growth elsewhere is unlikely to offset this reduction. India remains well supplied, limiting the need for stronger year-on-year imports, while persistent regional tensions and disruption are expected to constrain demand recovery in the Arabian Gulf. Chinese demand should remain comparatively resilient, but significant upside appears limited: bauxite arrivals were flat year-on-year in Q3, suggesting little underlying growth in import requirements. With Guinea accounting for the majority of China’s imported bauxite, lower Guinean loadings are likely to translate into weaker Chinese arrivals, although existing inventories and cargoes already in transit may cushion the initial impact. Overall, the balance of risks points to softer global bauxite flows in Q4.
Source: Monthly exports of bauxite from Guinea in 2026 from Signal Ocean https://app.signalocean.com/dry/dynamic/drybulkflows
Front loading leads to a weaker final quarter outlook
Global bauxite flows are expected to soften in Q4 as Chinese front-loading eases and Guinea’s export restrictions begin to constrain supply. September’s surge in Chinese arrivals contrasts with weakening demand across India and the Arabian Gulf, where adequate stocks and ongoing regional disruption limit the potential for a recovery. With Indian inventories well supplied and Gulf processing activity subdued, neither market is likely to absorb significantly more seaborne material in the coming months. China should remain the principal destination for global bauxite, but flat year-on-year arrivals in Q3 suggest limited scope for further demand growth. Although cargoes already in transit and existing inventories may cushion the initial impact, lower Guinean loadings are likely to weigh on arrivals towards year-end. Consequently, the balance of risks points to weaker global flows and reduced Capesize tonne-mile demand in Q4.
Luke has over 8-years of experience analysing and forecasting commodity markets, with particular expertise in stainless steel raw materials and the wider metals markets.
Creating a sustainable world requires us to embark on a journey towards a zero emission future, where every step is a commitment to preserve our planet for future generations.
Albert Greenway
Environmental Scientist, Sustainability Expert
No items found.
Increased Use of Renewable Energy:
Shipping companies are embracing renewable energy sources to power onboard systems and reduce emissions during port operations. Solar panels and wind turbines are being installed on vessels to generate clean energy, reducing reliance on auxiliary engines, and cutting down emissions. Shore power facilities in ports allow ships to connect to the electrical grid, eliminating the need for onboard generators while docked.
Collaboration and Industry Partnerships:
Recognizing that addressing emissions requires collective action, shipping companies, governments, and organizations have formed partnerships and collaborations. These initiatives focus on research and development, sharing best practices, and promoting knowledge transfer. Joint projects aim to develop and deploy innovative technologies, improve infrastructure, and create a supportive regulatory framework to accelerate the industry's transition towards a greener future. The Zero Emission Shipping - Mission Innovation.
To pave the way for a greener future in shipping, the availability of alternative fuels plays a vital role in their widespread adoption. However, this availability is influenced by factors such as port infrastructure, local regulations, and government policies. As the demand for cleaner fuels in shipping rises and environmental regulations become more stringent, efforts are underway to improve the accessibility of these fuels through infrastructure development, collaborations, and investments in production facilities.
Liquefied Natural Gas (LNG) infrastructure has seen significant growth in recent years, resulting in more LNG bunkering facilities and LNG-powered vessels. Nonetheless, the availability of LNG as a marine fuel can still vary depending on the region. To ensure consistent availability worldwide, there is a need for further development of LNG supply chains and infrastructure. For biofuels, their availability hinges on production capacity and the availability of feedstock. Although biofuels are being produced and utilized in various sectors, their availability as a marine fuel remains limited. Scaling up biofuel production and establishing robust supply chains are imperative to ensure wider availability within the shipping industry.Hydrogen, as a fuel for maritime applications, is still in the early stages of infrastructure development. While some hydrogen vessels have been tested or introduced in the first quarter of last year, the infrastructure required for hydrogen production and distribution needs further advancement.
Ammonia, as a marine fuel, currently faces limitations in availability. The production, storage, and handling infrastructure for ammonia need further development to support its widespread use in the shipping industry.Methanol, on the other hand, is already a commercially available fuel and has been used as a blend with conventional fuels in some ships. However, its availability as a standalone marine fuel can still be limited in certain regions. Bureau Veritas in October 2022 published a White Paper for the Alternative Fuels Outlook. This white paper provides a comprehensive overview of alternative fuels for the shipping industry, taking into account key factors such as technological maturity, availability, safety, emissions, and regulations.
Creating a sustainable world requires us to embark on a journey towards a zero emission future, where every step is a commitment to preserve our planet for future generations.
Albert Greenway
Environmental Scientist, Sustainability Expert
Increased Use of Renewable Energy:
Shipping companies are embracing renewable energy sources to power onboard systems and reduce emissions during port operations. Solar panels and wind turbines are being installed on vessels to generate clean energy, reducing reliance on auxiliary engines, and cutting down emissions. Shore power facilities in ports allow ships to connect to the electrical grid, eliminating the need for onboard generators while docked.
Collaboration and Industry Partnerships:
Recognizing that addressing emissions requires collective action, shipping companies, governments, and organizations have formed partnerships and collaborations. These initiatives focus on research and development, sharing best practices, and promoting knowledge transfer. Joint projects aim to develop and deploy innovative technologies, improve infrastructure, and create a supportive regulatory framework to accelerate the industry's transition towards a greener future. The Zero Emission Shipping - Mission Innovation.
To pave the way for a greener future in shipping, the availability of alternative fuels plays a vital role in their widespread adoption. However, this availability is influenced by factors such as port infrastructure, local regulations, and government policies. As the demand for cleaner fuels in shipping rises and environmental regulations become more stringent, efforts are underway to improve the accessibility of these fuels through infrastructure development, collaborations, and investments in production facilities.
Liquefied Natural Gas (LNG) infrastructure has seen significant growth in recent years, resulting in more LNG bunkering facilities and LNG-powered vessels. Nonetheless, the availability of LNG as a marine fuel can still vary depending on the region. To ensure consistent availability worldwide, there is a need for further development of LNG supply chains and infrastructure. For biofuels, their availability hinges on production capacity and the availability of feedstock. Although biofuels are being produced and utilized in various sectors, their availability as a marine fuel remains limited. Scaling up biofuel production and establishing robust supply chains are imperative to ensure wider availability within the shipping industry.Hydrogen, as a fuel for maritime applications, is still in the early stages of infrastructure development. While some hydrogen vessels have been tested or introduced in the first quarter of last year, the infrastructure required for hydrogen production and distribution needs further advancement.
Ammonia, as a marine fuel, currently faces limitations in availability. The production, storage, and handling infrastructure for ammonia need further development to support its widespread use in the shipping industry.Methanol, on the other hand, is already a commercially available fuel and has been used as a blend with conventional fuels in some ships. However, its availability as a standalone marine fuel can still be limited in certain regions. Bureau Veritas in October 2022 published a White Paper for the Alternative Fuels Outlook. This white paper provides a comprehensive overview of alternative fuels for the shipping industry, taking into account key factors such as technological maturity, availability, safety, emissions, and regulations.