Subscribe for our latest news, straight to your inbox:
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Share this post
SPOTLIGHT OF THE WEEK | CAPESIZE ROUTES
Brazil Premium Rebuilds: C3–C5 Spread Back Above $21/mt
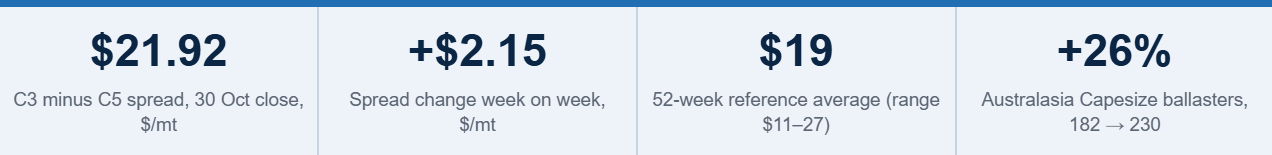
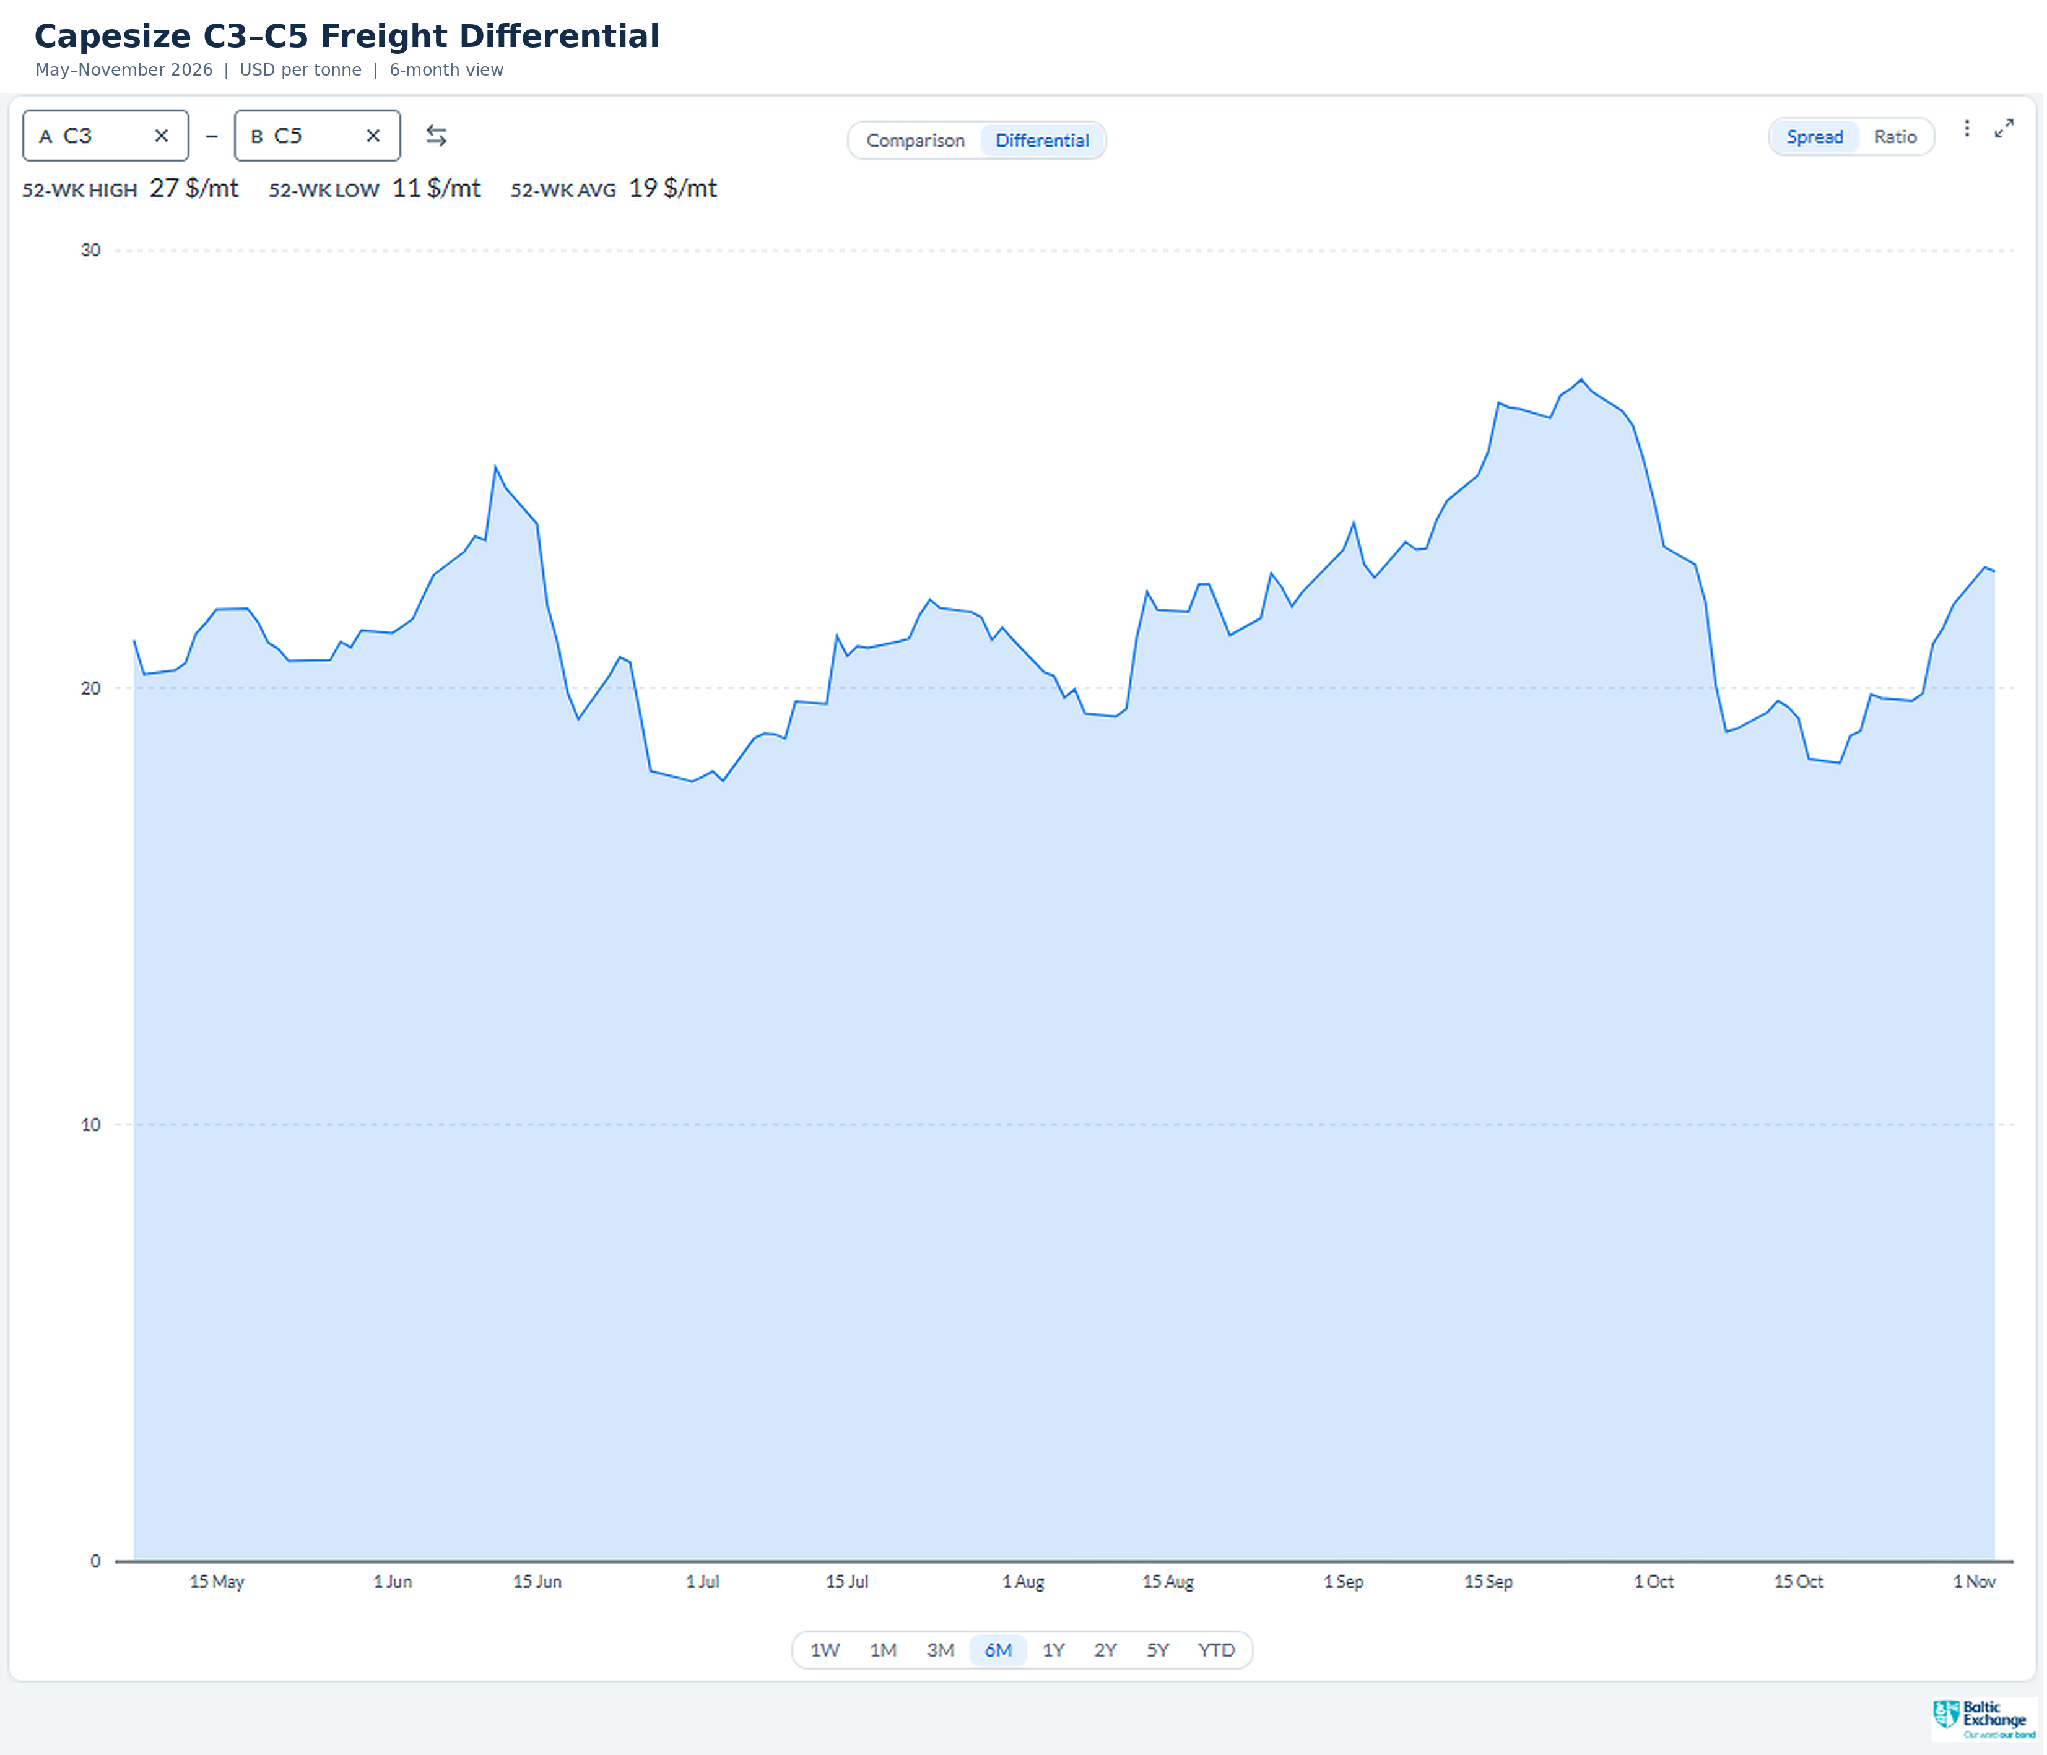
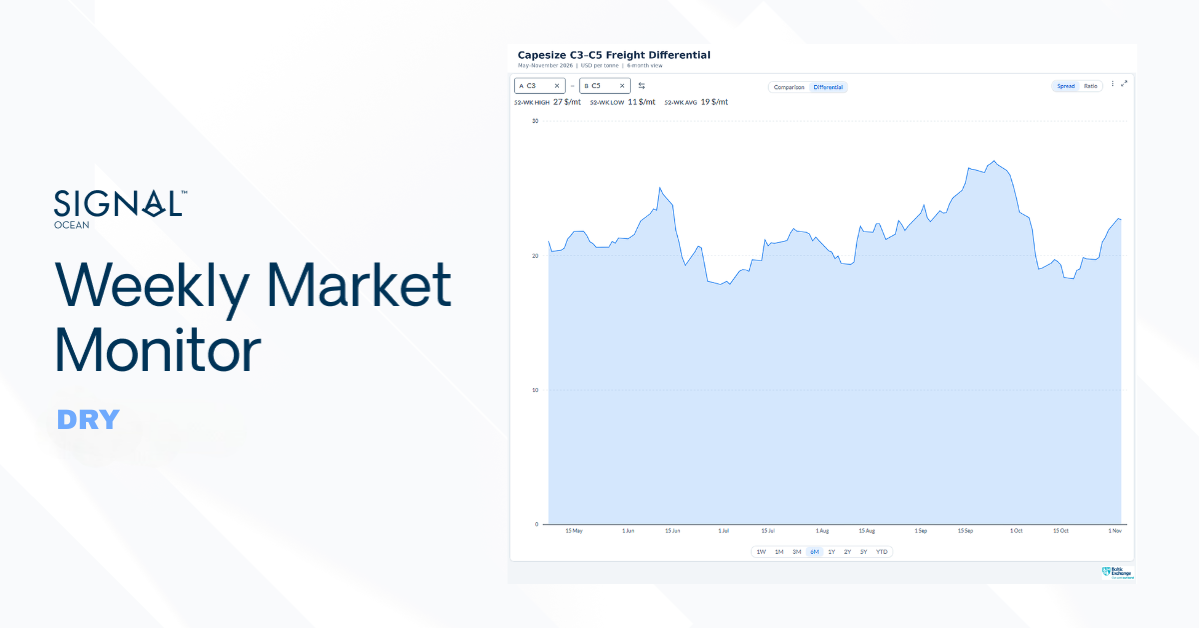
Brazil–China freight pulled away from West Australia–China for a second week. C3 Tubarao–Qingdao rose by $2.93/mt to $36.80/mt; C5 West Australia–Qingdao rose by only $0.78/mt to $14.88/mt. At the 30 October close, the spread was $21.92/mt, up $2.15/mt from $19.77/mt a week earlier and above its 52-week reference average of $19/mt. It had fallen from about $27/mt in late September to about $18/mt in mid-October. A later reading, on 2 November, put it near $22.7/mt.
Figure 1: Capesize C3–C5 freight differential (C3 Tubarao–Qingdao minus C5 West Australia–Qingdao), $/mt, May–November 2026. (Source: Signal/ Baltic Exchange).
SUPPLY & DEMAND | Weekly Volatility
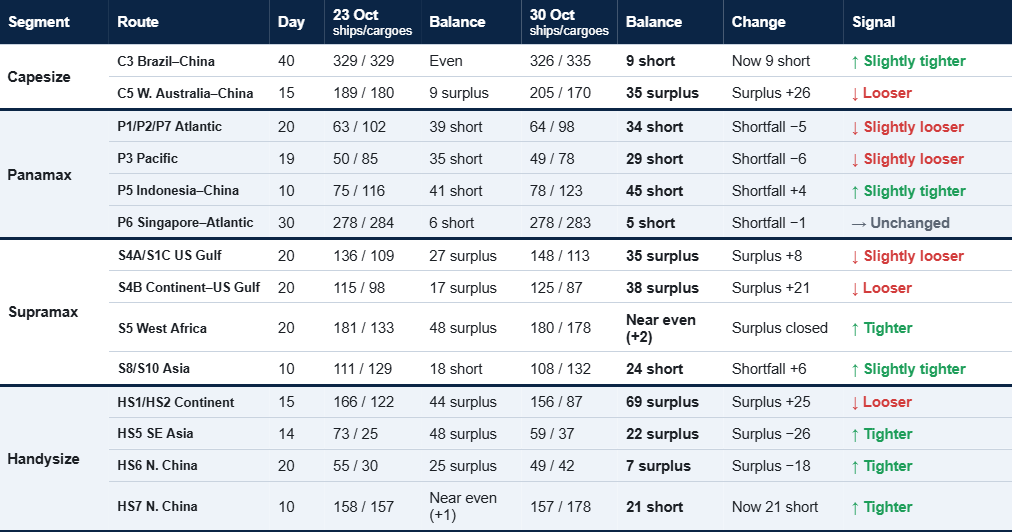
In the Capesize market, C3 Brazil–China tightened slightly as available ship counts fell below expected cargoes to around day 36, while C5 West Australia–China moved into surplus as vessel supply expanded to 205 against 170 cargoes by day 15. Panamax forward counts showed little net change overall; however, P1/P2/P7 Atlantic and P3 Pacific experienced slight loosening, whereas P5 Indonesia–China tightened slightly and P6 Singapore–Atlantic remained unchanged. Across geared vessel segments, US Gulf Supramax routes (S4A/S1C and S4B) and Continent Handysize (HS1/HS2) loosened further, with vessel surpluses widening. Conversely, Supramax S5 West Africa, S8/S10 Asia, and Handysize routes HS5 SE Asia, HS6 North China, and HS7 North China all tightened, with HS7 swinging from near-even balance into a 21-ship shortfall.
Table 2: Available ships vs expected cargoes, cumulative counts read from the Signal dashboards at the same forecast day for both weeks (approximate). Balance = ships minus cargoes: “short” = fewer ships than cargoes (tight); “surplus” = more ships than cargoes (loose); within ±3 = even. Change = how the shortfall or surplus moved week on week. Signal rule: a move of 3 ships or less, or under 2.5% of cargoes = Unchanged; under 10% = Slightly tighter/looser; 10% or more = Tighter/Looser. Previous = 23 Oct dashboards; this week = 30 Oct. Forecast horizons differ by route.
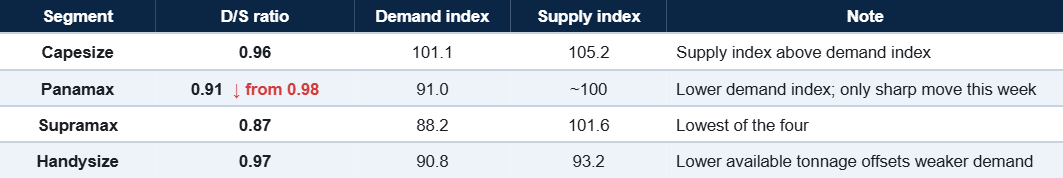
Demand vs supply ratio. A slower, fleet-wide measure. Each index compares the current four-week mean with the same four weeks a year earlier (×100).
Table 3: Tonne-mile demand index and available-tonnage supply index (prior year = 100) and their ratio, week ending 29 Oct 2026. Latest readings provisional. Capesize supply excludes contract-committed VLOC tonnage; Handysize demand is Voyage API tonne-miles only (Source: Signal – Voyage API, Vessel Daily Status).
FREIGHT MARKET OVERVIEW
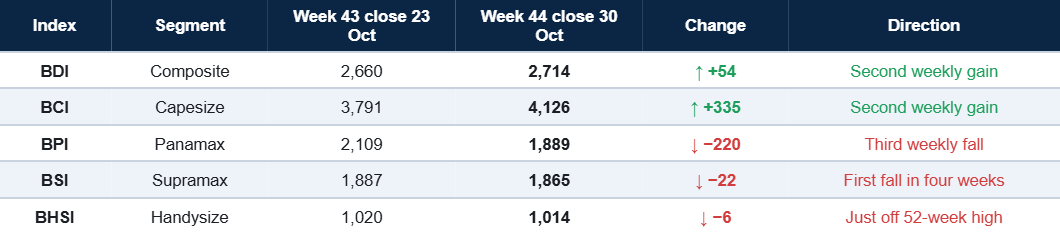
Table 4: Baltic indices, weekly close. Week 43 close = 30 Oct close less the Baltic weekly change (Source: Baltic Exchange).
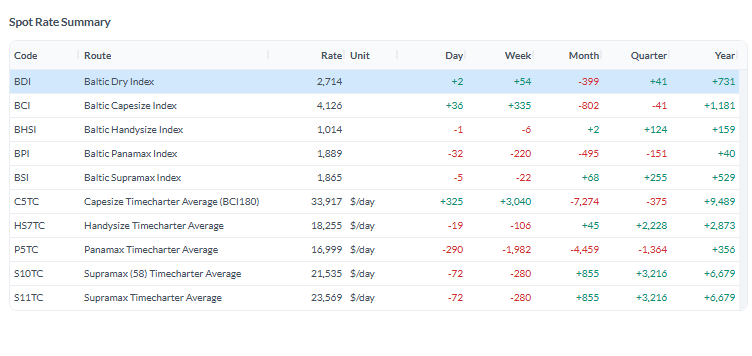
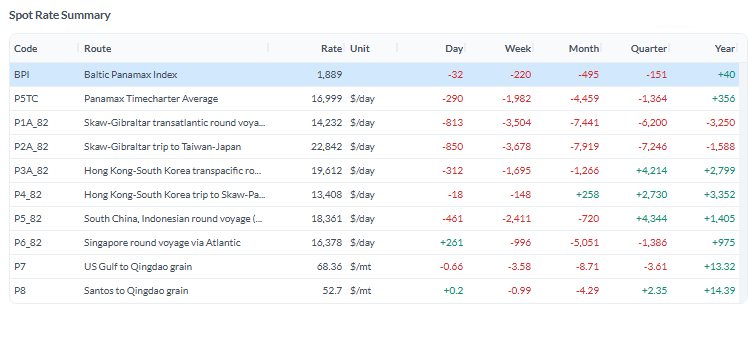
From Week 43 to Week 44. Capesize led the market: the BCI rose 335 points to 4,126, and C5TC(180) rose $3,040/day to $33,917/day, with every route higher. Panamax went the other way: the BPI fell 220 points to 1,889, and P5TC fell by $1,982/day to $16,999/day, with every route lower. The BDI closed October at 2,714, down 399 points on the month and up 731 on the year.
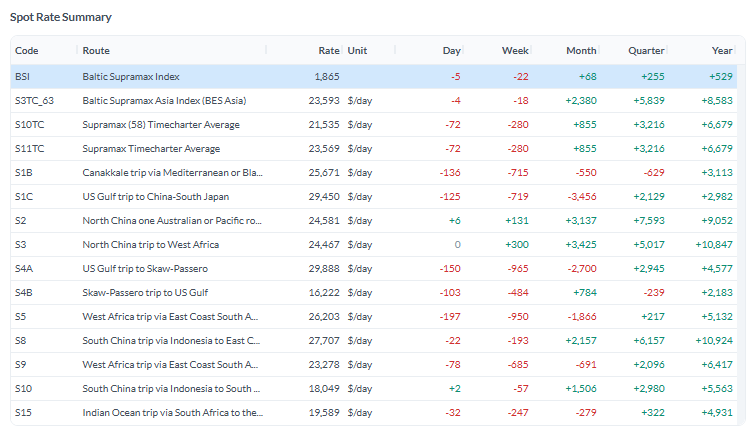
Geared sizes pause near the top. The BSI fell 22 points to 1,865, 25 below its 52-week high; the BHSI fell 6 points to 1,014, 6 below its own. Against the Week 43 readings, Supramax ballasters rose 5%, and Handysize ballasters fell 3%.
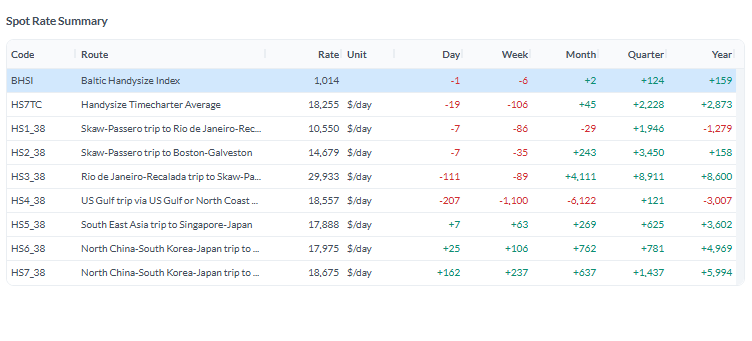
Figure 2: Baltic spot rate summary, close 30 Oct 2026. BDI 52-week reference values: high 3,628, low 1,532, average 2,555 (Source: Baltic Exchange).
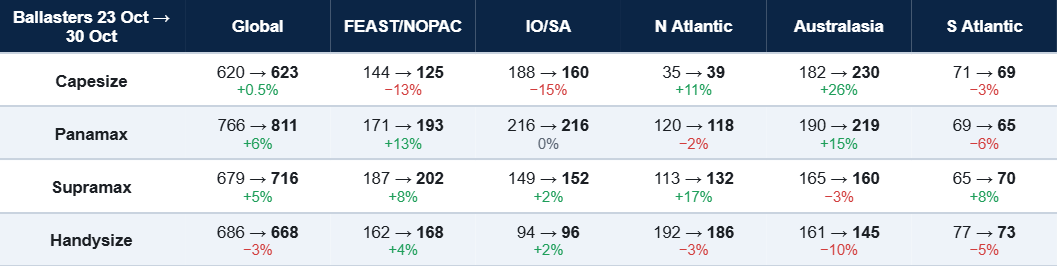
Table 5: Ballasters (empty ships heading to load), Week 43 (23 Oct) → Week 44 (30 Oct) reading, and change. The dashboards' own week-on-week percentages use a different base and are not used here (Source: Signal).
KEY TAKEAWAY
Capesize: C3 ships stay below cargoes to about day 36 (day 20 a week earlier), while C5 ships now cover cargoes throughout; Australasia ballasters rose 26% to 230. The C3–C5 spread closed at $21.92/mt, above its 52-week average.
Panamax: third weekly fall, every route lower. Forward route counts moved little, but the D/S ratio fell to 0.91 from 0.98, and global ballasters rose 6% to 811.
Supramax and Handysize: near 52-week highs. US Gulf and Continent surpluses widened and are the main drag for the next fixing window; Asian shortfalls (S8/S10, HS7) are the support.
CAPESIZE
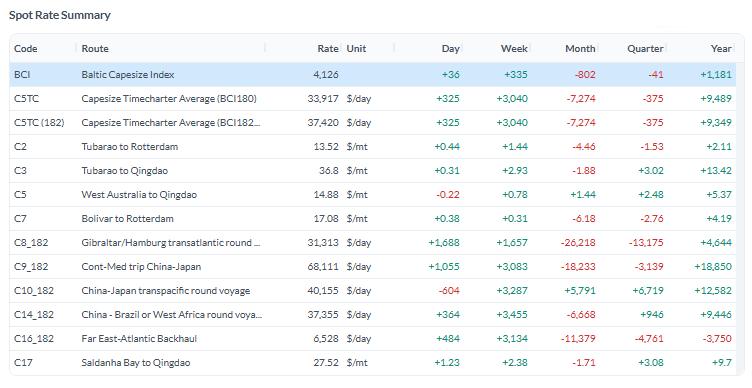
Freight. The BCI rose 335 points to 4,126, and C5TC(180) rose by $3,040/day to $33,917/day (C5TC(182) $37,420/day). Every route gained: C14_182 +$3,455/day to $37,355/day, C10_182 +$3,287/day to $40,155/day, C3 +$2.93/mt to $36.80/mt, and C5 +$0.78/mt to $14.88/mt. C9_182 remains the top route at $68,111/day.
Cargo backdrop. Iron ore hit a two-year low: SGX touched $89.25/t on 27 October. China’s October manufacturing PMI dropped to 49.3 from 50.1, back in contraction. Weaker steel demand is the risk to Q4 ore buying; so far Capesize rates have moved the other way.
Figure 3: Capesize route rates, close 30 Oct 2026 (Source: Baltic Exchange).
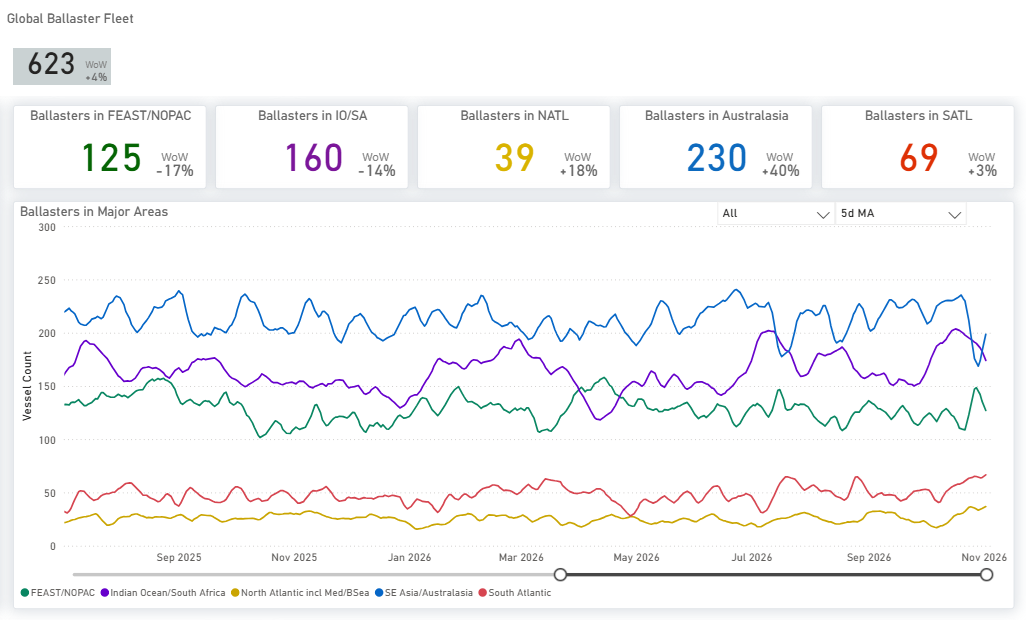
Figure 4: Capesize ballasters by region, 5-day MA; dashboard WoW uses its own base, see Table 5 (Source: Signal).
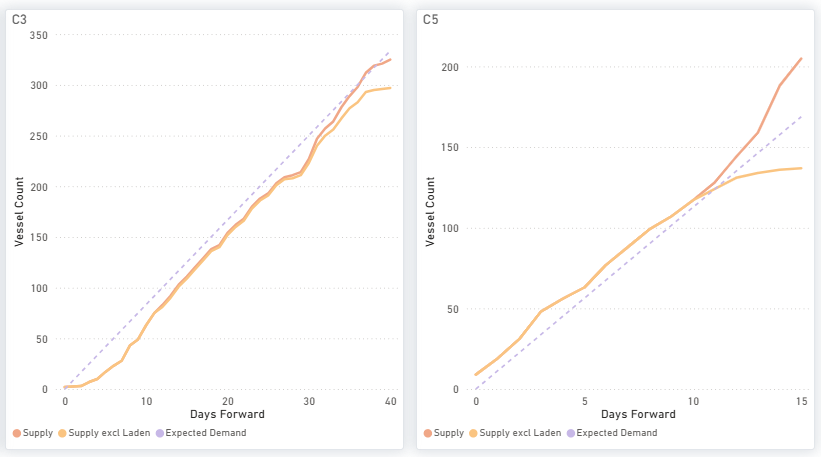
Figure 5: Capesize available ships (supply) vs expected cargoes (demand), by days ahead (Source: Signal).
Ships vs cargoes. C3: ships below cargoes to about day 36 (326 vs 335 by day 40). C5: ships at or above cargoes throughout (205 vs 170 by day 15). Ballasters vs Week 43: Australasia 182→230 (+26%); FEAST/NOPAC 144→125 (−13%); IO/SA 188→160 (−15%).
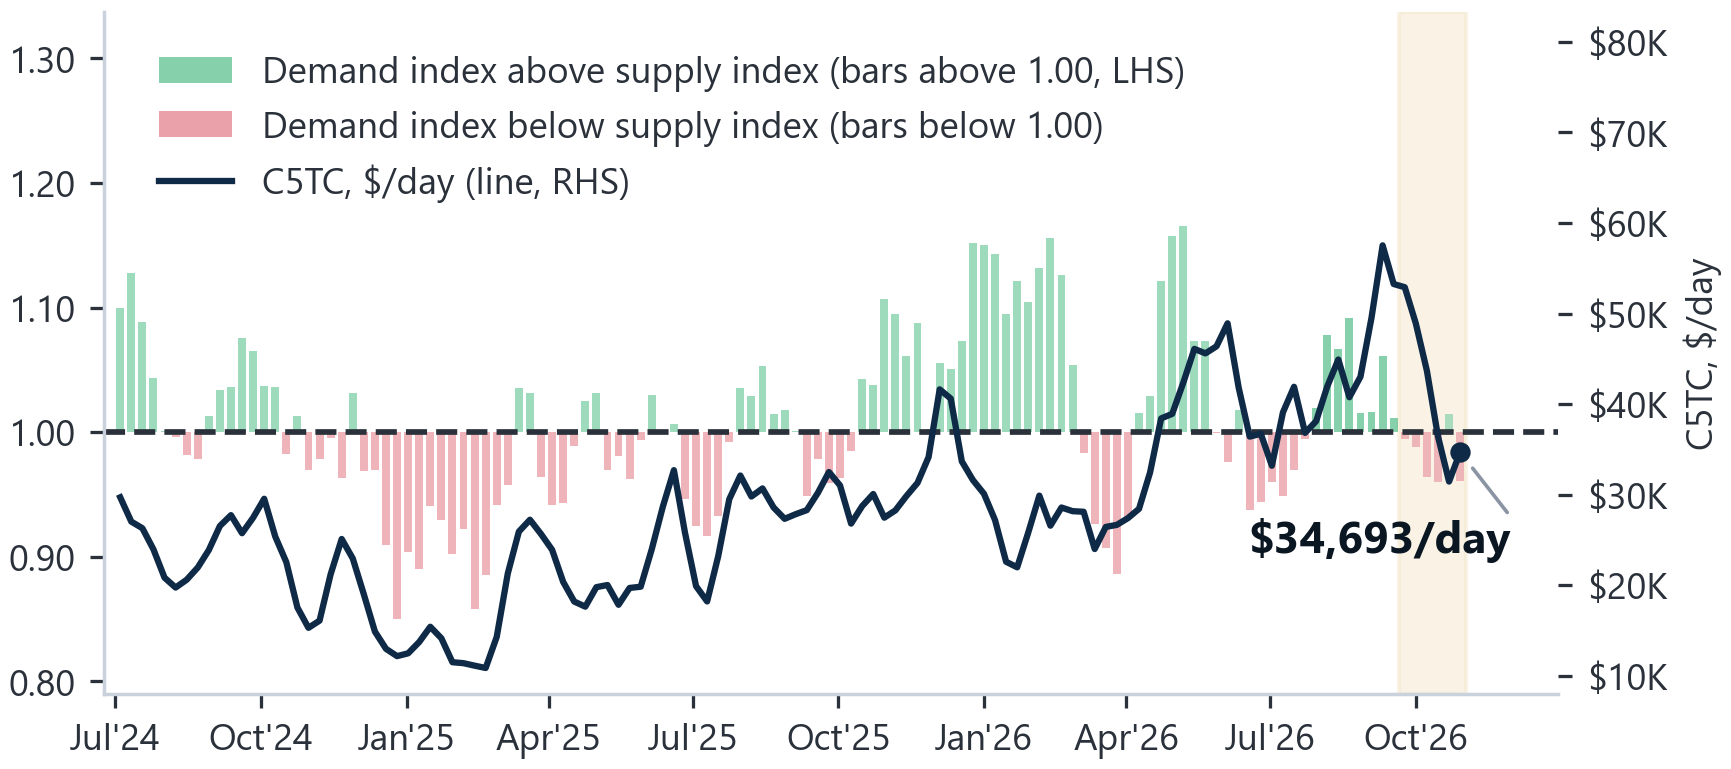
Figure 6: Capesize D/S ratio (bars, LHS) and C5TC weekly average (line, RHS), Jul 2024–Oct 2026; shaded = latest six weeks, provisional (Source: Baltic Exchange; Signal).
Demand vs. supply. D/S ratio 0.96: demand index 101.1, supply index 105.2. The rate gain came with the ratio below 1.00, consistent with a positioning-led move rather than fleet-wide tightness.
PANAMAX
Freight. The BPI fell 220 points to 1,889, and P5TC fell by $1,982/day to $16,999/day, a third weekly fall, with every route lower. The Atlantic led: P2A_82 −$3,678/day to $22,842/day (still the top route) and P1A_82 −$3,504/day to $14,232/day. P5_82 fell by $2,411/day to $18,361/day and P7 by $3.58/mt to $68.36/mt.
Figure 7: Panamax route rates, close 30 Oct 2026 (Source: Baltic Exchange).
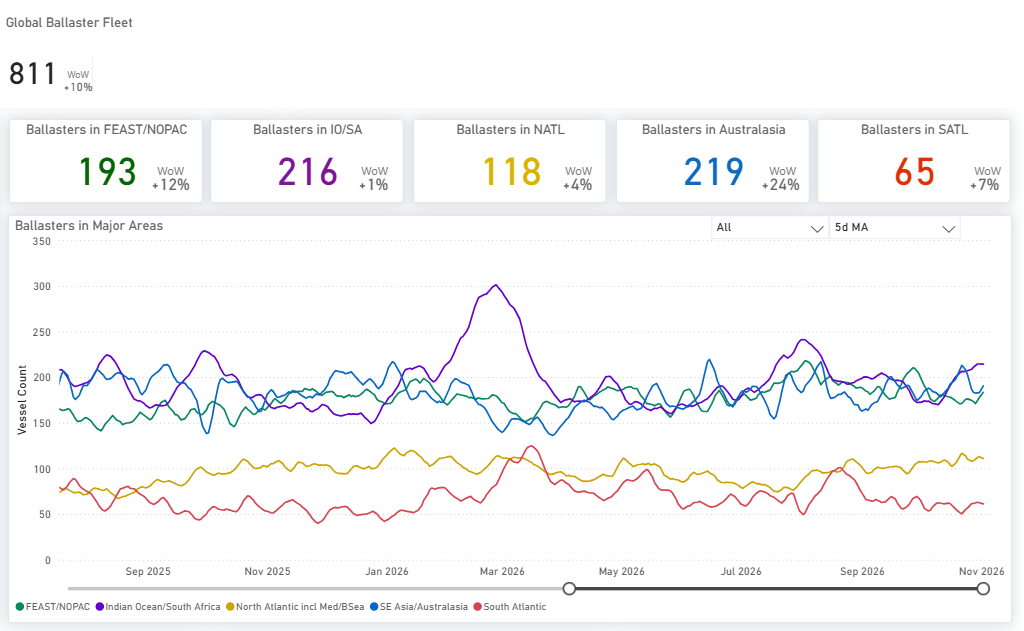
Figure 8: Panamax ballasters by region, 5-day MA; dashboard WoW uses its own base, see Table 5 (Source: Signal).
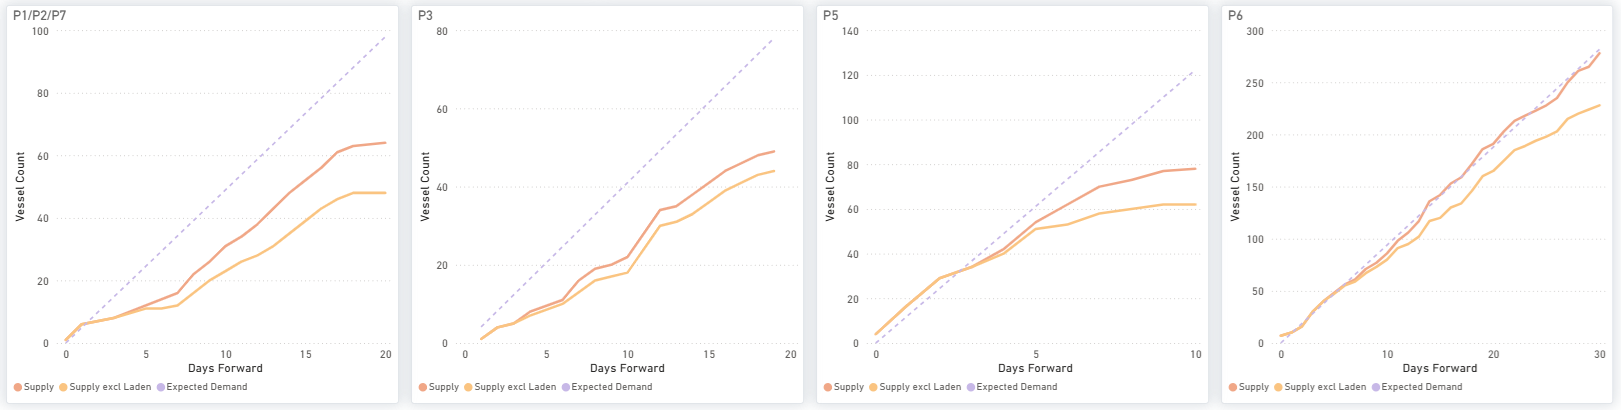
Figure 9: Panamax available ships (supply) vs expected cargoes (demand), by days ahead (Source: Signal).
Ships vs cargoes. Little net change. P1/P2/P7 64 vs 98 by day 20 (shortfall 5 smaller); P3 49 vs 78 by day 19 (6 smaller); P5 78 vs 123 by day 10 (4 larger); P6 278 vs 283 by day 30 (unchanged). Ballasters vs Week 43: global 766→811 (+6%); Australasia 190→219 (+15%); FEAST/NOPAC 171→193 (+13%).
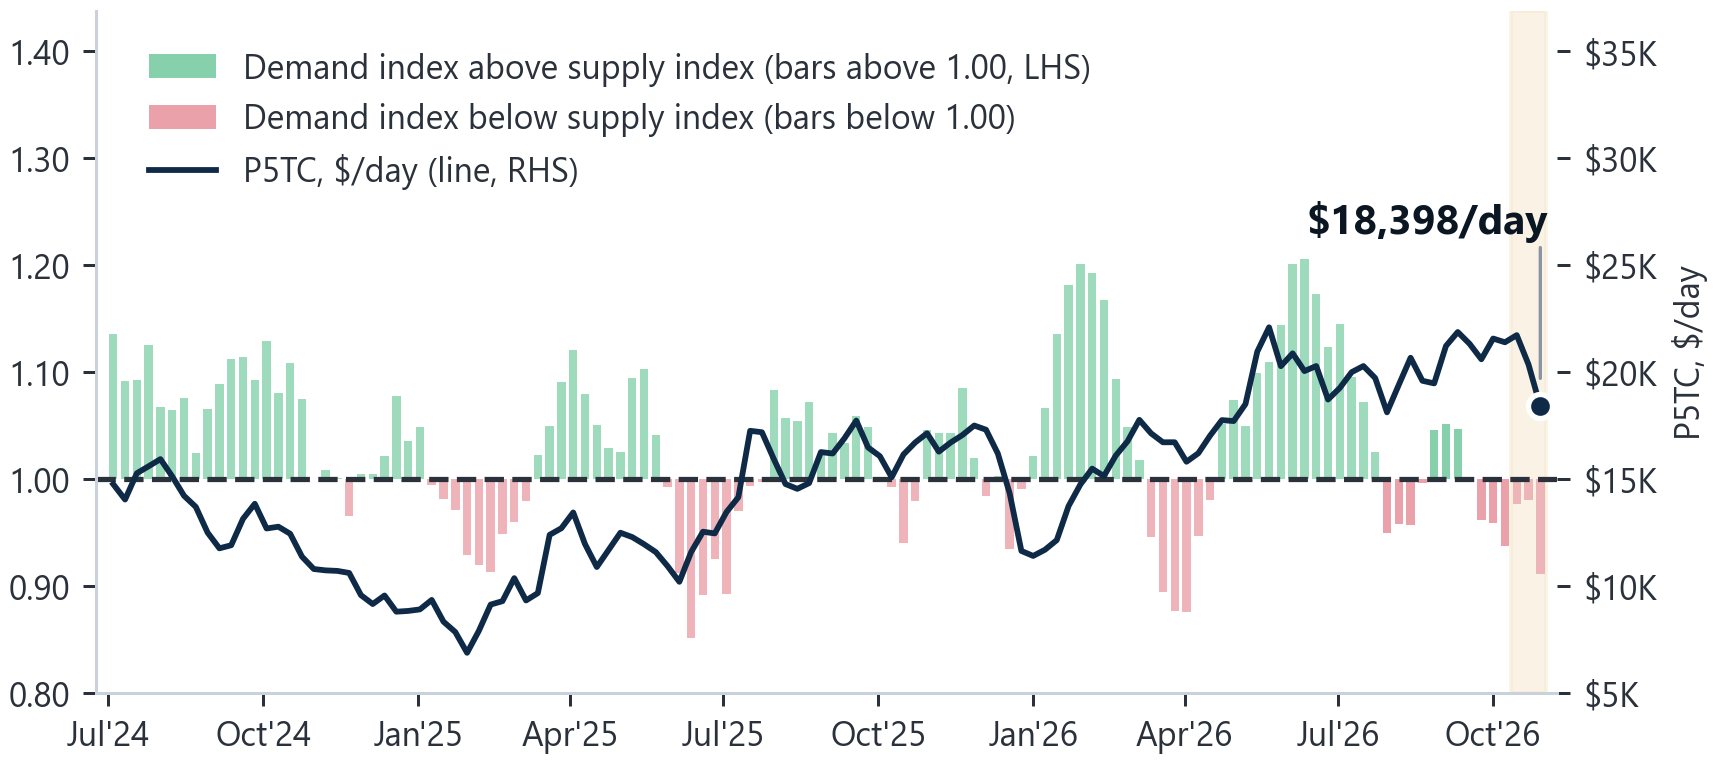
Figure 10: Panamax D/S ratio (bars, LHS) and P5TC weekly average (line, RHS), Jul 2024–Oct 2026; shaded = latest three weeks, provisional (Source: Baltic Exchange; Signal).
Demand vs supply. D/S ratio 0.91, from 0.98: demand index 91.0, supply index broadly unchanged. Route counts cover the next 10–30 days on specific routes; the ratio covers four weeks of fleet-wide tonne-miles against a year earlier, so the two can diverge.
SUPRAMAX
Freight. The BSI fell 22 points to 1,865, ending three weeks of gains 25 points below its 52-week high, and S11TC fell by $280/day to $23,569/day. The Atlantic led the fall: S4A −$965/day to $29,888/day, S5 −$950/day, and S1C −$719/day to $29,450/day. Asia held up: S3 +$300/day to $24,467/day and S2 +$131/day.
Figure 11: Supramax route rates, close 30 Oct 2026 (Source: Baltic Exchange).
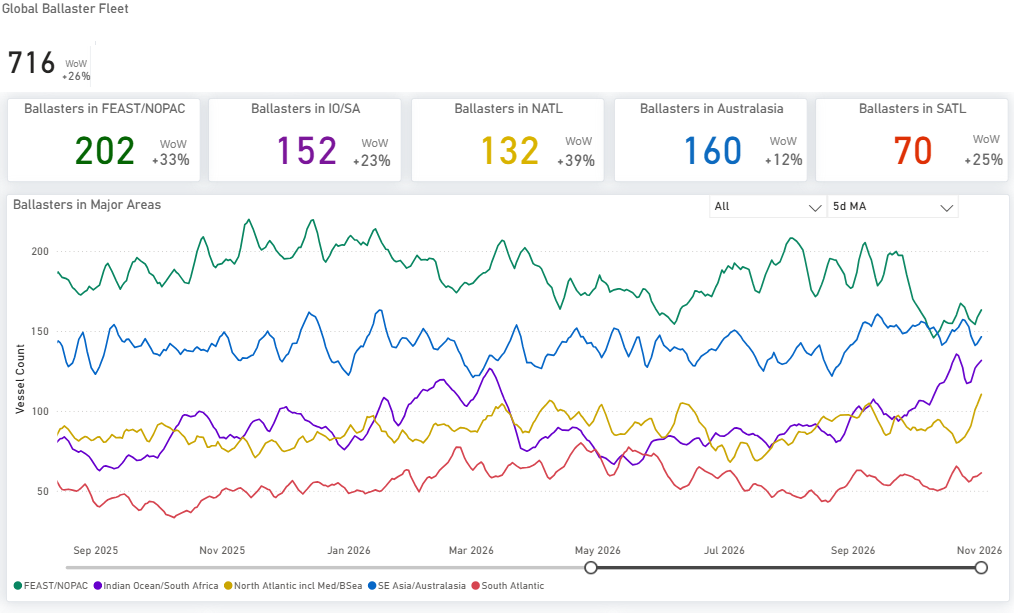
Figure 12: Supramax ballasters by region, 5-day MA; dashboard WoW uses its own base, see Table 5 (Source: Signal).
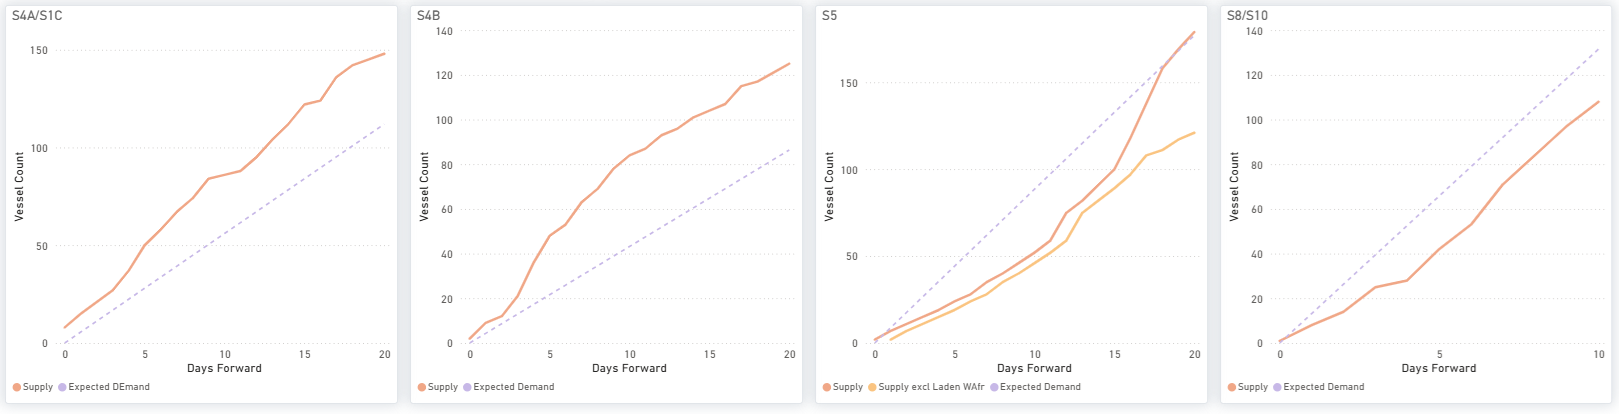
Figure 13: Supramax available ships (supply) vs expected cargoes (demand), by days ahead (Source: Signal).
Next fixing window. The US Gulf surplus is the main drag and widened: 148 ships vs 113 cargoes on S4A/S1C and 125 vs 87 on S4B by day 20. Asia is the support: S8/S10 108 vs 132 by day 10. S5 West Africa tightened to near balance (180 vs 178 by day 20, from 181 vs 133). Ballasters vs Week 43: global 679→716 (+5%); North Atlantic 113→132 (+17%).
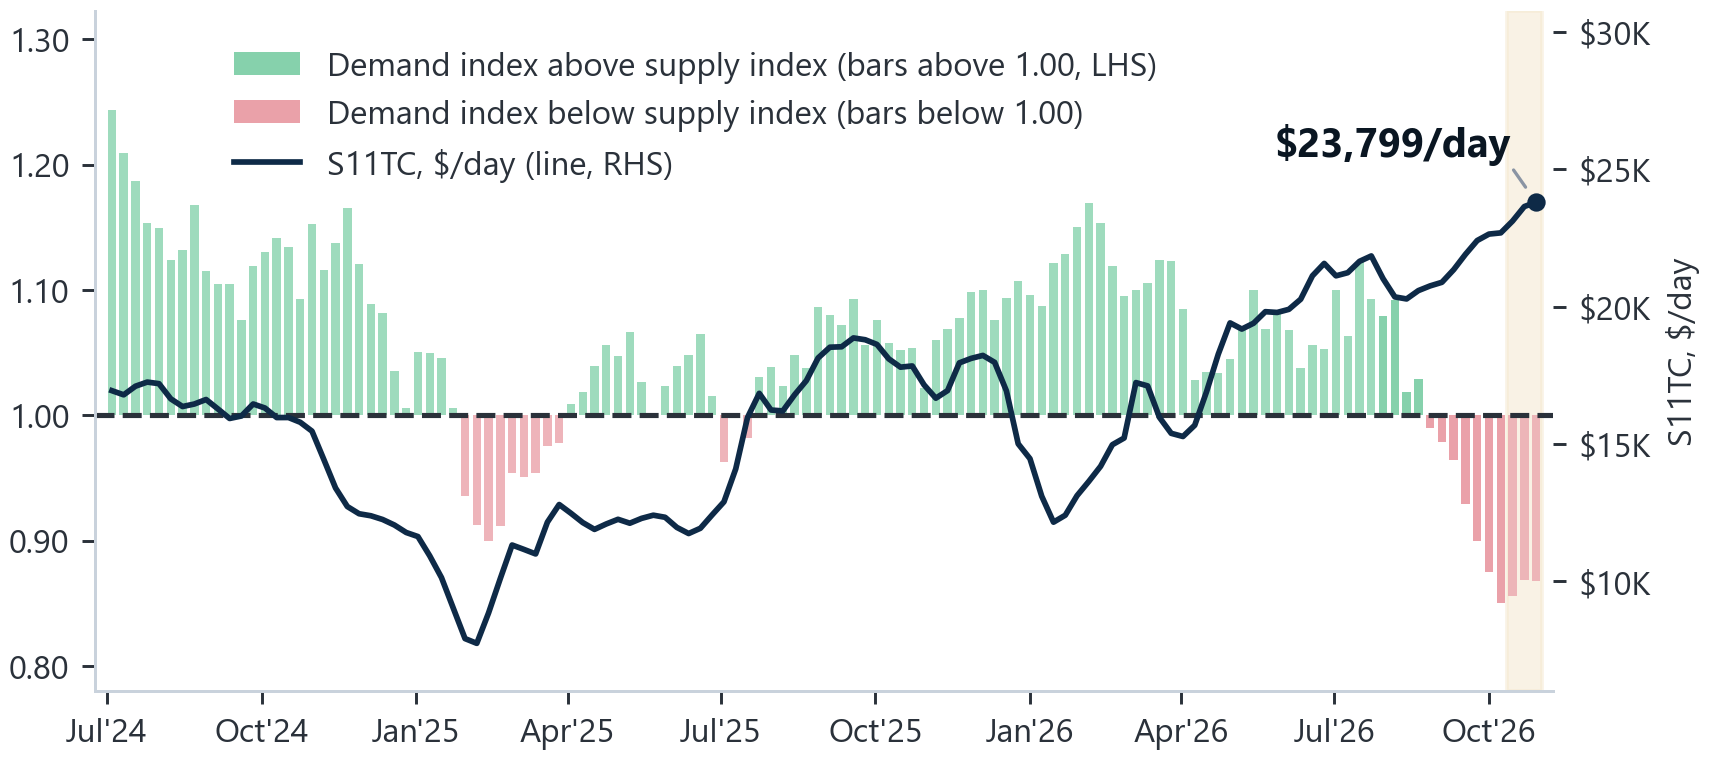
Figure 14: Supramax D/S ratio (bars, LHS) and S11TC weekly average (line, RHS), Jul 2024–Oct 2026; shaded = latest three weeks, provisional (Source: Baltic Exchange; Signal).
Demand vs. supply. D/S ratio 0.87, the lowest of the four: demand index 88.2, supply index 101.6. The BSI near its 52-week high reflects a few strong routes, not a broad demand recovery.
HANDYSIZE
Freight. The BHSI fell 6 points to 1,014, 6 below its 52-week high, and HS7TC fell by $106/day to $18,255/day. HS4_38 (US Gulf) fell by $1,100/day to $18,557/day. Asia firmed: HS7_38 +$237/day to $18,675/day, HS6_38 +$106/day, and HS5_38 +$63/day. HS3_38 (South Atlantic) remains the top route at $29,933/day.
Figure 15: Handysize route rates, close 30 Oct 2026 (Source: Baltic Exchange).
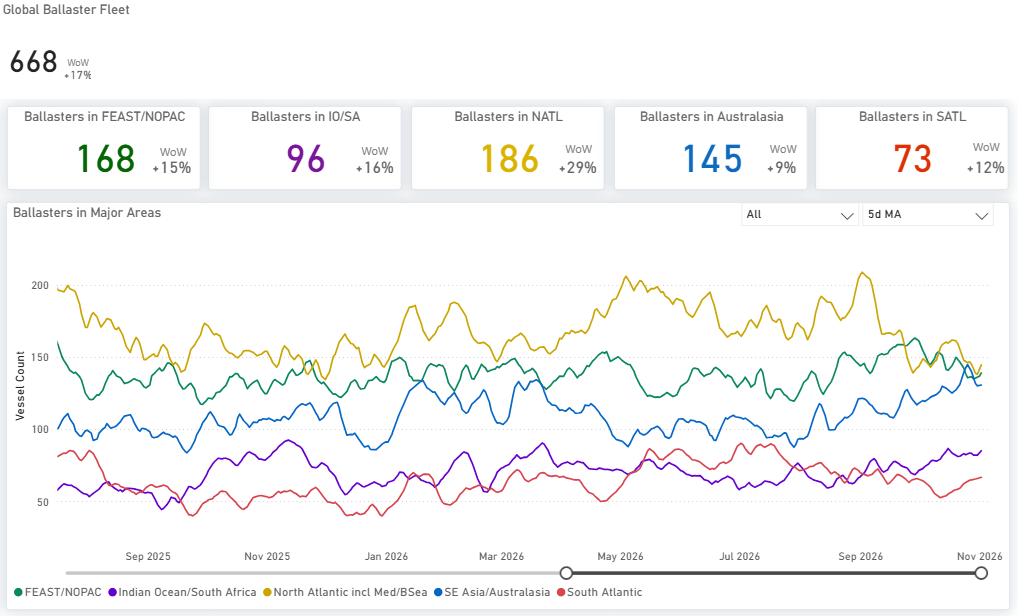
Figure 16: Handysize ballasters by region, 5-day MA; dashboard WoW uses its own base, see Table 5 (Source: Signal).
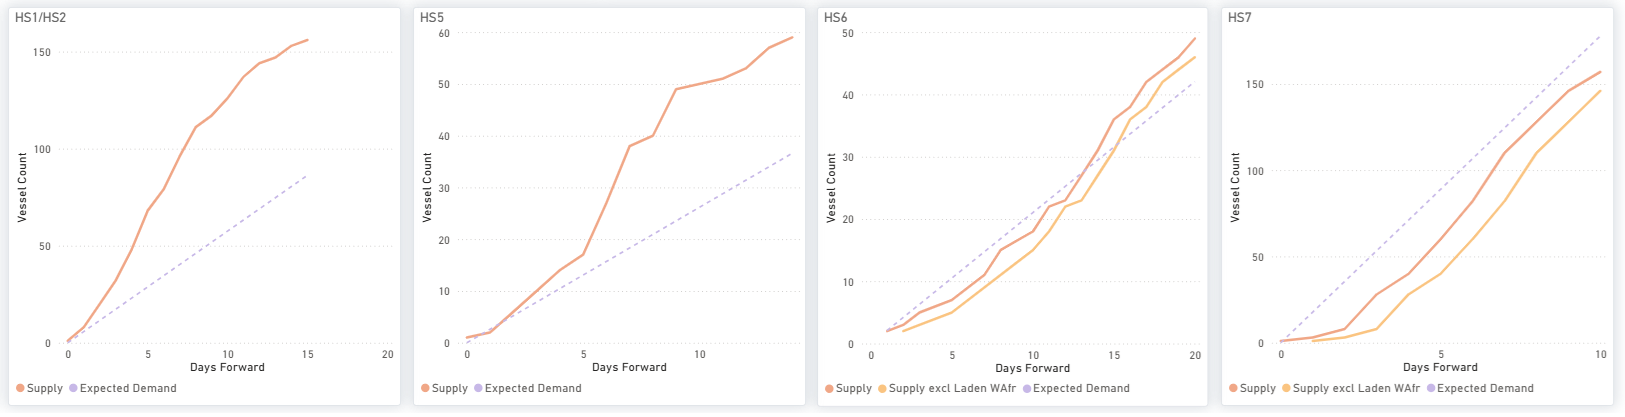
Figure 17: Handysize available ships (supply) vs expected cargoes (demand), by days ahead (Source: Signal).
Next fixing window. HS7 is the nearest-dated support: 157 ships vs 178 cargoes by day 10, from a balance a week earlier. HS1/HS2 is the main drag: 156 vs 87 by day 15. The HS5 surplus narrowed (59 vs 37 by day 14, from 73 vs 25) and HS6 is near balance (49 vs 42 by day 20). Ballasters vs Week 43: global 686→668 (−3%); Australasia 161→145 (−10%).
Disclaimer: This report has been prepared by Signal Group for general information purposes only. It does not constitute, and should not be relied upon as, investment, financial, trading, legal or commercial advice, or as a recommendation to enter into any transaction. While reasonable efforts have been made to ensure that the information is accurate and reliable at the date of publication, no representation or warranty, express or implied, is given as to its accuracy, completeness or continued availability. Certain figures may be estimates or provisional and may subsequently be revised. Market conditions and other external factors may change without notice and may not be reflected in this report. Readers should conduct their own assessment and seek appropriate professional advice before making any decision. To the fullest extent permitted by law, Signal Group accepts no liability for any loss or damage arising from the use of, or reliance on, this report.
Maria holds a M.Sc. in Shipping, Trade and Finance from the Bayes Business School at the City University in London and a B.Sc. in Shipping Economics from the University of Piraeus.
Creating a sustainable world requires us to embark on a journey towards a zero emission future, where every step is a commitment to preserve our planet for future generations.
Albert Greenway
Environmental Scientist, Sustainability Expert
No items found.
Increased Use of Renewable Energy:
Shipping companies are embracing renewable energy sources to power onboard systems and reduce emissions during port operations. Solar panels and wind turbines are being installed on vessels to generate clean energy, reducing reliance on auxiliary engines, and cutting down emissions. Shore power facilities in ports allow ships to connect to the electrical grid, eliminating the need for onboard generators while docked.
Collaboration and Industry Partnerships:
Recognizing that addressing emissions requires collective action, shipping companies, governments, and organizations have formed partnerships and collaborations. These initiatives focus on research and development, sharing best practices, and promoting knowledge transfer. Joint projects aim to develop and deploy innovative technologies, improve infrastructure, and create a supportive regulatory framework to accelerate the industry's transition towards a greener future. The Zero Emission Shipping - Mission Innovation.
To pave the way for a greener future in shipping, the availability of alternative fuels plays a vital role in their widespread adoption. However, this availability is influenced by factors such as port infrastructure, local regulations, and government policies. As the demand for cleaner fuels in shipping rises and environmental regulations become more stringent, efforts are underway to improve the accessibility of these fuels through infrastructure development, collaborations, and investments in production facilities.
Liquefied Natural Gas (LNG) infrastructure has seen significant growth in recent years, resulting in more LNG bunkering facilities and LNG-powered vessels. Nonetheless, the availability of LNG as a marine fuel can still vary depending on the region. To ensure consistent availability worldwide, there is a need for further development of LNG supply chains and infrastructure. For biofuels, their availability hinges on production capacity and the availability of feedstock. Although biofuels are being produced and utilized in various sectors, their availability as a marine fuel remains limited. Scaling up biofuel production and establishing robust supply chains are imperative to ensure wider availability within the shipping industry.Hydrogen, as a fuel for maritime applications, is still in the early stages of infrastructure development. While some hydrogen vessels have been tested or introduced in the first quarter of last year, the infrastructure required for hydrogen production and distribution needs further advancement.
Ammonia, as a marine fuel, currently faces limitations in availability. The production, storage, and handling infrastructure for ammonia need further development to support its widespread use in the shipping industry.Methanol, on the other hand, is already a commercially available fuel and has been used as a blend with conventional fuels in some ships. However, its availability as a standalone marine fuel can still be limited in certain regions. Bureau Veritas in October 2022 published a White Paper for the Alternative Fuels Outlook. This white paper provides a comprehensive overview of alternative fuels for the shipping industry, taking into account key factors such as technological maturity, availability, safety, emissions, and regulations.
Creating a sustainable world requires us to embark on a journey towards a zero emission future, where every step is a commitment to preserve our planet for future generations.
Albert Greenway
Environmental Scientist, Sustainability Expert
Increased Use of Renewable Energy:
Shipping companies are embracing renewable energy sources to power onboard systems and reduce emissions during port operations. Solar panels and wind turbines are being installed on vessels to generate clean energy, reducing reliance on auxiliary engines, and cutting down emissions. Shore power facilities in ports allow ships to connect to the electrical grid, eliminating the need for onboard generators while docked.
Collaboration and Industry Partnerships:
Recognizing that addressing emissions requires collective action, shipping companies, governments, and organizations have formed partnerships and collaborations. These initiatives focus on research and development, sharing best practices, and promoting knowledge transfer. Joint projects aim to develop and deploy innovative technologies, improve infrastructure, and create a supportive regulatory framework to accelerate the industry's transition towards a greener future. The Zero Emission Shipping - Mission Innovation.
To pave the way for a greener future in shipping, the availability of alternative fuels plays a vital role in their widespread adoption. However, this availability is influenced by factors such as port infrastructure, local regulations, and government policies. As the demand for cleaner fuels in shipping rises and environmental regulations become more stringent, efforts are underway to improve the accessibility of these fuels through infrastructure development, collaborations, and investments in production facilities.
Liquefied Natural Gas (LNG) infrastructure has seen significant growth in recent years, resulting in more LNG bunkering facilities and LNG-powered vessels. Nonetheless, the availability of LNG as a marine fuel can still vary depending on the region. To ensure consistent availability worldwide, there is a need for further development of LNG supply chains and infrastructure. For biofuels, their availability hinges on production capacity and the availability of feedstock. Although biofuels are being produced and utilized in various sectors, their availability as a marine fuel remains limited. Scaling up biofuel production and establishing robust supply chains are imperative to ensure wider availability within the shipping industry.Hydrogen, as a fuel for maritime applications, is still in the early stages of infrastructure development. While some hydrogen vessels have been tested or introduced in the first quarter of last year, the infrastructure required for hydrogen production and distribution needs further advancement.
Ammonia, as a marine fuel, currently faces limitations in availability. The production, storage, and handling infrastructure for ammonia need further development to support its widespread use in the shipping industry.Methanol, on the other hand, is already a commercially available fuel and has been used as a blend with conventional fuels in some ships. However, its availability as a standalone marine fuel can still be limited in certain regions. Bureau Veritas in October 2022 published a White Paper for the Alternative Fuels Outlook. This white paper provides a comprehensive overview of alternative fuels for the shipping industry, taking into account key factors such as technological maturity, availability, safety, emissions, and regulations.