Subscribe for our latest news, straight to your inbox:
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Share this post
SPOTLIGHT OF THE WEEK | SEGMENT COMPARISON
Capesize and Panamax Led as Asian Supramax/Handy Supply Tightened
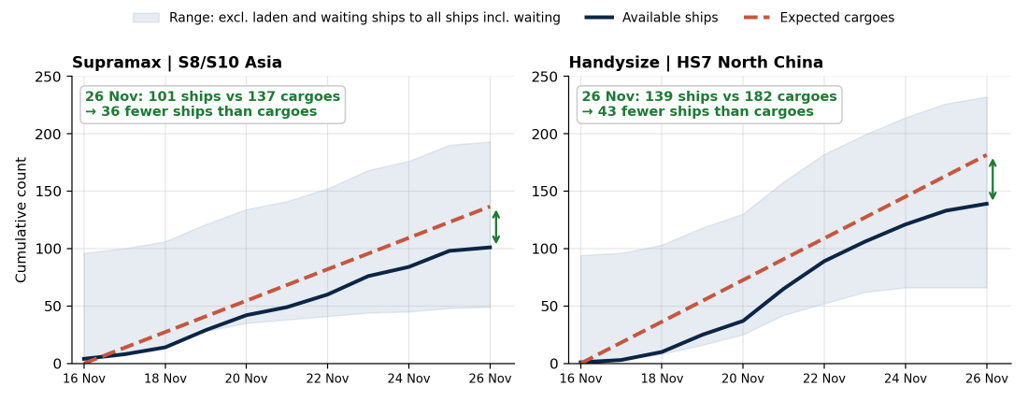
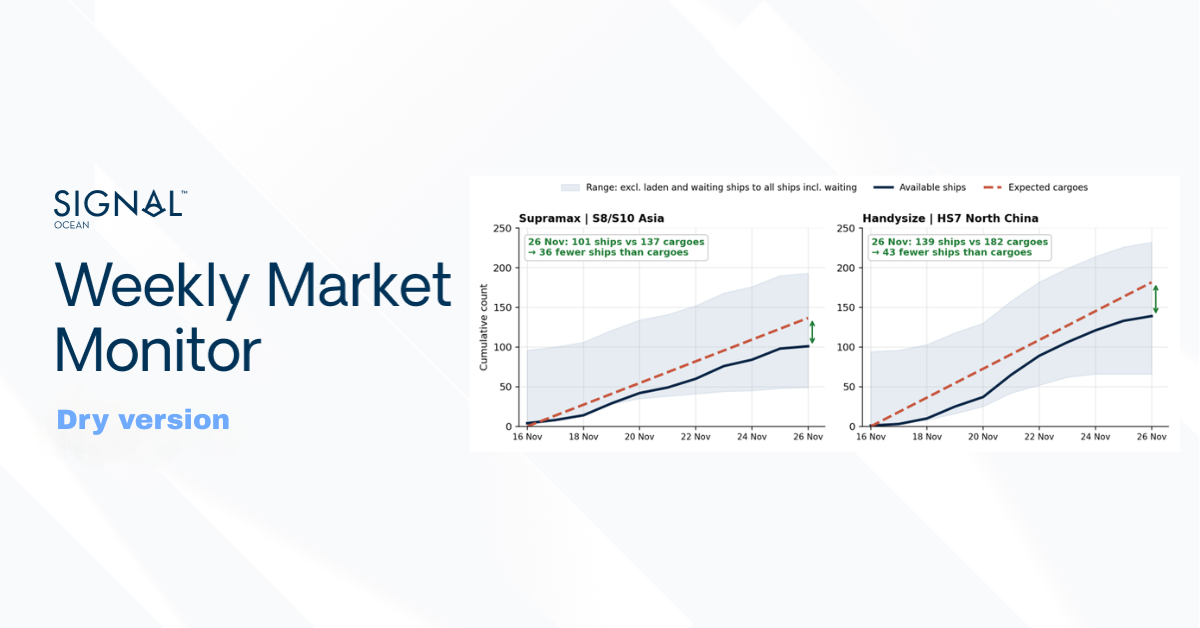
Figure 1: Supramax S8/S10 Asia and Handysize HS7 North China: cumulative available ships (excluding waiting vessels) vs expected cargoes, day by day from the 16 November 2026 snapshot to 26 November. Shaded band = range from excluding laden and waiting ships (bottom) to all ships including waiting (top). Exact route values (Source: Signal Ocean).
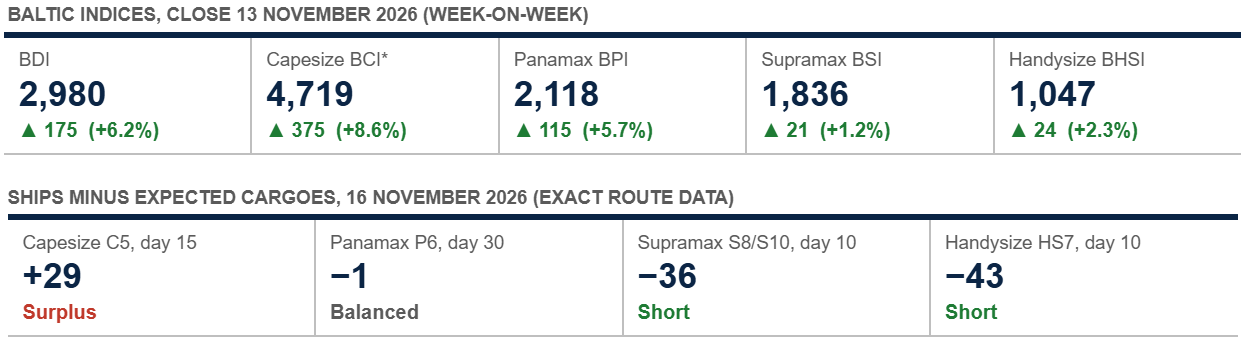
Capesize and Panamax led the weekly freight gains, with the BCI rising 8.6% and the BPI 5.7%, compared with more modest increases of 1.2% for Supramax and 2.3% for Handysize. The improvement was largely concentrated on Atlantic routes, particularly for the larger vessel segments. However, forward vessel availability as of 16 November points to a different pattern across regions and vessel sizes. While C5 West Australia–China retained a surplus of 29 vessels against expected cargoes by day 15 and P6 Singapore–Atlantic was broadly balanced by day 30, Asian Supramax and Handysize routes showed tighter conditions. On S8/S10, expected cargoes exceeded available vessels by 36 over the next 10 days, compared with 19 a week earlier, while the shortfall on HS7 North China widened from 36 to 43 vessels. Despite this tightening, Asian Supramax spot rates continued to decline, indicating that the stronger forward cargo demand relative to available tonnage has not yet been reflected in freight earnings.
FORWARD VESSEL AVAILABILITY | WHAT CHANGED
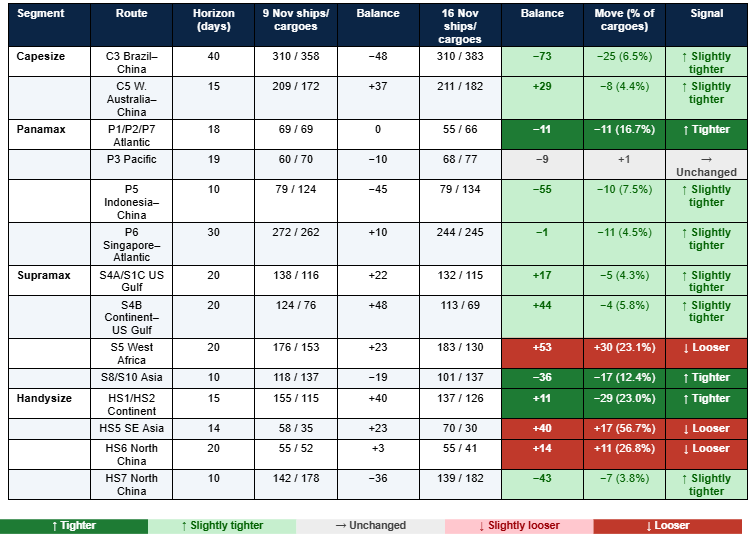
Between the 9 and 16 November snapshots, ten of 14 routes tightened, three loosened and one was unchanged; horizons differ by route, from 10 to 40 days. The largest moves were on C3 Brazil–China (deficit about 48 → 73 by day 40), S8/S10 Asia (19 → 36 by day 10), HS1/HS2 Continent (surplus 40 → 11 by day 15) and S5 West Africa (surplus 23 → 53 by day 20).
Table 1: Cumulative available ships (excluding waiting vessels) minus expected cargoes at the route-specific horizon. Negative values indicate a conditional deficit. Signal rule, applied in order: (1) move of 3 ships or less, or under 2.5% of 16 November expected cargoes = Unchanged; (2) under 10% = Slightly tighter/looser; (3) 10% or more = Tighter/Looser. A fall in the balance = tighter (Source: Signal Ocean; snapshots 9 and 16 November 2026).
FREIGHT MARKET OVERVIEW
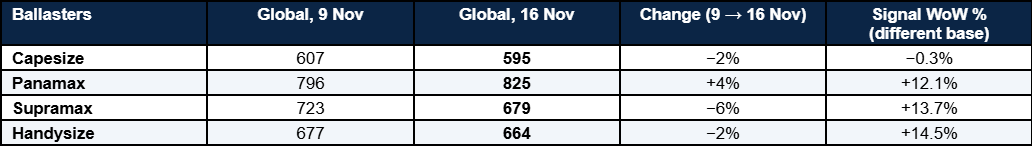
Table 2: Global ballasters (empty ships heading to load). The report compares fixed 9 and 16 November counts. (Source: Signal Ocean).
KEY TAKEAWAY
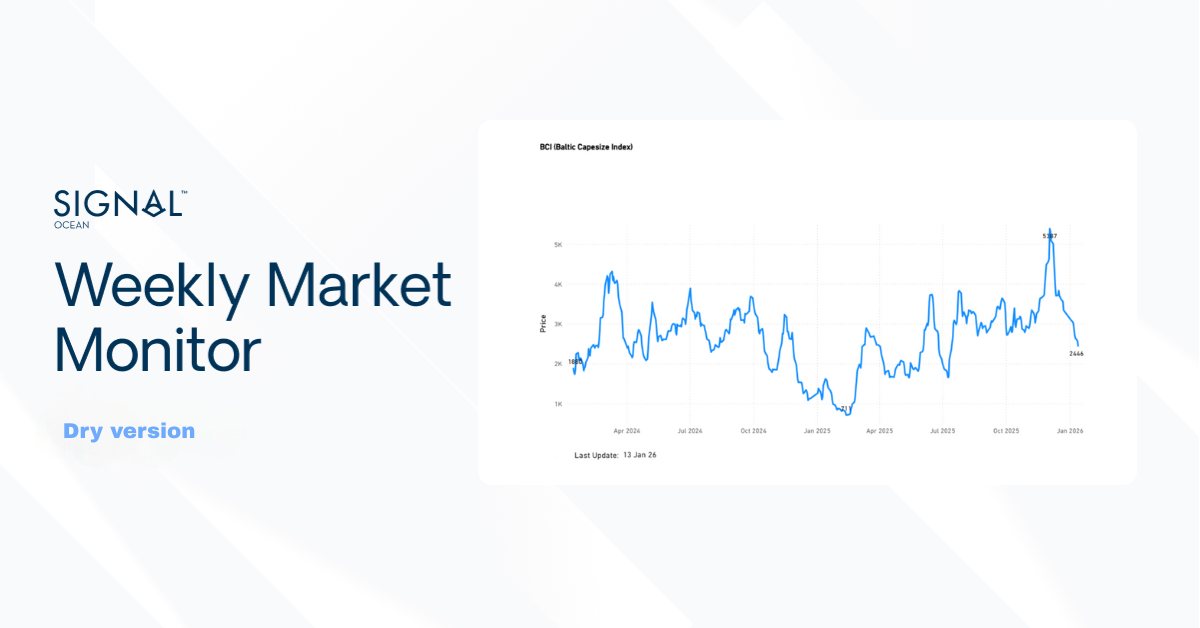
During the week ending November 13, the Baltic Dry Index (BDI) climbed to 2,980, supported by gains across all four vessel classes, led by Capesize and Panamax ships on Atlantic routes. However, forward data from November 16 indicated a shifting market dynamic: while Capesize and Panamax routes remained balanced or in oversupply, Asian Supramax and Handysize sectors faced vessel shortages that had not yet been reflected in their spot rates.
CAPESIZE
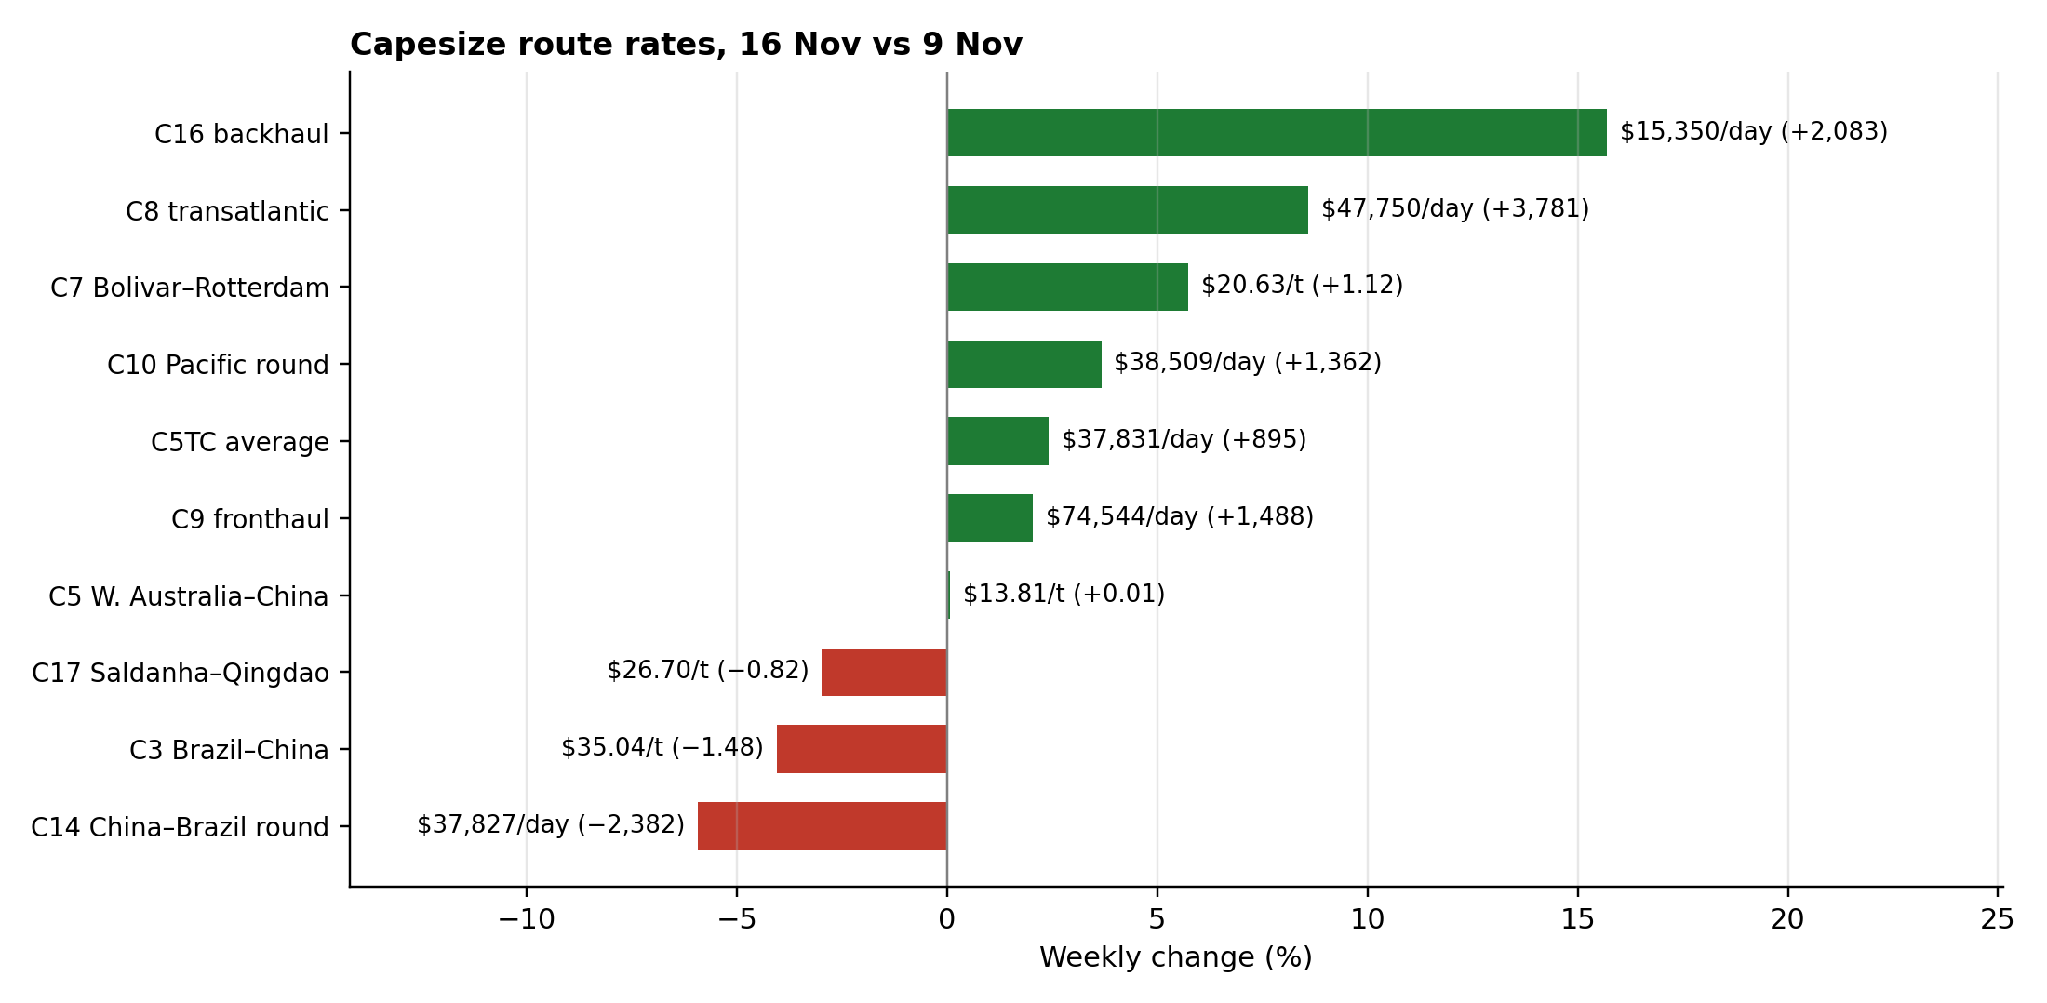
Freight. The BCI closed the week at 4,719 on 13 November, up 375 points, and eased 161 points to 4,558 on Monday 16 November. Over the week to 16 November, C8 transatlantic rose $3,781/day to $47,750/day and C9 fronthaul rose $1,488/day to $74,544/day, the highest-earning route. C14 China–Brazil fell $2,382/day to $37,827/day. C3 Brazil–China fell $1.48/t to $35.04/t, while C5 West Australia–China was flat at $13.81/t, which narrowed the C3–C5 spread to $21.23/t from $22.72/t.
Figure 2: Capesize route rates and weekly change, 16 November vs 9 November 2026 assessments (Source: Baltic Exchange/Signal Ocean).
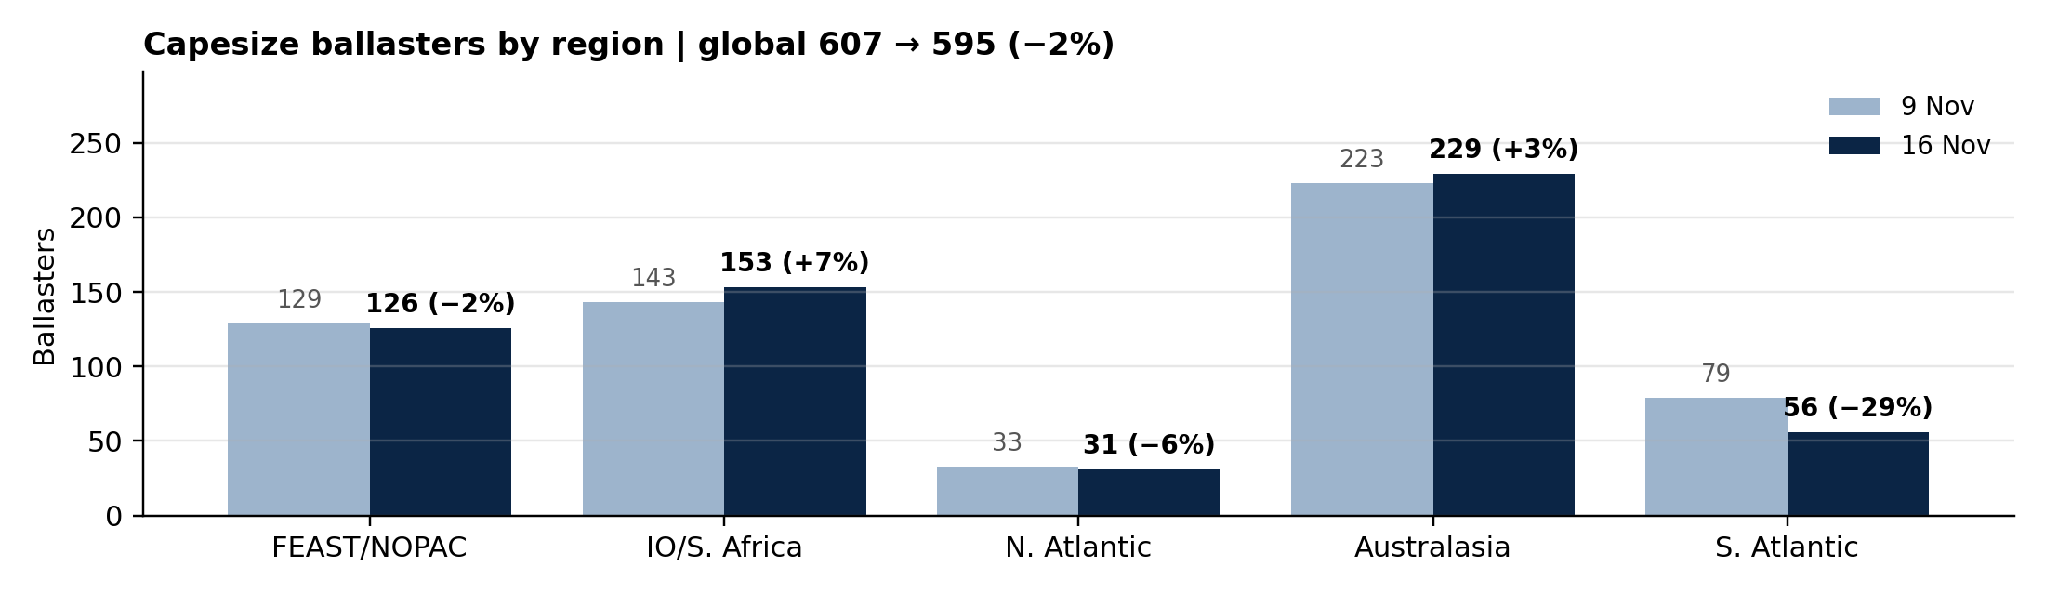
Figure 3: Capesize ballasters by region, 9 and 16 November 2026 (Source: Signal Ocean).
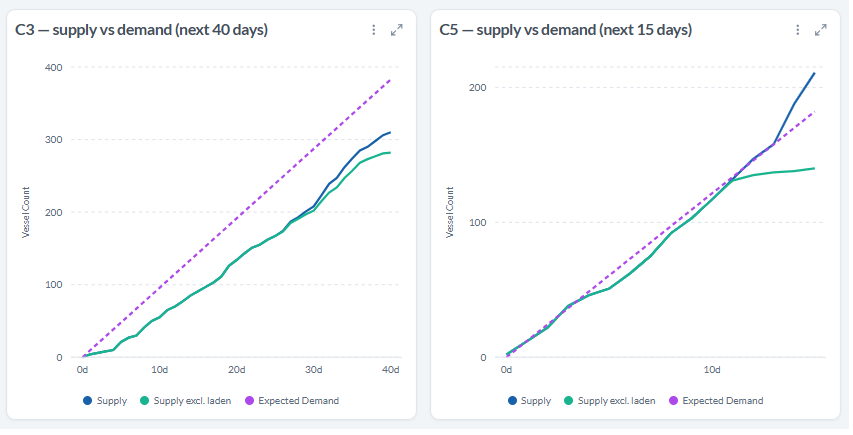
Figure 4: Capesize available ships (excluding waiting vessels) vs expected cargoes, C3 (40-day horizon) and C5 (15-day horizon), 16 November 2026 (Source: Signal Ocean).
The C3 Brazil–China rate fell over the week even though the 16 November snapshot showed an approximately 73-ship deficit at the 40-day horizon. C5, on a 15-day horizon, showed a 29-ship surplus. Global ballasters fell from 607 to 595, led by the South Atlantic (79 to 56).
PANAMAX
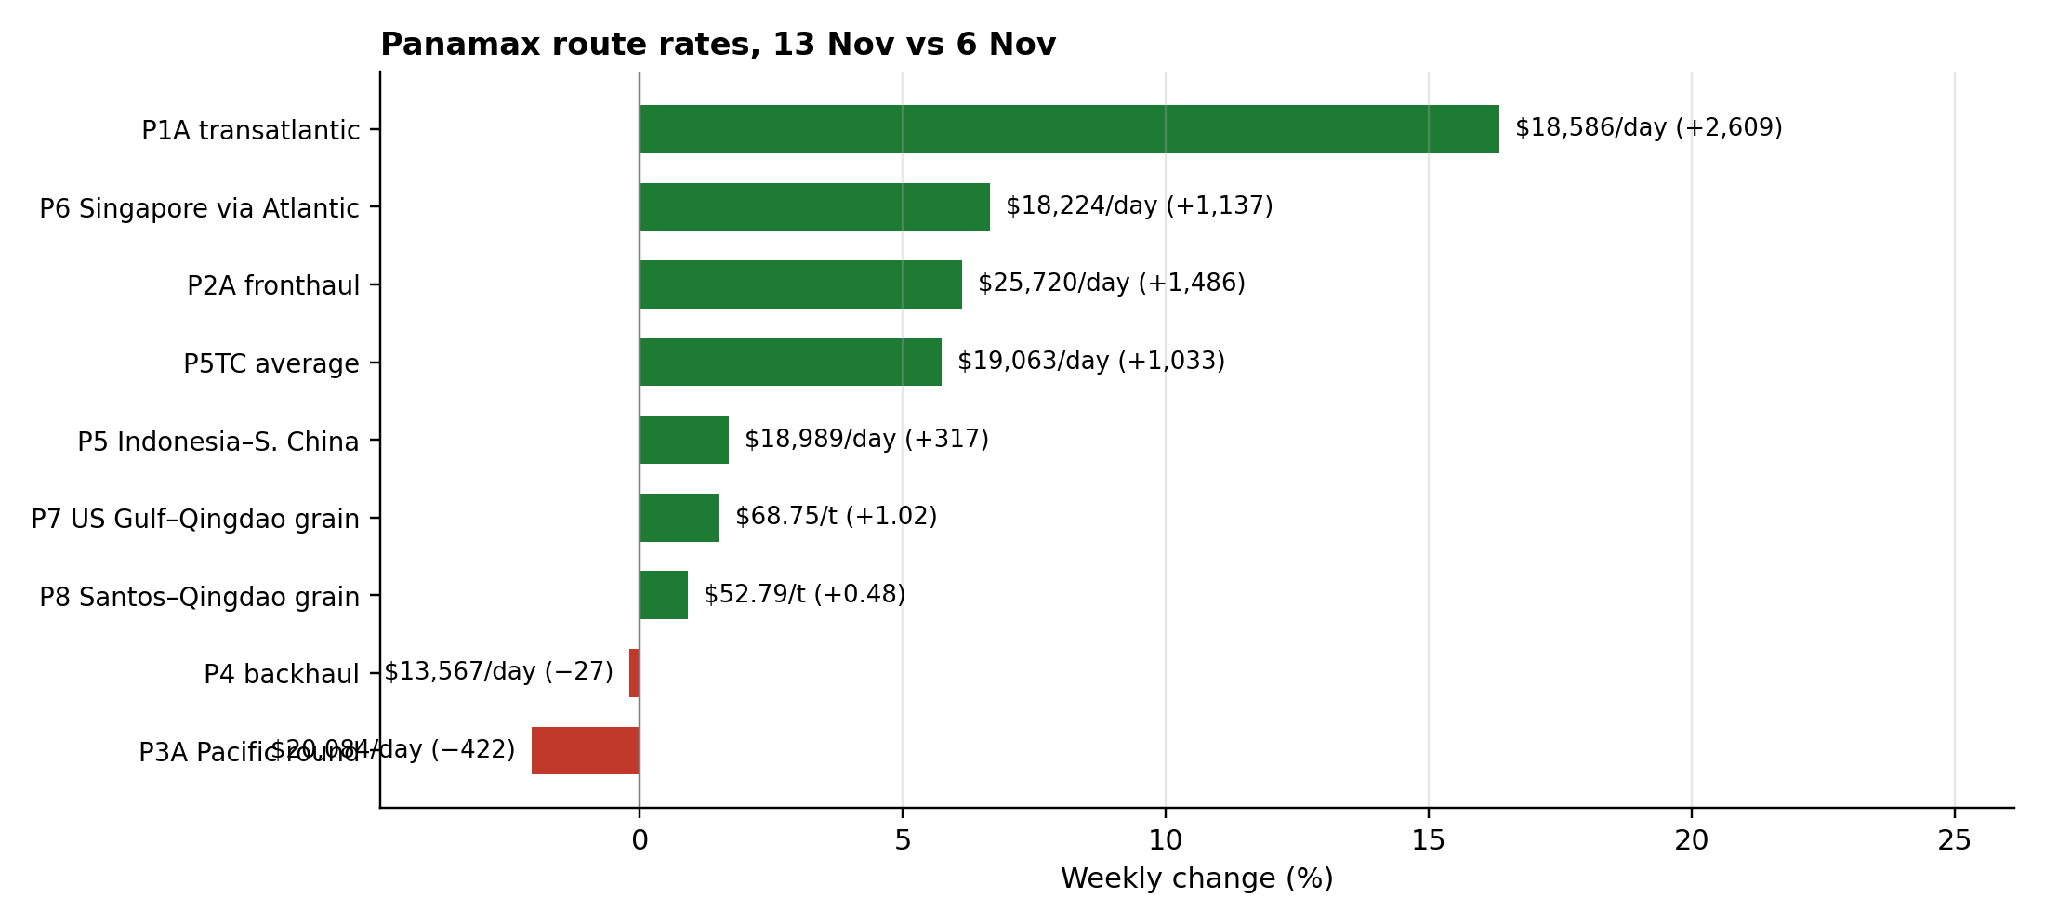
Freight. The BPI rose 115 points to 2,118. The Atlantic led: P1A transatlantic rose $2,609/day to $18,586/day and P2A fronthaul rose $1,486/day to $25,720/day, the highest-earning route. P6 rose $1,137/day to $18,224/day and P5 rose $317/day to $18,989/day, while P3A Pacific fell $422/day to $20,084/day. Grain routes P7 and P8 edged up to $68.75/t and $52.79/t.
Figure 5: Panamax route rates and weekly change, 13 November vs 6 November 2026 (Source: Baltic Exchange/Signal Ocean).
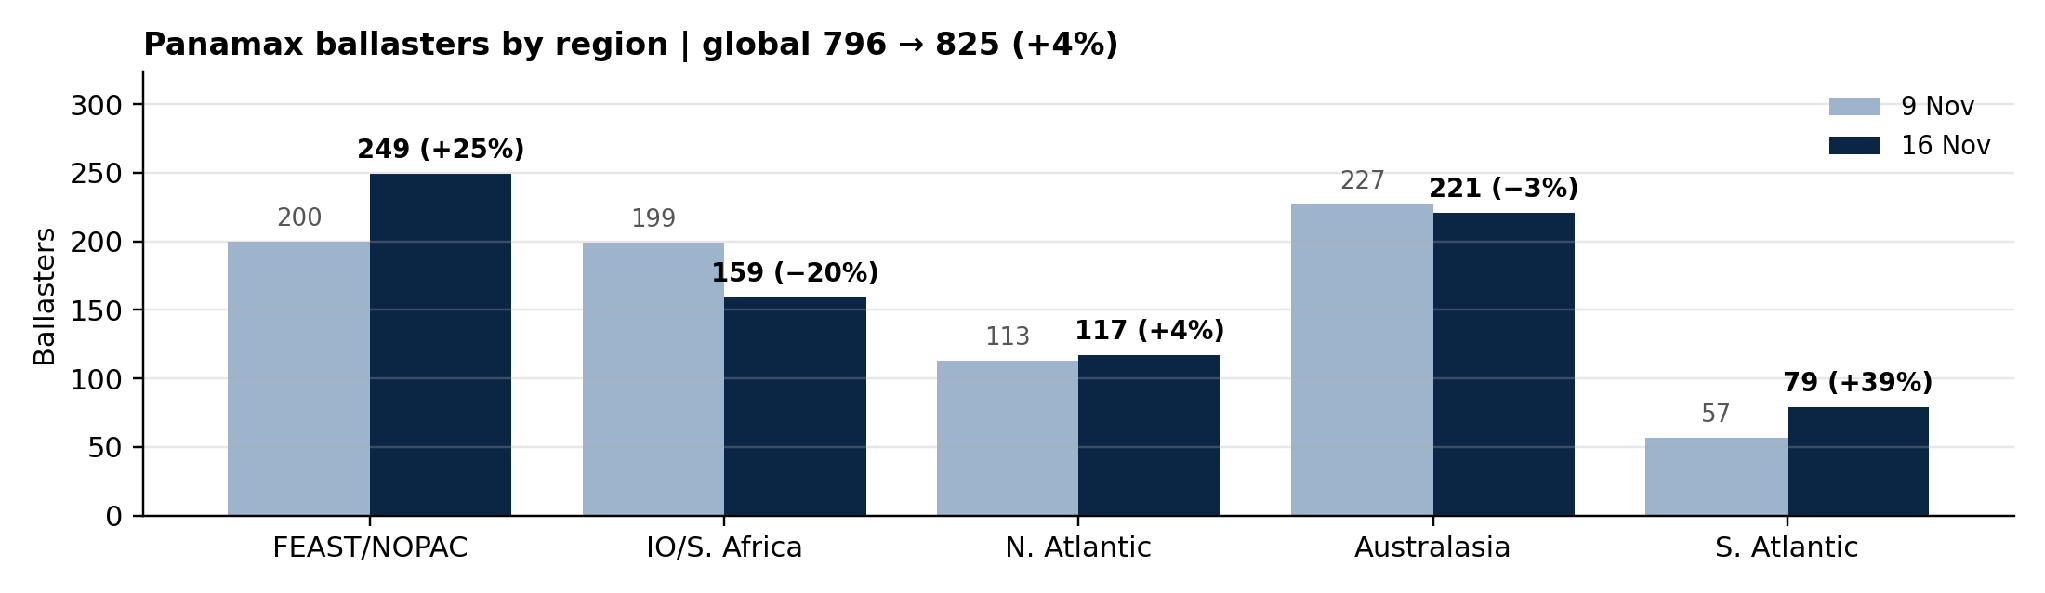
Figure 6: Panamax ballasters by region, 9 and 16 November 2026 (Source: Signal Ocean).
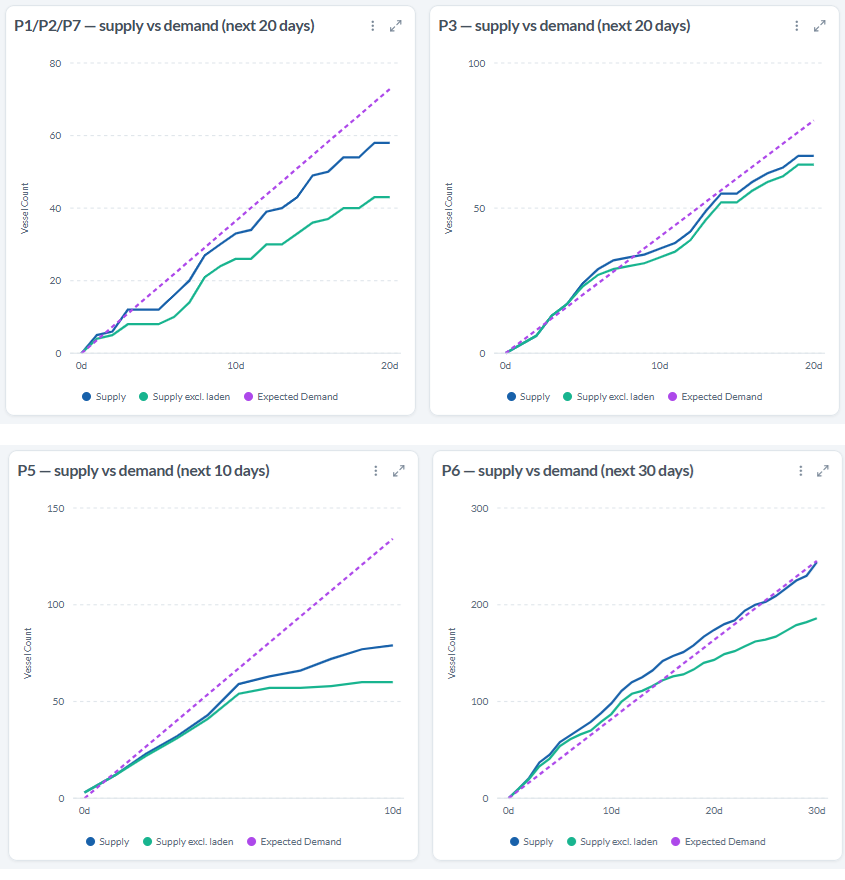
Figure 7: Panamax available ships (excluding waiting vessels) vs expected cargoes: P1/P2/P7 and P3 (20 days), P5 (10 days), P6 (30 days), 16 November 2026 (Source: Signal Ocean).
The P5TC was still 12.9% below its level a month earlier. Far East/North Pacific ballasters rose from 200 to 249, while P5 Indonesia–China showed a deficit of about 55 ships by day 10 and P1/P2/P7 about 11 by day 18; P6 was level at day 30. A larger regional ballast pool does not translate directly into ships eligible for a specific route and loading window.
SUPRAMAX
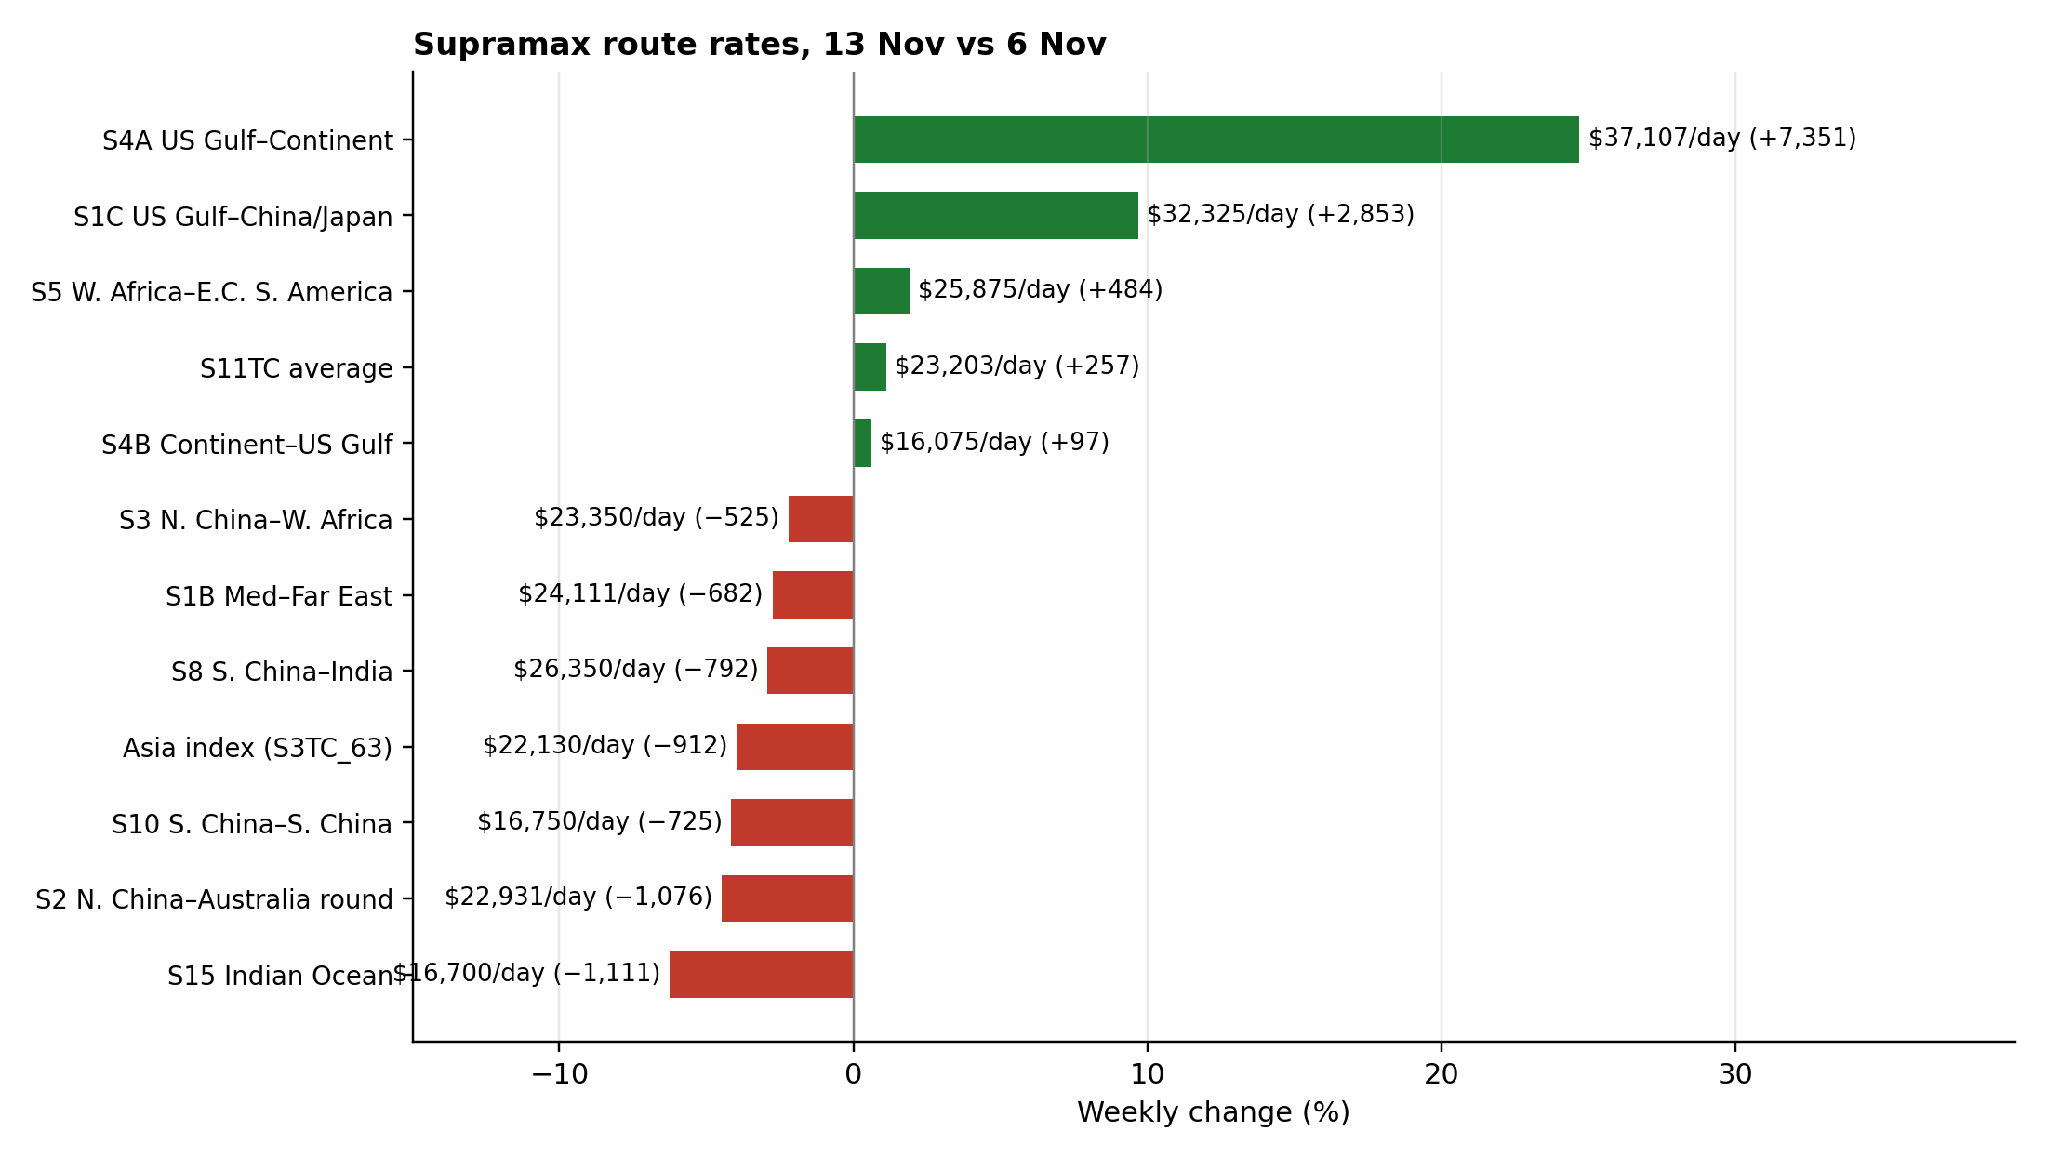
Freight. The BSI rose 21 points to 1,836. Supramax gains were concentrated in the Atlantic: S4A US Gulf rose $7,351/day to $37,107/day and S1C $2,853/day to $32,325/day. Asian and Indian Ocean routes fell: S2 −$1,076/day, S8 −$792/day, S10 −$725/day and S15 −$1,111/day; the Asia index (S3TC_63) lost $912/day to $22,130/day.
Figure 8: Supramax route rates and weekly change, 13 November vs 6 November 2026 (Source: Baltic Exchange/Signal Ocean).
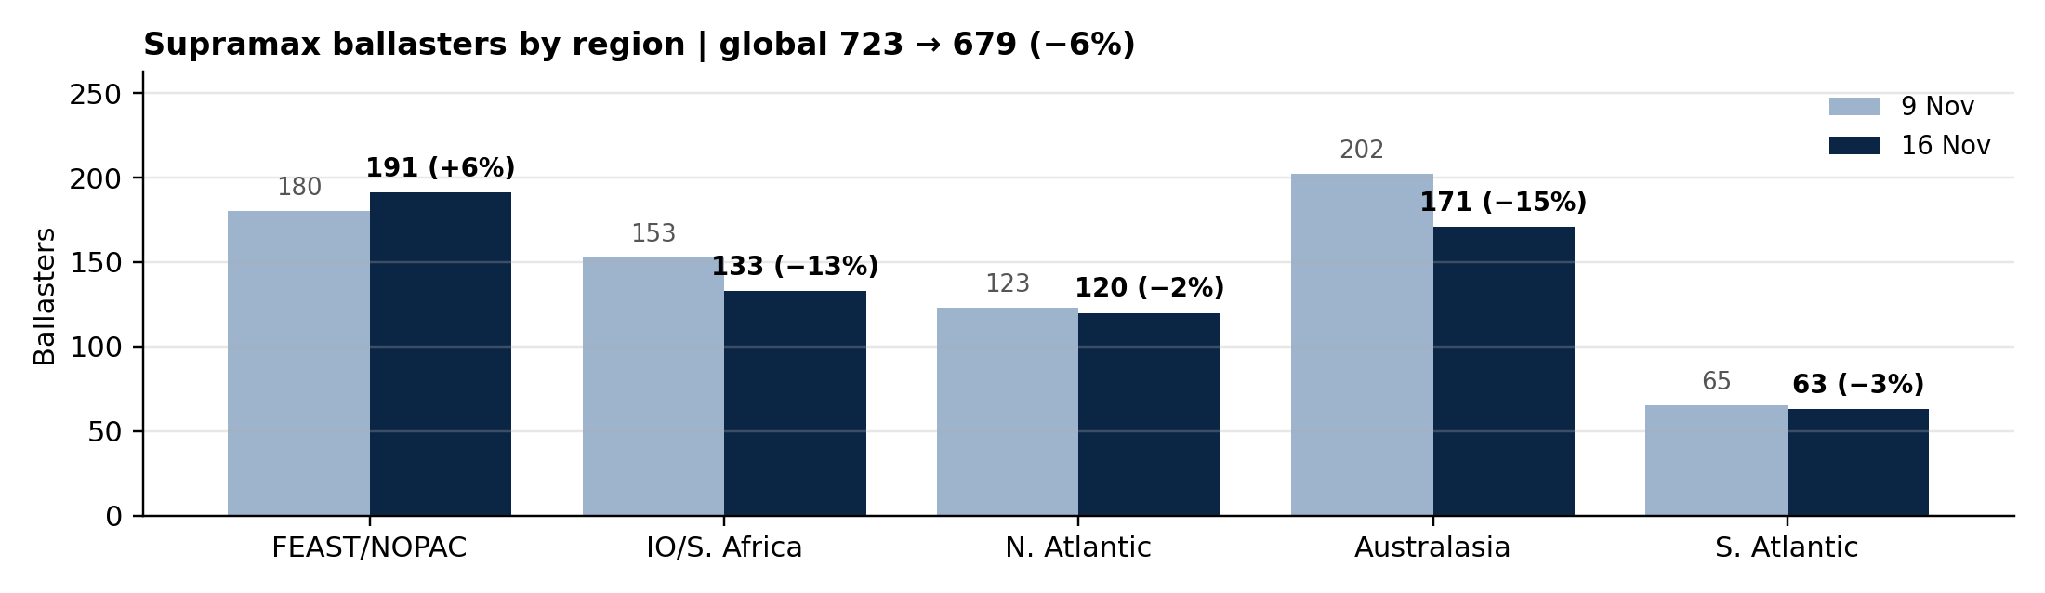
Figure 9: Supramax ballasters by region, 9 and 16 November 2026 (Source: Signal Ocean).
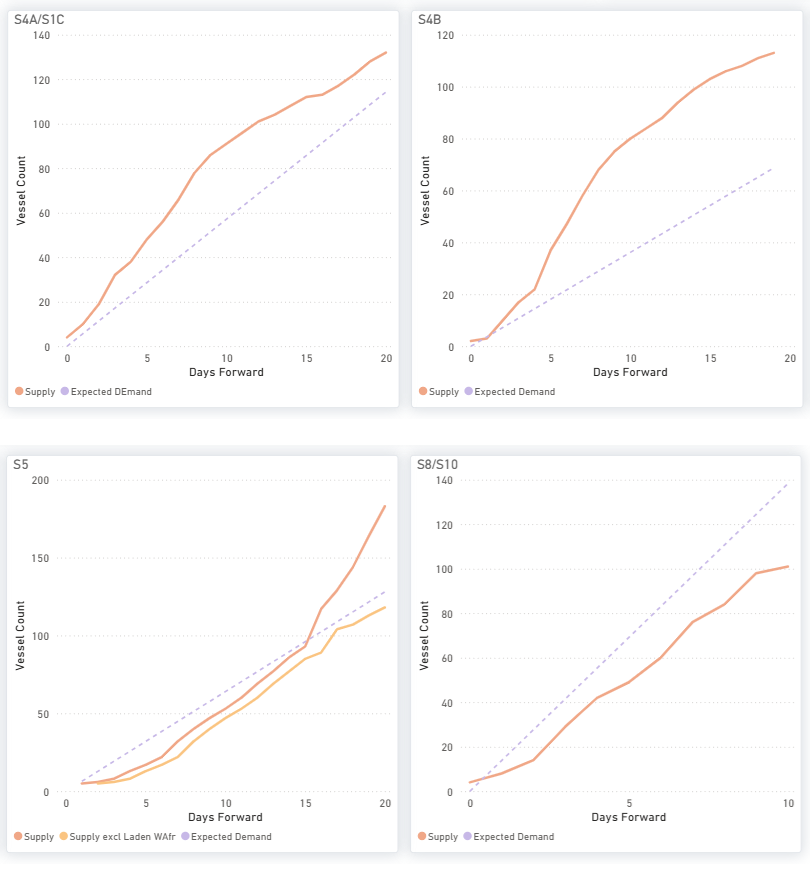
Figure 10: Supramax available ships vs expected cargoes: S4A/S1C, S4B and S5 (20 days), S8/S10 (10 days), 16 November 2026 (Source: Signal Ocean).
On S8/S10, the forward balance and the rate moves pointed in opposite directions. S5 West Africa showed a surplus of about 53 ships by day 20, so the Supramax picture was uneven across basins. Ballasters fell from 723 to 679, with Australasia down from 202 to 171 and the Indian Ocean/South Africa from 153 to 133.
HANDYSIZE
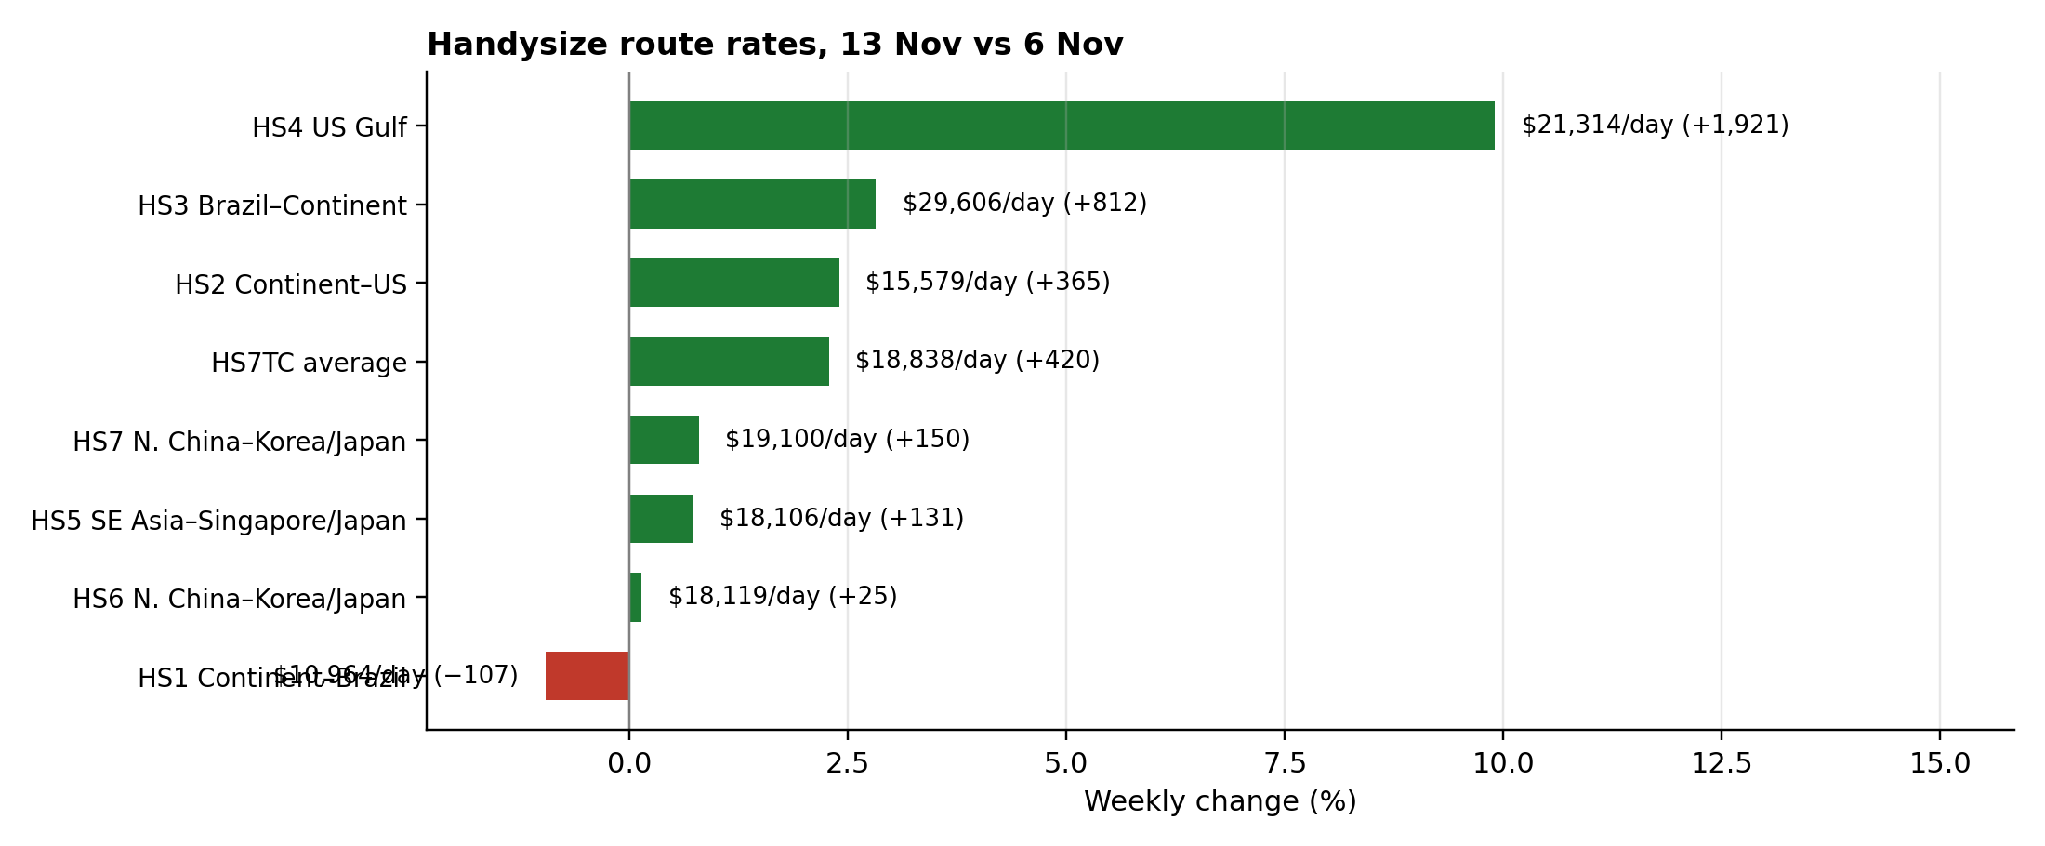
Freight. The BHSI rose 24 points to 1,047. HS4 US Gulf led, up $1,921/day to $21,314/day; HS3 South Atlantic rose $812/day to $29,606/day, the highest-earning route. In Asia, HS7 rose $150/day to $19,100/day, HS5 rose $131/day, and HS6 rose $25/day.
Figure 11: Handysize route rates and weekly change, 13 November vs 6 November 2026 (Source: Baltic Exchange/Signal Ocean).
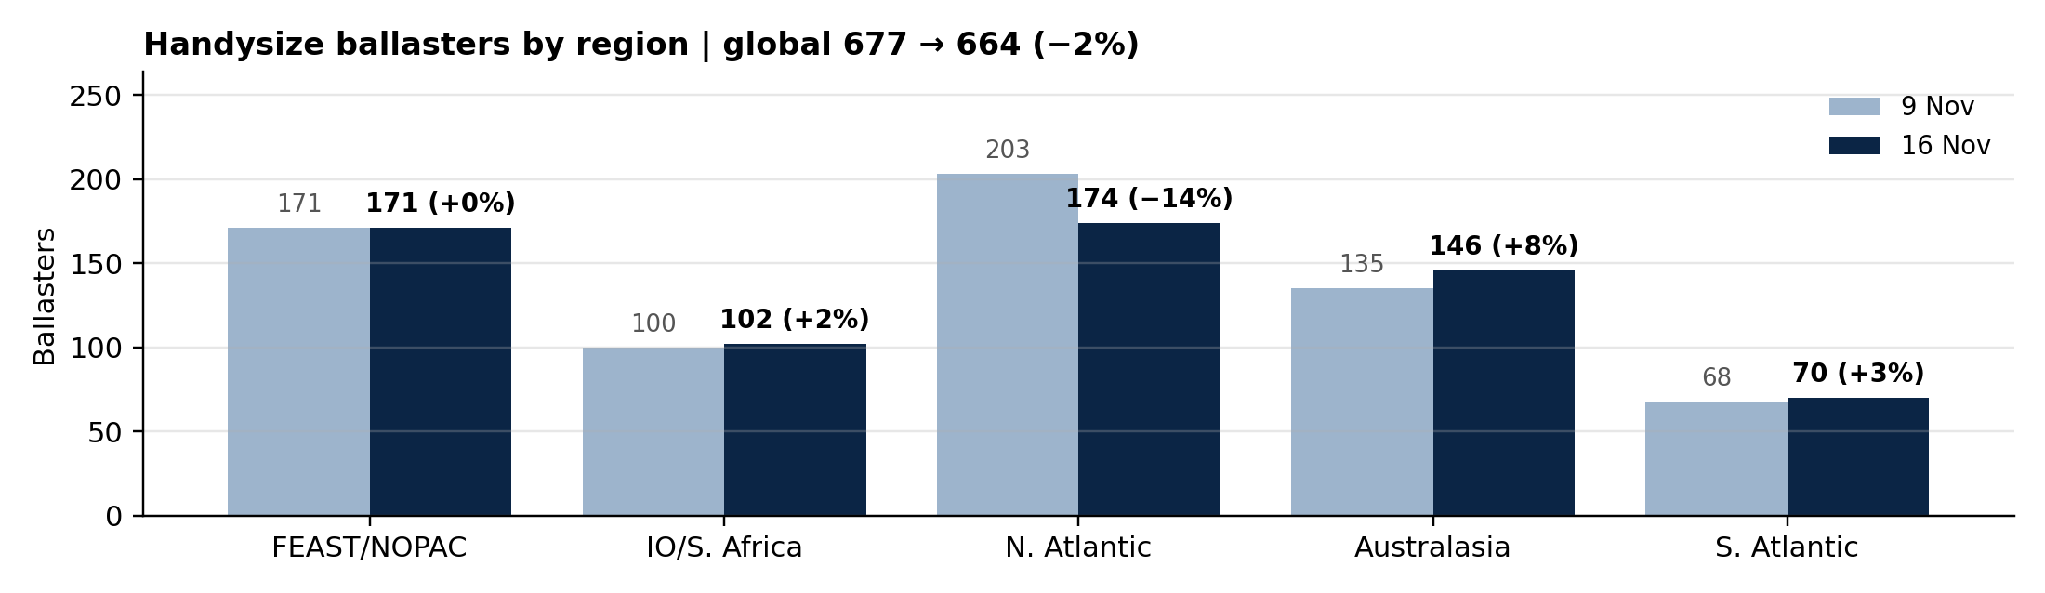
Figure 12: Handysize ballasters by region, 9 and 16 November 2026 (Source: Signal Ocean).
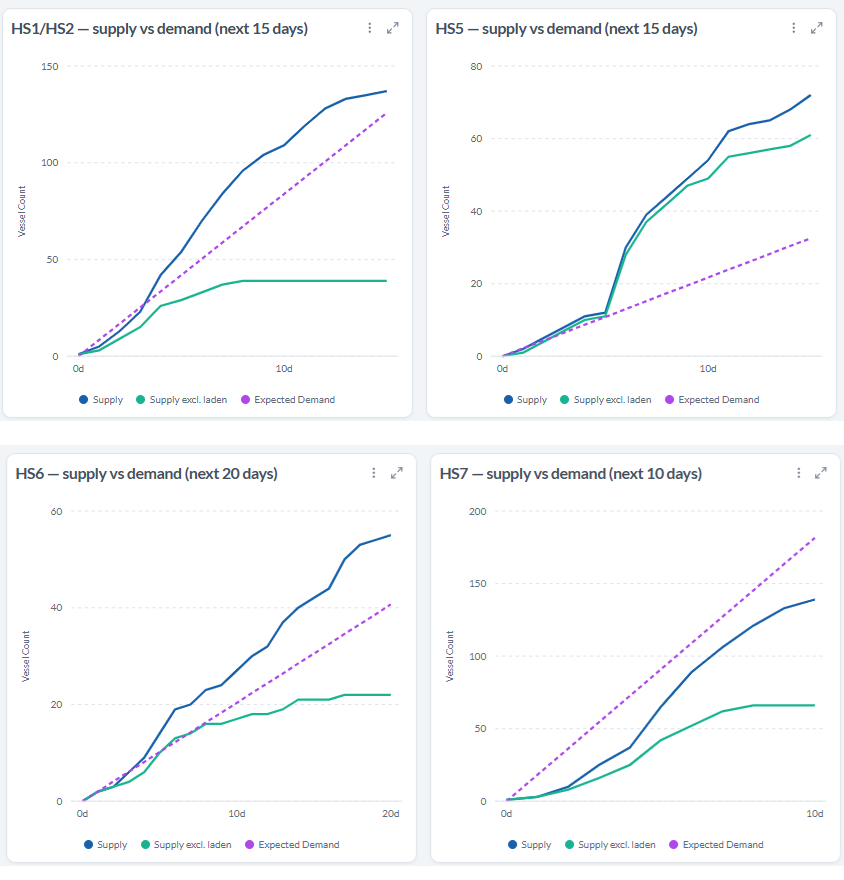
Figure 13: Handysize available ships vs expected cargoes: HS1/HS2 and HS5 (15 days), HS6 (20 days), HS7 (10 days), 16 November 2026 (Source: Signal Ocean).
The BHSI set a new 52-week high. HS7 North China showed a deficit of about 43 ships by day 10 while its rate rose only modestly; HS5 Southeast Asia and HS6 North China showed surpluses of about 40 and 14 ships, so the Asian picture was not uniformly tight. Ballasters fell from 677 to 664, with the North Atlantic down from 203 to 174.
Disclaimer: This report has been prepared by Signal Group for general information purposes only. It does not constitute, and should not be relied upon as, investment, financial, trading, legal or commercial advice, or as a recommendation to enter into any transaction. While reasonable efforts have been made to ensure that the information is accurate and reliable at the date of publication, no representation or warranty, express or implied, is given as to its accuracy, completeness or continued availability. Certain figures may be estimates or provisional and may subsequently be revised. Market conditions and other external factors may change without notice and may not be reflected in this report. Readers should conduct their own assessment and seek appropriate professional advice before making any decision. To the fullest extent permitted by law, Signal Group accepts no liability for any loss or damage arising from the use of, or reliance on, this report.
Maria holds a M.Sc. in Shipping, Trade and Finance from the Bayes Business School at the City University in London and a B.Sc. in Shipping Economics from the University of Piraeus.
Creating a sustainable world requires us to embark on a journey towards a zero emission future, where every step is a commitment to preserve our planet for future generations.
Albert Greenway
Environmental Scientist, Sustainability Expert
No items found.
Increased Use of Renewable Energy:
Shipping companies are embracing renewable energy sources to power onboard systems and reduce emissions during port operations. Solar panels and wind turbines are being installed on vessels to generate clean energy, reducing reliance on auxiliary engines, and cutting down emissions. Shore power facilities in ports allow ships to connect to the electrical grid, eliminating the need for onboard generators while docked.
Collaboration and Industry Partnerships:
Recognizing that addressing emissions requires collective action, shipping companies, governments, and organizations have formed partnerships and collaborations. These initiatives focus on research and development, sharing best practices, and promoting knowledge transfer. Joint projects aim to develop and deploy innovative technologies, improve infrastructure, and create a supportive regulatory framework to accelerate the industry's transition towards a greener future. The Zero Emission Shipping - Mission Innovation.
To pave the way for a greener future in shipping, the availability of alternative fuels plays a vital role in their widespread adoption. However, this availability is influenced by factors such as port infrastructure, local regulations, and government policies. As the demand for cleaner fuels in shipping rises and environmental regulations become more stringent, efforts are underway to improve the accessibility of these fuels through infrastructure development, collaborations, and investments in production facilities.
Liquefied Natural Gas (LNG) infrastructure has seen significant growth in recent years, resulting in more LNG bunkering facilities and LNG-powered vessels. Nonetheless, the availability of LNG as a marine fuel can still vary depending on the region. To ensure consistent availability worldwide, there is a need for further development of LNG supply chains and infrastructure. For biofuels, their availability hinges on production capacity and the availability of feedstock. Although biofuels are being produced and utilized in various sectors, their availability as a marine fuel remains limited. Scaling up biofuel production and establishing robust supply chains are imperative to ensure wider availability within the shipping industry.Hydrogen, as a fuel for maritime applications, is still in the early stages of infrastructure development. While some hydrogen vessels have been tested or introduced in the first quarter of last year, the infrastructure required for hydrogen production and distribution needs further advancement.
Ammonia, as a marine fuel, currently faces limitations in availability. The production, storage, and handling infrastructure for ammonia need further development to support its widespread use in the shipping industry.Methanol, on the other hand, is already a commercially available fuel and has been used as a blend with conventional fuels in some ships. However, its availability as a standalone marine fuel can still be limited in certain regions. Bureau Veritas in October 2022 published a White Paper for the Alternative Fuels Outlook. This white paper provides a comprehensive overview of alternative fuels for the shipping industry, taking into account key factors such as technological maturity, availability, safety, emissions, and regulations.
Creating a sustainable world requires us to embark on a journey towards a zero emission future, where every step is a commitment to preserve our planet for future generations.
Albert Greenway
Environmental Scientist, Sustainability Expert
Increased Use of Renewable Energy:
Shipping companies are embracing renewable energy sources to power onboard systems and reduce emissions during port operations. Solar panels and wind turbines are being installed on vessels to generate clean energy, reducing reliance on auxiliary engines, and cutting down emissions. Shore power facilities in ports allow ships to connect to the electrical grid, eliminating the need for onboard generators while docked.
Collaboration and Industry Partnerships:
Recognizing that addressing emissions requires collective action, shipping companies, governments, and organizations have formed partnerships and collaborations. These initiatives focus on research and development, sharing best practices, and promoting knowledge transfer. Joint projects aim to develop and deploy innovative technologies, improve infrastructure, and create a supportive regulatory framework to accelerate the industry's transition towards a greener future. The Zero Emission Shipping - Mission Innovation.
To pave the way for a greener future in shipping, the availability of alternative fuels plays a vital role in their widespread adoption. However, this availability is influenced by factors such as port infrastructure, local regulations, and government policies. As the demand for cleaner fuels in shipping rises and environmental regulations become more stringent, efforts are underway to improve the accessibility of these fuels through infrastructure development, collaborations, and investments in production facilities.
Liquefied Natural Gas (LNG) infrastructure has seen significant growth in recent years, resulting in more LNG bunkering facilities and LNG-powered vessels. Nonetheless, the availability of LNG as a marine fuel can still vary depending on the region. To ensure consistent availability worldwide, there is a need for further development of LNG supply chains and infrastructure. For biofuels, their availability hinges on production capacity and the availability of feedstock. Although biofuels are being produced and utilized in various sectors, their availability as a marine fuel remains limited. Scaling up biofuel production and establishing robust supply chains are imperative to ensure wider availability within the shipping industry.Hydrogen, as a fuel for maritime applications, is still in the early stages of infrastructure development. While some hydrogen vessels have been tested or introduced in the first quarter of last year, the infrastructure required for hydrogen production and distribution needs further advancement.
Ammonia, as a marine fuel, currently faces limitations in availability. The production, storage, and handling infrastructure for ammonia need further development to support its widespread use in the shipping industry.Methanol, on the other hand, is already a commercially available fuel and has been used as a blend with conventional fuels in some ships. However, its availability as a standalone marine fuel can still be limited in certain regions. Bureau Veritas in October 2022 published a White Paper for the Alternative Fuels Outlook. This white paper provides a comprehensive overview of alternative fuels for the shipping industry, taking into account key factors such as technological maturity, availability, safety, emissions, and regulations.